Europe Surges While Wall Street Stumbles: S&P 500 Fights to Hold 7,599 as the Chip Rout Deepens
Indices This Week | 19–23 October 2026
Europe Surges While Wall Street Stumbles: S&P 500 Fights to Hold 7,599 as the Chip Rout Deepens
- Weekly bias
- Divergent
- Dow, DAX and FTSE firm; S&P 500, Nikkei and Hang Seng weaker
- Expected volatility
- Elevated
- VIX near 20, Nikkei volatility above 36, Fed in blackout
- Key event
- Tesla and Meta results
- Wednesday 21 Oct, after the US close (from 20:00 GMT)
- Key pivot level
- 7,599
- S&P 500 average and channel base; a weekly close below shifts the bias for US and Asian indices
Market Overview
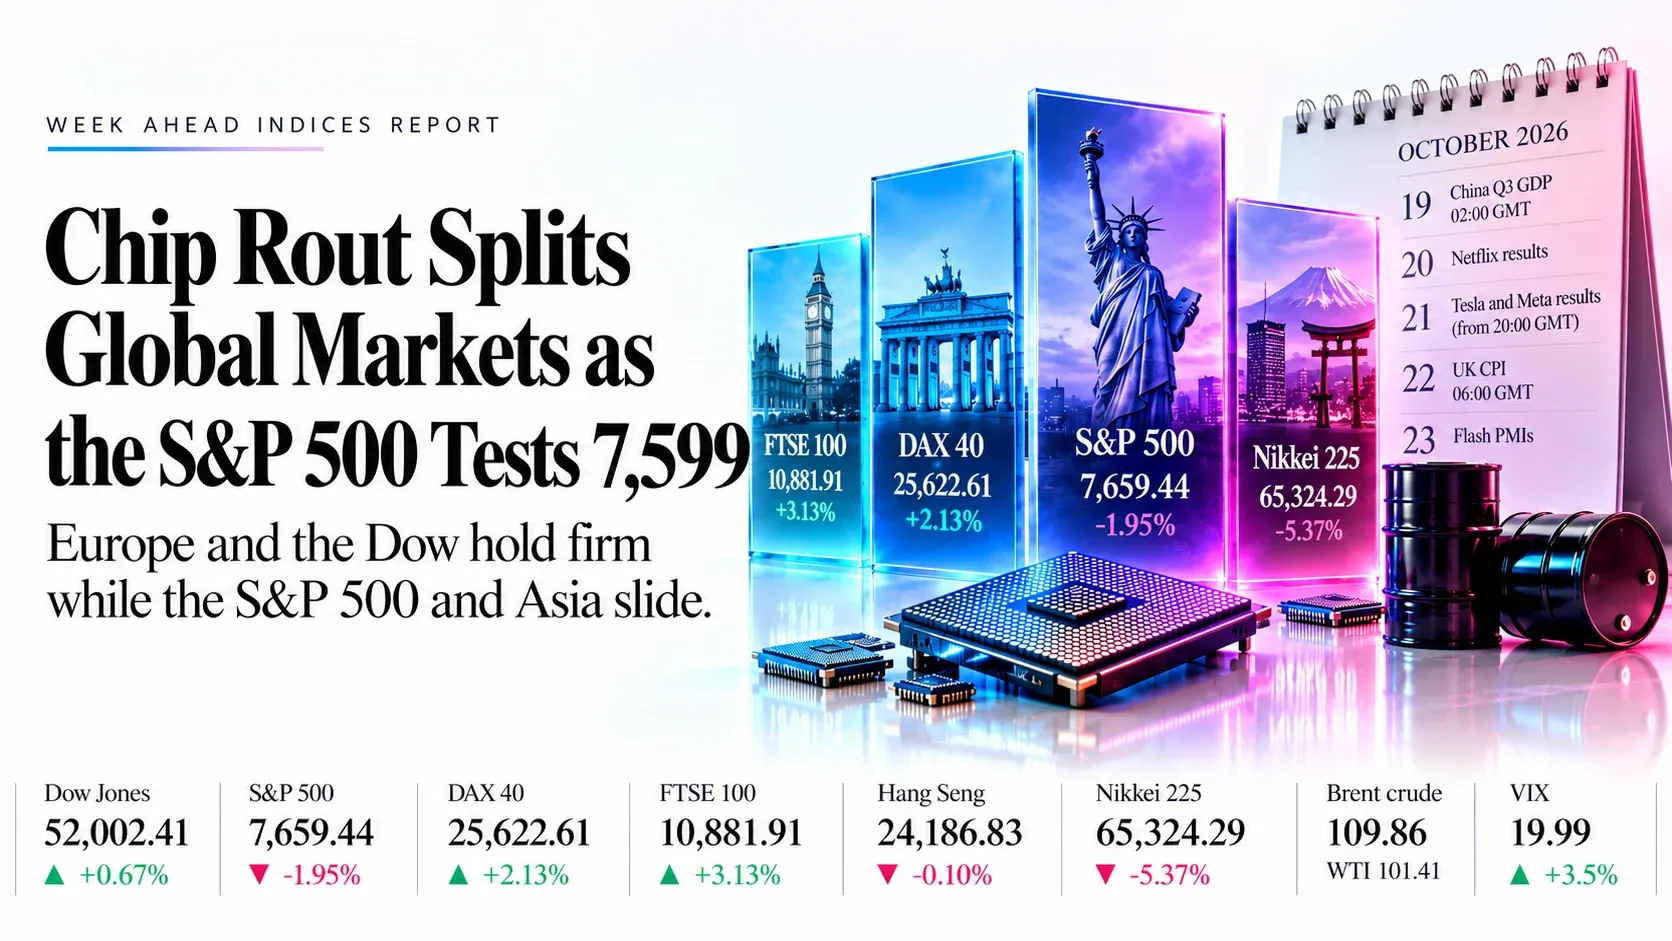
A technology-led split defined last week. The S&P 500 fell 1.95% to 7,659.44 and the Nasdaq lost 4.5%, both their worst weeks since June, as chip stocks fell for an eighth straight session (AP, Trading Economics). The Dow Jones gained 0.67% to 52,002.41 on a rotation into industrials and value. Europe rallied, with the FTSE 100 up 3.13% and the DAX up 2.13% (Investing.com), while the Nikkei 225 dropped 5.37%, its steepest weekly fall since July.
Inflation kept the Federal Reserve on hike watch. US core consumer prices rose 0.3% in September and producer prices jumped 1.3% on the month, lifting the chance of an October hike to around 50% from 20% (Newsquawk). The Fed raised rates to 3.75%–4.00% on 16 September and enters its blackout this weekend ahead of the 27–28 October meeting, so earnings and data will lead. Brent settled at 109.86 on Friday, which keeps energy-driven inflation in focus.
The week ahead opens with China’s Q3 GDP and activity data on Monday at 02:00 GMT, followed by Netflix on Tuesday and Tesla and Meta on Wednesday after the US close. UK CPI on Wednesday at 06:00 GMT and Japan CPI on Thursday at 23:30 GMT precede flash PMIs on Friday. The desk sees Europe’s indices as the strongest charts and the Nikkei and S&P 500 as the most exposed to further chip weakness.
Key highlights
- Wall Street: The Nasdaq Composite fell 2.14% on Friday to 26,140.03 and the S&P 500 lost 1.09%; the Dow slipped 0.34% yet finished the week higher (AP).
- Chips: The iShares Semiconductor ETF fell 4.14% on Friday, with AMD down 5.96%, Intel 5.79% and Micron 5.63%, on Chinese competition fears and debt-funded AI spending (ts2.tech, TradingKey).
- Europe: The STOXX 600 gained 1.4% for its strongest week since August, and the FTSE 100 led the main bourses (Trading Economics, Investinglive).
- Japan: The Nikkei fell 4.90% on Thursday as its semiconductor index dropped 10.14%, then rebounded 1.39% on Friday to 65,324.29 (Vantage, Yahoo Finance).
- Oil: WTI settled at 101.41 and Brent at 109.86 on Friday, with US producer-price energy costs up 10.8% in September (Newsquawk).
- Inflation: US producer prices rose 6.3% on the year against 5.3% expected, the highest since December 2022 (Newsquawk).
Market Snapshot: Friday 16 October 2026 Closes
DJI Dow Jones
52,002.41
+347.46+0.67% week
Range 51,370.14–52,587.26
49,993.0354,600.00
Buy near 51,400SPX S&P 500
7,659.44
-152.10-1.95% week
Range 7,631.77–7,821.67
7,191.278,000.00
Sell near 7,822DAX DAX 40
25,622.61
+535.34+2.13% week
Range 25,133.71–25,693.89
24,704.5326,400.00
Buy near 25,134UKX FTSE 100
10,881.91
+329.87+3.13% week
Range 10,549.64–10,892.38
10,362.3211,000.00
Buy near 10,656HSI Hang Seng
24,186.83
-24.52-0.10% week
Range 23,945.84–24,524.63
22,518.0025,487.76
Sell near 24,684NI225 Nikkei 225
65,324.29
-3,706.41-5.37% week
Range 64,092.74–68,710.99
59,671.1568,710.99
Sell near 66,723- Brent / WTI crude
- 109.86 / 101.41
- Friday settlement; energy drives inflation
- US 10-year Treasury yield
- About 5.1%
- Swung between 5.33% and 5.05% in a day
- Fed funds target range
- 3.75%–4.00%
- Next decision 28 October
- CBOE Volatility Index
- 19.99
- Up 3.5% on Friday
Trade Setups for the Week
| Index | Direction | Entry | Stop | Target 1 | Target 2 | Reward:risk | Conviction |
|---|---|---|---|---|---|---|---|
| Dow Jones | Long | 51,400.00 | 50,550.00 | 52,587.26 | 54,600.00 | 1.4 / 3.8 | Medium |
| S&P 500 | Short | 7,822.00 | 7,950.00 | 7,599.03 | 7,191.27 | 1.7 / 4.9 | Medium |
| DAX 40 | Long | 25,134.00 | 24,650.00 | 25,693.89 | 26,400.00 | 1.2 / 2.6 | Medium |
| FTSE 100 | Long | 10,656.00 | 10,520.00 | 10,892.38 | 11,000.00 | 1.7 / 2.5 | Medium |
| Hang Seng | Short | 24,684.00 | 25,150.00 | 23,945.84 | 22,518.00 | 1.6 / 4.6 | High |
| Nikkei 225 | Short | 66,723.00 | 68,900.00 | 64,092.74 | 59,671.15 | 1.2 / 3.2 | Medium |
Reward:risk is the distance from entry to target 1 and target 2, divided by the distance from entry to the stop. Levels are conditional technical references, not recommendations.
Key Market Drivers
Hot Inflation Keeps the Fed on Hike Watch
US core consumer prices rose 0.3% in September, or 2.6% on the year against 2.5% expected, and the odds of an October hike rose to about 50% from 20% (Newsquawk). Producer prices then jumped 1.3% on the month and 6.3% on the year, the highest annual rate since December 2022. The Fed lifted rates to 3.75%–4.00% on 16 September in a 12-0 vote. Pantheon still sees December as the base case for the next hike, so the data this week matters for the 28 October decision.
Key events: Fed blackout until after 28 October; FOMC Tuesday 27 to Wednesday 28 October; US Q3 GDP Thursday 29 October, 12:30 GMT.
The AI Chip Selloff Is Dragging Technology and Asia
The Nasdaq fell 4.5% on the week and chip stocks have declined for eight sessions, the longest streak since 2008 (Trading Economics). Concerns centre on Chinese chip competition after reports that CXMT made design progress, and on debt-funded AI infrastructure (Reuters, TradingKey). CoreWeave fell nearly 12% on Friday. In Tokyo, the Nikkei semiconductor index lost 10.14% on Thursday, the root of the index’s steepest weekly fall since July.
Key events: Netflix on Tuesday 20 October after the US close; Tesla and Meta on Wednesday 21 October after the US close (from 20:00 GMT).
Oil Above 100 Sustains the Inflation Impulse
WTI settled at 101.41 and Brent at 109.86 on Friday, each about 3.4% and 3.7% higher on the day, amid attacks on Saudi energy infrastructure and doubts over Russia and Ukraine’s energy ceasefire (Newsquawk). Energy added to US producer prices, where goods prices rose 2.6% in September. Energy shares helped the Dow and FTSE 100 against technology, but higher oil raises the odds of tighter policy at the Fed, Bank of England and Bank of Japan.
Key events: EIA crude inventories Wednesday 21 October, 14:30 GMT; Middle East and Russia-Ukraine headlines throughout the week.
Europe and Asia Macro Set the Regional Tone
Chinese Q3 GDP is expected at 4.4% a year on Monday, with September retail sales at 0.7% and investment still falling, so weak data would raise pressure for support (Newsquawk). UK CPI is forecast at 3.4% against 3.1%, with a November Bank of England hike about 77% priced. Japan CPI is forecast near 2.8%–3.0% against 1.9%, ahead of the BoJ. Moody’s reviews France on Friday, and the UK Autumn Budget follows on 28 October.
Key events: China GDP Monday 19 October, 02:00 GMT; UK CPI Wednesday 06:00 GMT; Japan CPI Thursday 22 October, 23:30 GMT; flash PMIs Friday 23 October.
A weekly close below 7,599 on the S&P 500 would hand control to sellers across the US and Asian indices, while a close above 7,821 would signal that the chip selloff has run its course.
Tech and Chip Sentiment Scenario Analysis
No single release decides this week, so the desk frames two paths for chip and AI sentiment, tested by Netflix on Tuesday, Tesla and Meta on Wednesday, and flash PMIs on Friday at 13:45 GMT.
Selloff extends: chips fall for a ninth session
Weak earnings reactions or fresh AI-funding worries would pressure the Nasdaq-heavy S&P 500 and Asian chip exporters first, with hot inflation limiting dip buying.
- Dow Jones51,370.14, then 49,993.03
- S&P 5007,599.03, then 7,191.27
- DAX 4025,133.71, then 24,704.53
- FTSE 10010,655.80, then 10,362.32
- Hang Seng23,945.84, then 22,518.00
- Nikkei 22564,092.74, then 59,671.15
Chips rebound: earnings steady sentiment
Resilient results and softer oil would allow a bounce towards the overhead averages, with Europe’s breakout attempts holding.
- Dow Jones52,587.26, then 54,600.00
- S&P 5007,821.67, then 8,000.00
- DAX 4025,693.89, then 26,400.00
- FTSE 10010,892.38, then 11,000.00
- Hang Seng24,683.94, then 25,487.76
- Nikkei 22566,722.68, then 68,710.99
DJI | Dow Jones Industrial Average
Dow Outlook: Triangle Support Near 51,370 Frames the Breakout Decision
52,002.41 +347.46 (+0.67%) week Range 51,370.14–52,587.26
Outlook: Bias is constructive while the Dow holds above 51,370.14. The blue-chip index gained 0.67% last week while the Nasdaq lost 4.5%, as money rotated into industrials, health care and consumer names. Price is pinned beneath the falling trendline and the 52,333.43 average, so we prefer to buy a pullback to the weekly low rather than chase a break of 52,587.26.
Key levels
- Support 2
- 49,993.03
- Support 1
- 51,370.14
- Resistance 1
- 52,587.26
- Resistance 2
- 54,600.00
Weekly chart structure
- Pattern: a symmetrical triangle between the July high near 54,600 and the March low, with price close to the apex and the lower trendline near 50,800.
- Averages: 52,333.43 sits just above price, with 49,993.03 and 46,814.58 rising beneath.
- Last candle: opened 51,770.18, high 52,587.26, low 51,370.14 and a close near 52,007 on the TradingView chart (52,002.41 on Investing.com), a modest green body.
- Momentum: RSI at 54.16 is below its average at 61.21, a cooling profile since August.
Key technical levels
51,370.14 is last week’s low and the first support; 49,993.03 is the average beneath the triangle base. Above price, 52,587.26 is the weekly high and 54,600 the July peak. A weekly close above 52,587.26 would break the triangle upward, while a close below 49,993.03 would turn the structure bearish.
Fundamental drivers
Defensive rotation
The Dow logged a second straight weekly gain on 16 October even as it fell 0.34% on the day to 52,002.41, outperforming because of its lighter technology weighting (Yahoo Finance, AP).
Rates and oil
Energy stocks rose on Friday as WTI settled at 101.41, which cushioned the Dow while the 10-year yield hovered near 5.1% (Newsquawk, Schwab).
Dow Jones trade setup
LongMedium conviction- Entry
- 51,400.00
- Stop loss
- 50,550.00
- Target 1
- 52,587.26
- Target 2
- 54,600.00
Risk 850.00. Reward:risk 1.4 to target 1, 3.8 to target 2.
Rationale: Triangle support and the defensive-rotation bid favour buyers on a dip to the weekly low; the falling trendline above keeps conviction at medium.
Invalidation: A daily close below 50,550. The main risk is an AI-led selloff that spreads beyond technology, or a hawkish Fed repricing.
SPX | S&P 500 Index
S&P 500 Outlook: Chip Rout Pushes Price to the 7,599 Channel Base
7,659.44 -152.10 (-1.95%) week Range 7,631.77–7,821.67
Outlook: Bias is cautious while the S&P 500 trades below 7,821.67. Last week’s 1.95% fall was the index’s worst since June, and price now sits on the lower edge of the rising channel and the 7,599.03 average. We prefer to sell a bounce towards last week’s high, with a weekly close below 7,599.03 the trigger for the channel to fail.
Key levels
- Support 2
- 7,191.27
- Support 1
- 7,599.03
- Resistance 1
- 7,821.67
- Resistance 2
- 8,000.00
Weekly chart structure
- Pattern: a rising channel from the March low, with price at its lower boundary and the upper boundary far above near 8,450.
- Averages: 7,599.03 directly beneath price, then 7,191.27 and 6,638.32 further down.
- Last candle: opened 7,813.04, high 7,821.67, low 7,631.77 and a close at 7,659.44, a long red body.
- Momentum: RSI at 57.45 has turned down from its average at 62.77.
Key technical levels
7,631.77 is last week’s low and 7,599.03 the average and channel base beneath it. 7,191.27 is the next average. Above price, 7,821.67 is the weekly high and 8,000 the round-number barrier. A weekly close below 7,599.03 would break the channel and expose 7,191.27; a close above 7,821.67 would restore the uptrend.
Fundamental drivers
Chip selloff
Semiconductor shares fell for an eighth straight session on 16 October, the longest losing streak since 2008, with the Nasdaq down 2.14% on the day (Trading Economics, AP).
Breadth and volatility
The VIX closed at 19.99, up 3.5% on Friday, and 272 S&P 500 members fell against 228 advancing (Trading Economics, ts2.tech).
S&P 500 trade setup
ShortMedium conviction- Entry
- 7,822.00
- Stop loss
- 7,950.00
- Target 1
- 7,599.03
- Target 2
- 7,191.27
Risk 128.00. Reward:risk 1.7 to target 1, 4.9 to target 2.
Rationale: A large red candle at the channel base and weakening momentum favour selling the bounce; the intact channel keeps conviction at medium.
Invalidation: A daily close above 7,950. The main risk is a sharp chip rebound after Tuesday and Wednesday earnings.
DAX | DAX 40 Index
DAX Outlook: Reclaiming the 25,459 Average Keeps the Channel Rebound Alive
25,622.61 +535.34 (+2.13%) week Range 25,133.71–25,693.89
Outlook: Bias is constructive while the DAX holds above 24,704.53. A 2.13% weekly gain lifted price back above the 25,459.60 average and inside the middle of the rising channel. We prefer to buy a retest of last week’s low near 25,134 rather than pay up beneath resistance at 25,693.89.
Key levels
- Support 2
- 24,704.53
- Support 1
- 25,133.71
- Resistance 1
- 25,693.89
- Resistance 2
- 26,400.00
Weekly chart structure
- Pattern: a rising channel from the March low near 21,800, with price in the upper half after a pullback from the August high.
- Averages: 25,459.60 now beneath price, with 24,704.53 and 23,692.11 rising below.
- Last candle: opened 25,206.95, high 25,693.89, low 25,133.71 and a close at 25,622.61 near the high of its range.
- Momentum: RSI at 54.07 is turning up but remains just below its average at 56.11.
Key technical levels
25,459.60 is the average that price has reclaimed and 25,133.71 last week’s low. 24,704.53 is the next average. Above price, 25,693.89 is the weekly high and about 26,400 the August peak. A weekly close above 25,693.89 would target 26,400, while a close below 24,704.53 would put the channel base at risk.
Fundamental drivers
European relief
The DAX rose 0.95% on Friday to 25,622.61 as all major sectors gained and the STOXX 600 posted its strongest week since August (Trading Economics, Investing.com).
Inflation watch
Eurozone flash PMIs on Friday will show whether input prices are re-accelerating, with the September survey pointing to inflation near 4% (Newsquawk).
DAX 40 trade setup
LongMedium conviction- Entry
- 25,134.00
- Stop loss
- 24,650.00
- Target 1
- 25,693.89
- Target 2
- 26,400.00
Risk 484.00. Reward:risk 1.2 to target 1, 2.6 to target 2.
Rationale: Channel structure and a reclaimed average favour buyers on a retest of the weekly low; ZEW and flash PMI risk keep conviction at medium.
Invalidation: A daily close below 24,650. The main risk is a global chip selloff that drags exporters and technology lower.
UKX | FTSE 100 Index
FTSE 100 Outlook: Weekly Breakout Attempt Targets the 11,000 Record Zone
10,881.91 +329.87 (+3.13%) week Range 10,549.64–10,892.38
Outlook: Bias is bullish while the FTSE 100 holds above 10,362.32. The 3.13% weekly gain led Europe and pushed price to the top of a narrowing triangle, with the weekly close just under last week’s high. We prefer to buy a retest of the 10,655.80 average, because a first weekly close above the falling trendline invites a run at 11,000.
Key levels
- Support 2
- 10,362.32
- Support 1
- 10,655.80
- Resistance 1
- 10,892.38
- Resistance 2
- 11,000.00
Weekly chart structure
- Pattern: a narrowing triangle between the falling line from the July high near 11,000 and the rising line from the March low.
- Averages: 10,655.80 and 10,362.32 beneath price, with 9,567.98 far below.
- Last candle: opened 10,551.55, high 10,892.38, low 10,549.64 and a close at 10,881.91, a full-bodied green candle.
- Momentum: RSI at 59.59 has crossed above its average at 57.80.
Key technical levels
10,655.80 is the average that now acts as first support and 10,549.64 last week’s low. 10,362.32 is the next average. Above price, 10,892.38 is the weekly high and about 11,000 the July and February peak zone. A weekly close above 10,892.38 would confirm the breakout; a close below 10,362.32 would negate it.
Fundamental drivers
Inflation and the BoE
UK CPI is due on Wednesday at 06:00 GMT with a consensus of 3.4% against 3.1%, and markets price roughly a 77% chance of a November rate rise (Newsquawk).
Budget risk
The Autumn Budget on 28 October adds fiscal uncertainty for domestic stocks, while the FTSE 100 closed Friday at 10,881.91, up 0.38% (Investing.com, Bloomberg).
FTSE 100 trade setup
LongMedium conviction- Entry
- 10,656.00
- Stop loss
- 10,520.00
- Target 1
- 10,892.38
- Target 2
- 11,000.00
Risk 136.00. Reward:risk 1.7 to target 1, 2.5 to target 2.
Rationale: The breakout attempt and rising averages favour buyers on a retest of 10,655.80; hot UK CPI would test the idea, so conviction stays at medium.
Invalidation: A daily close below 10,520. The main risk is a hotter CPI print that lifts BoE hike pricing and weighs on banks and domestic stocks.
HSI | Hang Seng Index
Hang Seng Outlook: Falling Channel and Lost Averages Favour Selling 24,684
24,186.83 -24.52 (-0.10%) week Range 23,945.84–24,524.63
Outlook: Bias is bearish while the Hang Seng trades below 25,487.76. The index closed 0.10% lower on the week, just beneath the 24,336.67 average, after a 0.52% Friday bounce failed to reclaim it. We prefer to sell a rally to the 24,683.94 average, with Monday’s China data the first test.
Key levels
- Support 2
- 22,518.00
- Support 1
- 23,945.84
- Resistance 1
- 24,683.94
- Resistance 2
- 25,487.76
Weekly chart structure
- Pattern: a falling channel from the January high near 28,000, with the upper boundary near 25,600 and the lower near 21,300.
- Averages: 24,336.67, 24,683.94 and 25,487.76 all sit overhead.
- Last candle: opened 24,434.93, high 24,524.63, low 23,945.84 and a close at 24,186.83, a small red body.
- Momentum: RSI at 43.05 is below 50 and below its average at 48.61.
Key technical levels
23,945.84 is last week’s low and the first support; 22,518 is the June low and 52-week low. Above price, 24,683.94 is the average that should cap rallies and 25,487.76 the channel-top average. A weekly close below 23,945.84 would target 22,518, while a close above 25,487.76 would end the bearish structure.
Fundamental drivers
China data
Chinese Q3 GDP is due on Monday at 02:00 GMT with a consensus of 4.4% a year, alongside retail sales of 0.7% and weak fixed-asset investment (Newsquawk).
Mainland weakness
To 15 October, the Shanghai Composite fell 2.79%, the Shenzhen Component 6.53% and the ChiNext 8.55% on the week (Lundgreen’s Investor Insights).
Hang Seng trade setup
ShortHigh conviction- Entry
- 24,684.00
- Stop loss
- 25,150.00
- Target 1
- 23,945.84
- Target 2
- 22,518.00
Risk 466.00. Reward:risk 1.6 to target 1, 4.6 to target 2.
Rationale: A falling channel, lost averages and sub-50 momentum favour sellers into 24,684; strong export data keeps conviction from being absolute.
Invalidation: A daily close above 25,150. The main risk is a stimulus signal or a strong China data beat that triggers short covering.
NI225 | Nikkei 225 Index
Nikkei 225 Outlook: Failed Triangle Breakout Leaves 64,093 Support Exposed
65,324.29 -3,706.41 (-5.37%) week Range 64,092.74–68,710.99
Outlook: Bias is bearish while the Nikkei trades below 66,722.68. The index fell 5.37% last week, its steepest since July, after a 4.90% drop on Thursday and a 1.39% Friday bounce. Price sits on the rising trendline just above 64,000, and we prefer to sell a rally to the 66,722.68 average.
Key levels
- Support 2
- 59,671.15
- Support 1
- 64,092.74
- Resistance 1
- 66,722.68
- Resistance 2
- 68,710.99
Weekly chart structure
- Pattern: a symmetrical triangle between the June high near 72,500 and the March low; the break higher failed and price is back at the rising trendline.
- Averages: 66,722.68 overhead, with 59,671.15 and 49,897.24 rising beneath.
- Last candle: opened 68,564.85, high 68,710.99, low 64,092.74 and a close at 65,324.29 after a Friday bounce.
- Momentum: RSI at 52.74 has crossed below its average at 58.06.
Key technical levels
64,093 is last week’s low and the triangle support; 59,671.15 is the next average. Above price, 66,722.68 is the average and 68,710.99 last week’s high. A weekly close below 64,092.74 would open 59,671.15, while a close above 68,710.99 would revive the breakout.
Fundamental drivers
Chip rout
The Nikkei fell 4.90% on 15 October as its semiconductor index dropped 10.14%, and the volatility index jumped to 36.13 (Vantage, Nikkei Inc.).
Inflation and the BoJ
Japan CPI is due on Thursday at 23:30 GMT, with headline forecast at 2.8%–3.0% against 1.9%, the last major print before the October BoJ meeting (Newsquawk).
Nikkei 225 trade setup
ShortMedium conviction- Entry
- 66,723.00
- Stop loss
- 68,900.00
- Target 1
- 64,092.74
- Target 2
- 59,671.15
Risk 2,177.00. Reward:risk 1.2 to target 1, 3.2 to target 2.
Rationale: A failed breakout, a bearish momentum cross and the chip rout favour selling into the 66,723 average; the rising trendline keeps conviction at medium.
Invalidation: A daily close above 68,900. The main risk is a sharp chip rebound or a softer Japan CPI that eases BoJ hike pricing.
Economic Calendar: 19–23 October 2026
| Date | Event | Market | Impact | Context |
|---|---|---|---|---|
| 02:00 GMT | China Q3 GDP, September retail sales and industrial production; GDP consensus 4.4% y/y, prior 4.3% | Hang Seng, Nikkei, DAX | High | Sets the Asian risk tone at the weekly open; Hang Seng 24,684 resistance |
| 12:30 GMT | Canada CPI, September | Risk sentiment | Low | Global inflation read-across |
| 14:00 GMT | US NAHB housing market index, October | Dow, S&P 500 | Low | Rate-sensitive housing demand |
| 01:15 GMT | China loan prime rates, October; consensus 1yr 3.00%, 5yr 3.50% | Hang Seng, Nikkei | Medium | Policy read-through of Monday’s GDP data |
| 06:00 GMT | UK labour market report | FTSE 100 | Medium | Hiring signs ahead of the 28 October budget |
| 09:00 GMT | Germany and eurozone ZEW economic sentiment, October | DAX | Medium | Investor mood after the chip selloff |
| 12:30 GMT | US housing starts and building permits, September | Dow, S&P 500 | Low | Growth gauge for rate-sensitive sectors |
| From 20:00 GMT | Netflix quarterly results (after the US close) | S&P 500, Nasdaq | Medium | Technology tone; S&P 500 7,599 support |
| 23:50 GMT | Japan trade balance, September | Nikkei | Low | Export demand into the BoJ meeting |
| 06:00 GMT | UK CPI, September; consensus 3.4% y/y, prior 3.1% | FTSE 100, gilts | High | BoE November hike pricing; FTSE 10,656 in play |
| 14:30 GMT | EIA crude oil inventories, week ending 16 October | Oil, all indices | Medium | Energy costs behind the inflation surprise |
| 17:00 GMT | US 20-year Treasury auction (expected) | Dow, S&P 500 | Medium | Demand at 5% yields; Dow 51,370 |
| From 20:00 GMT | Tesla and Meta results (expected after the US close) | S&P 500, Nikkei | High | Decides whether the chip rout extends; S&P 500 7,599 |
| 01:00 GMT | Bank of Korea policy decision, October; expected hold at 3.00% | Nikkei, Hang Seng | Low | Asian chip-exporter sentiment |
| 12:30 GMT | US initial jobless claims, week ending 17 October | Dow, S&P 500 | Medium | Labour data before the Fed decision |
| 23:30 GMT | Japan CPI, September; headline forecast 2.8%–3.0% y/y, prior 1.9% | Nikkei | High | BoJ hike pricing; Nikkei 66,723 resistance |
| 06:00 GMT | UK retail sales, September | FTSE 100 | Low | Consumer strain before the budget |
| 08:00 GMT | Eurozone and Germany flash PMIs, October | DAX | High | Input-price components; DAX 25,134 support |
| 08:30 GMT | UK flash PMI, October | FTSE 100 | Medium | Activity and price pressures |
| 13:45 GMT | S&P Global flash US manufacturing and services PMIs, October | Dow, S&P 500 | High | Price components feed Fed pricing; Dow 52,587 |
| 14:00 GMT | University of Michigan final sentiment and inflation expectations, October | Dow, S&P 500 | Medium | Expectations shape the Fed tone |
| Evening GMT | Moody’s credit review on France (scheduled) | DAX | Medium | Negative outlook; OAT-Bund spread near 151bp |
Conclusion
The theme is a technology-led divergence under a hawkish backdrop. With the Fed silent, Tuesday and Wednesday earnings, UK and Japan inflation, and Friday’s PMIs decide whether the chip rout spreads. A weekly close below 7,599 on the S&P 500 would challenge the view that the March channel is intact.
The FTSE 100 and DAX carry the strongest charts and the Dow is the steadiest of the US benchmarks. The Nikkei, Hang Seng and S&P 500 are the weakest, which is why they carry the three short ideas.
The desk approach is to work from the stated zones, treat every level as conditional, size positions so that a stop is a manageable event, and reduce exposure ahead of China’s data at 02:00 GMT on Monday and Wednesday’s earnings.
| Index | Bias | Key level | Targets | Invalidation | Principal risk |
|---|---|---|---|---|---|
| Dow Jones | Buy near 51,400 | 51,400.00 | 52,587.26 / 54,600.00 | Below 50,550.00 | Hot inflation, Fed hike risk |
| S&P 500 | Sell near 7,822 | 7,821.67 | 7,599.03 / 7,191.27 | Above 7,950.00 | Chip rebound, earnings beats |
| DAX 40 | Buy near 25,134 | 25,134.00 | 25,693.89 / 26,400.00 | Below 24,650.00 | Tech contagion, PMI prices |
| FTSE 100 | Buy near 10,656 | 10,656.00 | 10,892.38 / 11,000.00 | Below 10,520.00 | UK CPI, BoE hike pricing |
| Hang Seng | Sell near 24,684 | 24,684.00 | 23,945.84 / 22,518.00 | Above 25,150.00 | China stimulus, data beat |
| Nikkei 225 | Sell near 66,723 | 66,723.00 | 64,092.74 / 59,671.15 | Above 68,900.00 | Chip rebound, soft Japan CPI |
Trade the Dow, S&P 500, DAX, FTSE 100, Hang Seng and Nikkei with Capital Street FX.
Frequently Asked Questions
What could move stock indices between 19 and 23 October?
China’s Q3 GDP on Monday, UK CPI on Wednesday, Japan CPI on Thursday and the flash PMIs on Friday are the main data points. Netflix, Tesla and Meta results shape technology sentiment while the Fed is silent.
Why is the Dow outperforming the S&P 500 and Nasdaq?
The Dow has less technology weighting and more industrials, health care and energy. Last week’s chip selloff hit the Nasdaq-heavy S&P 500 harder, while the Dow gained 0.67%.
Why did the Nikkei 225 fall so much last week?
The Nikkei fell 5.37% as its semiconductor index dropped 10.14% on Thursday, in line with the global chip selloff. Its weekly decline was the steepest since July, and volatility spiked.
How do Fed rate expectations affect stock indices?
Higher expected rates lift Treasury yields and discount rates on future profits, which pressures growth-heavy indices more. Hot inflation data therefore tends to weigh on the S&P 500, while value-heavy indices hold up better.
When is the next Federal Reserve decision?
The Federal Open Market Committee meets on 27–28 October, a week after the period covered here. Policymakers entered their blackout on Saturday 17 October, so no scheduled speeches are due before the decision.