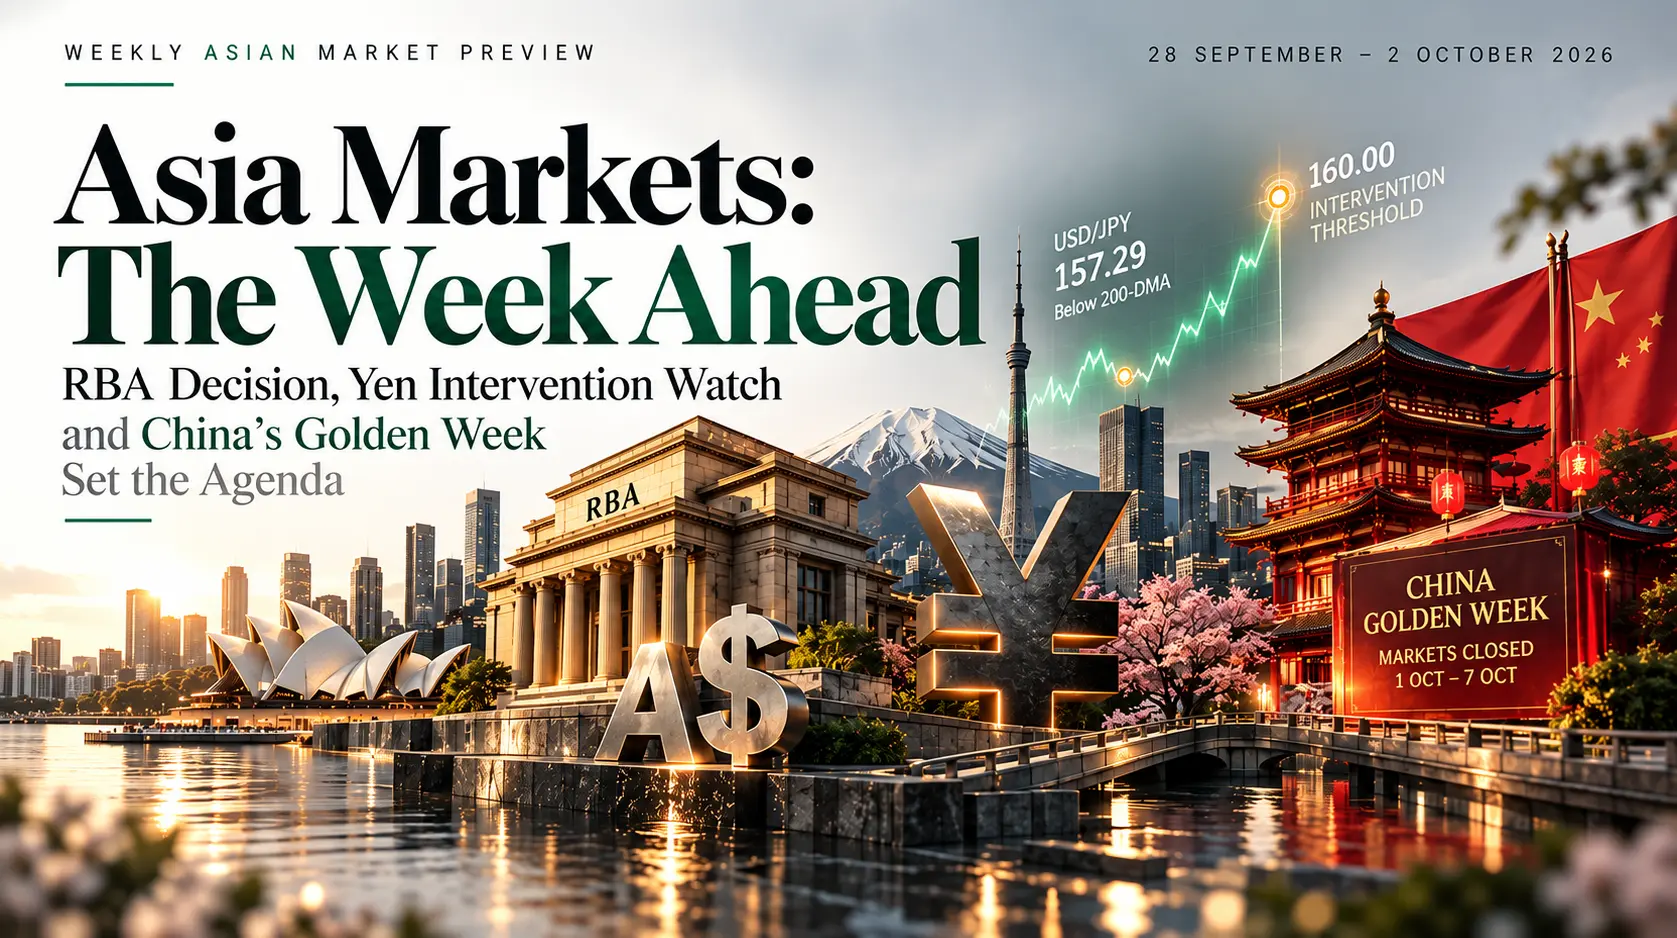
Weekly Asian Market Outlook: RBA Decision, Yen Intervention Watch and China’s Golden Week Headline.
Weekly Asian Market Outlook: RBA Decision, Yen Intervention Watch and China’s Golden Week Headline the Week Ahead
USD/JPY · AUD/USD · Copper · Corn · Nikkei 225 · Dogecoin · Litecoin — weekly news, upcoming events and key drivers, 28 September – 2 October 2026
What Happened Last Week
A quick look back before the week ahead
Last week was dominated by a firming Dollar and a global bond sell-off that pushed US 10-year yields toward their highest since 2007, weighing on Asian risk assets and pulling AUD/USD to a four-month low near 0.7024. USD/JPY pushed as high as 158.37 on renewed intervention chatter before fading back below its 200-day average into the weekend. The Hang Seng slipped for a second straight session as yields spiked, while the Nikkei 225 bucked the trend, climbing on Yen weakness and strength in large-cap tech names. Copper notched a fresh record above $6.90 as Chile’s Escondida suspension and a looming Centinela strike vote kept supply fears elevated, and Wheat pressed toward three-year highs on tight global stocks. In crypto, Litecoin surged over 20% on its golden cross and Grayscale’s spot-ETF conversion news, while Dogecoin climbed on reported whale accumulation heading toward the $0.10 level.
Nine Stories Setting Up the Week Ahead
Ranked by expected impact on Asian trading through 2 October
RBA rate decision on Tuesday is the week’s key event risk
All big-four Australian banks now expect a 25bp hike to 4.60% on 29 September. The statement’s guidance on further tightening will matter as much as the decision itself.
RBA Decision TuesdayYen intervention watch carries into the new week
USD/JPY enters the week near 157.29 after touching a high of 158.37 on Friday before slipping back below its 200-day average. Tokyo has spent roughly ¥15.4 trillion defending the currency since late July, keeping 160.00 the line to watch.
Intervention WatchA data-heavy US week culminates in Friday’s payrolls report
ISM Manufacturing (Wed/Thu Asia time), ADP employment and Friday’s Non-Farm Payrolls will shape October Fed hike odds, currently near 70-72%, and set the tone for Asian FX and rates.
US Jobs WeekAussie carries a fresh four-month low into the RBA meeting
AUD/USD sits below its 200-day moving average heading into Tuesday. A hike that is already close to fully priced raises the risk of a “sell the fact” reaction unless guidance surprises hawkish.
RBA WeekNikkei carries Yen-driven momentum into Tankan week
Japan’s quarterly Tankan survey lands Thursday alongside quarter-end and Q4-start portfolio flows, a key test of whether large-cap and tech names can keep outperforming.
Tankan ThursdayChina’s Golden Week closure looms over copper positioning
Mainland Chinese markets shut for National Day holidays from 1 October, so pre-holiday demand, Wednesday’s final PMIs and the Centinela strike vote outcome are all in focus before the lull.
Golden Week AheadCorn stays capped as harvest supply meets a quieter China
Fresh US harvest bushels and the start of Brazil’s planting season continue to weigh, with Chinese buying likely to slow further as the Golden Week holiday approaches.
Harvest PressureLitecoin’s golden-cross rally faces a follow-through test
The 50/200-day golden cross and Grayscale’s move to convert its Litecoin Trust into a spot ETF drove Friday’s surge; whether buyers defend the move through the week is now the key question.
ETF Process WatchDogecoin’s whale accumulation carries toward $0.10
A widely followed tracker flagged large holders buying over 600 million DOGE in 24 hours. Whether that flow continues into the week will determine if the $0.10 resistance zone comes into range.
Whale Buying| Market | Friday Close | Weekly Bias Note | What To Watch This Week |
|---|---|---|---|
| Dollar Index (DXY) | ~101.2 | Two-month high | ISM, ADP and Friday’s NFP into elevated Fed hike odds |
| US 10-Year Yield | 5.11% | Near 2007 high | US jobs data flow; October Fed hike odds near 70-72% |
| USD/JPY | 157.29 | Below 200-day SMA | 160.00 line; any verbal or actual BOJ action |
| AUD/USD | 0.7024 | 4-month low | Tuesday’s RBA decision and guidance |
| Nikkei 225 | 66,345 | Outperforming peers | Thursday’s Tankan survey; quarter-end flows |
| Copper (COMEX) | $6.811/lb | On track for weekly gain | China PMIs, Centinela strike vote, Golden Week closure |
| Corn (CBOT front-month) | 520.75 | Harvest pressure | China demand pace ahead of its holiday |
| Dogecoin (DOGE/USD) | $0.0956 | Whale accumulation | Follow-through toward the $0.10 resistance zone |
| Litecoin (LTC/USD) | $73.00 | Golden cross | Whether the rally holds; ETF-process headlines |
Levels reflect Friday 25 September 2026 close and are indicative; futures, crypto and index figures carry a ~ where taken from other trackers.
Technical Levels for Seven Instruments
Each analysis is conditional and lists a bias, resistance and support levels for the week of 28 September – 2 October. Levels are technical references, not forecasts.
USD/JPY
Weekly Setup
USD/JPY opens the week near 157.29, having slipped from Friday’s high near 158.37 to an intraweek low around 156.90, taking some heat off the BOJ intervention watch that had built up near the 160.00 line after Tokyo already spent roughly ¥15.4 trillion defending the Yen since late July.
Technical Structure & Confirmation
Price now sits below the 200-day SMA at 158.43, which caps the immediate upside. A weekly close back above that average would reopen 159.00 and then the psychological 160.00 intervention line, while US yields near 5.11% and October Fed hike odds near 70-72% keep the broader Dollar bid.
Alternative Scenario
A hot Friday payrolls print or fresh verbal BOJ restraint could send the pair back above 158.43 toward 159.00-160.00, while continued softness or a break of 156.80 opens a deeper slide toward 156.20-155.80.

| Resistance | Support |
|---|---|
| R1 158.43 | S1 156.80 |
| R2 159.00 | S2 156.20 |
| R3 160.00 | S3 155.80 |
AUD/USD
Weekly Setup
AUD/USD opens the week at 0.7024, its lowest since early August, with all big-four Australian banks expecting a 25bp hike to 4.60% on Tuesday and markets pricing roughly 92% odds.
Technical Structure & Confirmation
The pair trades below its 200-day moving average as a broadly firm Dollar and elevated US yields cap rallies. A hike that is already fully priced could still fail to lift AUD, while any RBA disappointment risks a slide toward 0.6980-0.6940 ahead of Wednesday’s CPI.
Alternative Scenario
A dovish surprise or soft Tuesday retail sales could send the pair toward 0.6900, while a hawkish RBA surprise paired with softer US data could lift it back to 0.7040-0.7090.

| Resistance | Support |
|---|---|
| R1 0.7040 | S1 0.6980 |
| R2 0.7090 | S2 0.6940 |
| R3 0.7140 | S3 0.6900 |
Copper (COMEX)
Weekly Setup
Copper trades near $6.811 per pound, a fresh high after clearing its prior $6.926 record set two weeks ago, and up about 9% this quarter, as Chile’s Escondida mine remains suspended and a Centinela strike vote looms.
Technical Structure & Confirmation
Chinese buyers are front-loading purchases ahead of the Golden Week holiday (1-8 October), which should thin mainland liquidity into the back half of the week. Wednesday and Thursday’s China PMIs are the key swing data before the holiday closes the loop on demand signals.
Alternative Scenario
A resolved Centinela strike vote or a softer China PMI print could ease the supply-risk premium and send copper back toward $6.657, while continued disruption keeps a push toward $6.983 in play.

| Resistance | Support |
|---|---|
| R1 6.889 | S1 6.750 |
| R2 6.926 | S2 6.657 |
| R3 6.983 | S3 6.588 |
Wheat (CBOT Front-Month)
Weekly Setup
Wheat trades near 765.75, up over 30% since June and recently touching three-year highs, as tight global supply and adverse weather risk keep the complex firm into the new week.
Technical Structure & Confirmation
Price is testing resistance near the Fibonacci extension around 792.00 that has capped recent rallies. Thursday’s Caixin PMI and China’s Golden Week closure could slow near-term Chinese buying interest even as the broader uptrend stays intact above 750.00.
Alternative Scenario
A pickup in US export sales pace (currently around 33% of the season estimate versus a 39% average) or fresh Black Sea supply disruption could extend the rally toward 800.00, while a stronger Dollar or favourable harvest weather could pull price back to 745.00-733.00.

| Resistance | Support |
|---|---|
| R1 780.00 | S1 750.00 |
| R2 792.00 | S2 733.00 |
| R3 800.00 | S3 715.00 |
Hang Seng Index
Weekly Setup
The Hang Seng enters the week near 24,510, extending a second straight losing session as a global bond sell-off, a firmer Dollar and rebounding oil prices weigh on sentiment, with tech and financial names among the laggards.
Technical Structure & Confirmation
The index trades below both its recent highs near 24,834 and last week’s 25,050-25,070 range, with US 10-year yields near their highest since 2007 keeping pressure on regional risk assets. Wednesday and Thursday’s China PMIs are the last major data points before mainland markets close for Golden Week (1-8 October), which typically thins Southbound Stock Connect flows.
Alternative Scenario
A stronger-than-expected China PMI or constructive signals around this week’s Trump-Xi meeting could lift the index back above 24,850 toward 25,050-25,300, while a further yield spike or a weak PMI print could extend losses toward 23,900-23,600.

| Resistance | Support |
|---|---|
| R1 24,750 | S1 24,350 |
| R2 24,950 | S2 24,050 |
| R3 25,150 | S3 23,750 |
Dogecoin (DOGE/USD)
Weekly Setup
Dogecoin trades near $0.0956, supported by fresh large-holder accumulation, with Bitcoin holding near $84,000 providing a steadier backdrop for altcoins this week.
Technical Structure & Confirmation
A close above 0.0971 opens the round-number 0.1000 level and then the 7-day high near 0.1054. Elevated Fed hike odds and this week’s US jobs data remain the main headwind for broader risk appetite.
Alternative Scenario
A hotter-than-expected Friday payrolls print that lifts Fed hike odds further could trigger renewed de-risking across crypto, pulling Dogecoin back toward 0.0890-0.0822.

| Resistance | Support |
|---|---|
| R1 0.0971 | S1 0.0920 |
| R2 0.1000 | S2 0.0890 |
| R3 0.1054 | S3 0.0822 |
Solana (SOL/USD)
Weekly Setup
Solana trades near $120.50, up sharply on the day and roughly 7% higher over the past week, as Bitwise’s BSOL staking ETF tops $1 billion in assets and Fidelity’s FSOL continues to draw inflows.
Technical Structure & Confirmation
Price holds above the 112.00 support built over recent weeks, with the upcoming Alpenglow upgrade targeting 150ms transaction finality adding a fundamental tailwind alongside growing real-world-asset activity on the network.
Alternative Scenario
A broader risk-off move tied to elevated Fed hike odds, or a slowdown in ETF inflow momentum, could pull Solana back toward 108.00-97.00.

| Resistance | Support |
|---|---|
| R1 128.00 | S1 112.00 |
| R2 135.00 | S2 105.00 |
| R3 145.00 | S3 97.00 |
Key Events, 28 September – 2 October
Scheduled data and events most likely to move Asian markets this week (times approximate, GMT)
| Day | Time (GMT) | Event | Impact |
|---|---|---|---|
| Mon 28 Sep | All day | Kospi reopens after Chuseok holiday; quiet positioning ahead of the RBA and China PMIs | Medium |
| Mon 28 Sep | 05:00 | Japan · Retail Sales (August) | Medium |
| Tue 29 Sep | 00:30 | Australia · Retail Sales (August) | High |
| Tue 29 Sep | 04:30 | RBA Interest Rate Decision & Statement | Critical |
| Tue 29 Sep | 06:30 | RBA Governor press conference | Critical |
| Wed 30 Sep | 01:00 | China · NBS Manufacturing & Non-Manufacturing PMI (September) — final release before Golden Week | Critical |
| Wed 30 Sep | 01:30 | Australia · Monthly CPI Indicator (August) | High |
| Wed 30 Sep | 23:50 | Japan · Industrial Production (preliminary, August) | Medium |
| Thu 1 Oct | 00:50 | Japan · Tankan Large Manufacturers & Non-Manufacturers Index (Q3) | Critical |
| Thu 1 Oct | 01:45 | China · Caixin Manufacturing PMI (September) | High |
| Thu 1 Oct | All day | Mainland China markets closed for National Day “Golden Week” (through 8 October) | High |
| Thu 1 Oct | 14:00 | US · ISM Manufacturing PMI (September) | High |
| Fri 2 Oct | 12:30 | US · Non-Farm Payrolls, Unemployment Rate & Average Hourly Earnings (September) | Critical |
| Fri 2 Oct | Throughout | Fed speakers react to the jobs report; quarter/month-end flow settles into the weekly close | Medium |
China’s National Day Golden Week runs 1–8 October, thinning mainland liquidity across metals and agriculture for the back half of the week and beyond.
What Will Drive Asia This Week
Macro, policy and event risk shaping the week ahead
RBA Decision Is the Week’s Fulcrum
DriverTuesday’s rate decision is close to fully priced at a 25bp hike to 4.60%, so the statement’s guidance on further tightening carries more weight than the move itself.
ContextHawkish RBA commentary and a jump in oil prices have lifted inflation risk since the July CPI print; Wednesday’s monthly CPI indicator lands just after the decision.
WatchAny RBA guidance on the pace of further hikes, and whether AUD/USD can reclaim 0.7040-0.7090 on a “buy the rumour, sell the fact” unwind.
Yen Intervention Line Stays in Play
DriverUSD/JPY carries into the week near 157.29, having pulled back below its 200-day average after touching 158.37, easing some pressure on the 160.00 level where Japan’s Ministry of Finance has intervened before.
ContextTokyo has spent roughly ¥15.4 trillion defending the Yen since late July, and October Fed hike odds near 70-72% keep the pair broadly supported.
WatchAny verbal or actual BOJ intervention, and whether US jobs data this week pushes the pair to test 160.00.
China’s Golden Week Reshapes Flows
DriverMainland Chinese markets close from 1 October for National Day holidays through 8 October, so Wednesday’s PMIs are the last mainland data point for over a week.
ContextCopper buyers are likely to position ahead of the closure, while the Escondida suspension and a pending Centinela strike vote keep supply-side risk elevated.
WatchWednesday’s NBS PMIs and Thursday’s Caixin PMI for a read on demand heading into the holiday lull.
Tankan Survey Tests the Nikkei’s Rally
DriverJapan’s quarterly Tankan survey, due Thursday, is the first major gauge of corporate sentiment since the recent Yen weakness and global bond-yield shock.
ContextA weaker Yen and firm large-cap tech and semiconductor names have helped the Nikkei 225 outperform regional peers into the week.
WatchWhether Tankan confidence readings and quarter-end flows extend the rally toward 66,500-67,000 or trigger profit-taking.
A Data-Heavy US Week Sets the Dollar’s Path
DriverADP employment, ISM Manufacturing and Friday’s Non-Farm Payrolls form a full read on the US labour market ahead of the next Fed decision.
ContextOctober Fed hike odds sit near 70-72% per CME FedWatch, with the 10-year Treasury yield holding near 5.11%, close to a 19-year high.
WatchFriday’s payrolls print for the clearest signal yet on whether hike odds firm further into October.
Crypto Momentum Faces a Follow-Through Test
DriverLitecoin’s golden cross and Grayscale’s spot-ETF filing, alongside Dogecoin’s whale accumulation, carry fresh altcoin momentum into the week.
ContextBitcoin holds near $84,000, providing a steadier backdrop even as elevated Fed hike odds remain a headwind for risk assets broadly.
WatchWhether DOGE can clear $0.10 and LTC can hold above $75 as the week’s macro data flow lands.
Conditional Outlook For The Week
Event-driven scenarios built from the week’s calendar. No unconditional forecasts are made.
USD/JPY & AUD/USD
If the RBA hikes with hawkish guidance, US jobs data stays firm and USD/JPY reclaims its 200-day average, it should press toward 159.00-160.00 and AUD/USD should hold a “sell the fact” move toward 0.6980-0.6940.
If the RBA hikes but signals a pause, or US data disappoints, USD/JPY should extend its slide toward 156.20-155.80 and AUD/USD could reclaim 0.7040-0.7090.
Copper & Corn
If China’s PMIs beat expectations and pre-holiday buying stays firm, copper should press 6.889-6.926 into the Golden Week closure while corn stays capped near 515.00-510.00.
If Chinese demand slows sharply ahead of the holiday or the Dollar firms further on strong US jobs data, copper should slip toward 6.750-6.657 while corn could recover 526.50-530.50.
Nikkei 225 & Litecoin
If Thursday’s Tankan survey confirms firm corporate sentiment and the Yen stays soft, the Nikkei 225 should test 66,500-67,000, and continued ETF-process headlines should help Litecoin extend toward 75.00-78.13.
If US yields spike further on strong jobs data or Tankan disappoints, the Nikkei 225 should retreat toward 65,500-65,000 and Litecoin could pull back to 67.65-61.68.
Dogecoin
If whale accumulation continues and broader crypto risk appetite holds through the week, Dogecoin should press 0.0971-0.1000 and challenge its recent high near 0.1054.
If Friday’s payrolls report triggers renewed Fed-hike-driven de-risking across crypto, Dogecoin should retreat toward 0.0890-0.0822.
Weekly Summary
The week of 28 September to 2 October is an event-driven week for Asia, anchored by Tuesday’s RBA decision and closing with Friday’s US payrolls report. USD/JPY enters near 157.29, having pulled back below its 200-day average and easing BOJ intervention watch near the 160.00 line, while AUD/USD (~0.7024) faces its biggest single-day catalyst of the month when the RBA’s decision and guidance land Tuesday. Mid-week brings China’s final PMI releases before its National Day Golden Week closure (1-8 October), a key input for copper and corn positioning, alongside Japan’s quarterly Tankan survey on Thursday, a major test for the Nikkei 225’s Yen-driven outperformance. The week closes with a heavy US data slate — ADP, ISM Manufacturing and Non-Farm Payrolls — that will shape October Fed hike odds, currently near 70-72%. In crypto, Dogecoin’s whale accumulation and Litecoin’s golden-cross rally both carry into the week as follow-through tests. Key catalysts: Tuesday’s RBA decision, Wednesday’s China PMIs, Thursday’s Tankan survey and China’s Golden Week closure, and Friday’s US jobs report.
Week Ahead FAQ
Answers based on the week’s calendar and current positioning
Why is Tuesday’s RBA decision the week’s key event?
All big-four Australian banks expect a 25bp hike to 4.60%, and markets price it near 92%, so the outcome itself is largely priced. What moves AUD/USD is the RBA’s forward guidance on the pace of further tightening.
Why does China’s Golden Week matter for copper and corn?
Mainland Chinese markets close from 1 to 8 October for the National Day holiday, thinning liquidity and demand signals across metals and agriculture just as Wednesday’s PMIs deliver the last mainland data before the break.
What is the Tankan survey and why does it matter for the Nikkei?
The Bank of Japan’s quarterly Tankan survey gauges corporate sentiment among large manufacturers and non-manufacturers. As the first major confidence read since the recent Yen weakness and global bond-yield shock, it is a key input for whether the Nikkei’s rally can extend.
Why is Friday’s US jobs report important for Asian markets?
Non-Farm Payrolls is the clearest single signal on US labour market strength ahead of the Fed’s next decision. A strong print would likely firm October hike odds (currently near 70-72%), supporting the Dollar and pressuring Asian FX and risk assets; a weak print would do the opposite.
Why could the BOJ intervene this week?
USD/JPY has pulled back to 157.29 this week, though it remains within striking distance of the 160.00 level where Japan’s Ministry of Finance has intervened before, after already spending roughly ¥15.4 trillion defending the Yen since late July.
Why are Dogecoin and Litecoin still in focus this week?
Both carry fresh momentum into the week: Dogecoin from reported whale accumulation, and Litecoin from a daily golden cross amplified by Grayscale’s move to convert its Litecoin Trust into a spot ETF. The key question is whether that momentum survives the week’s heavier macro calendar.