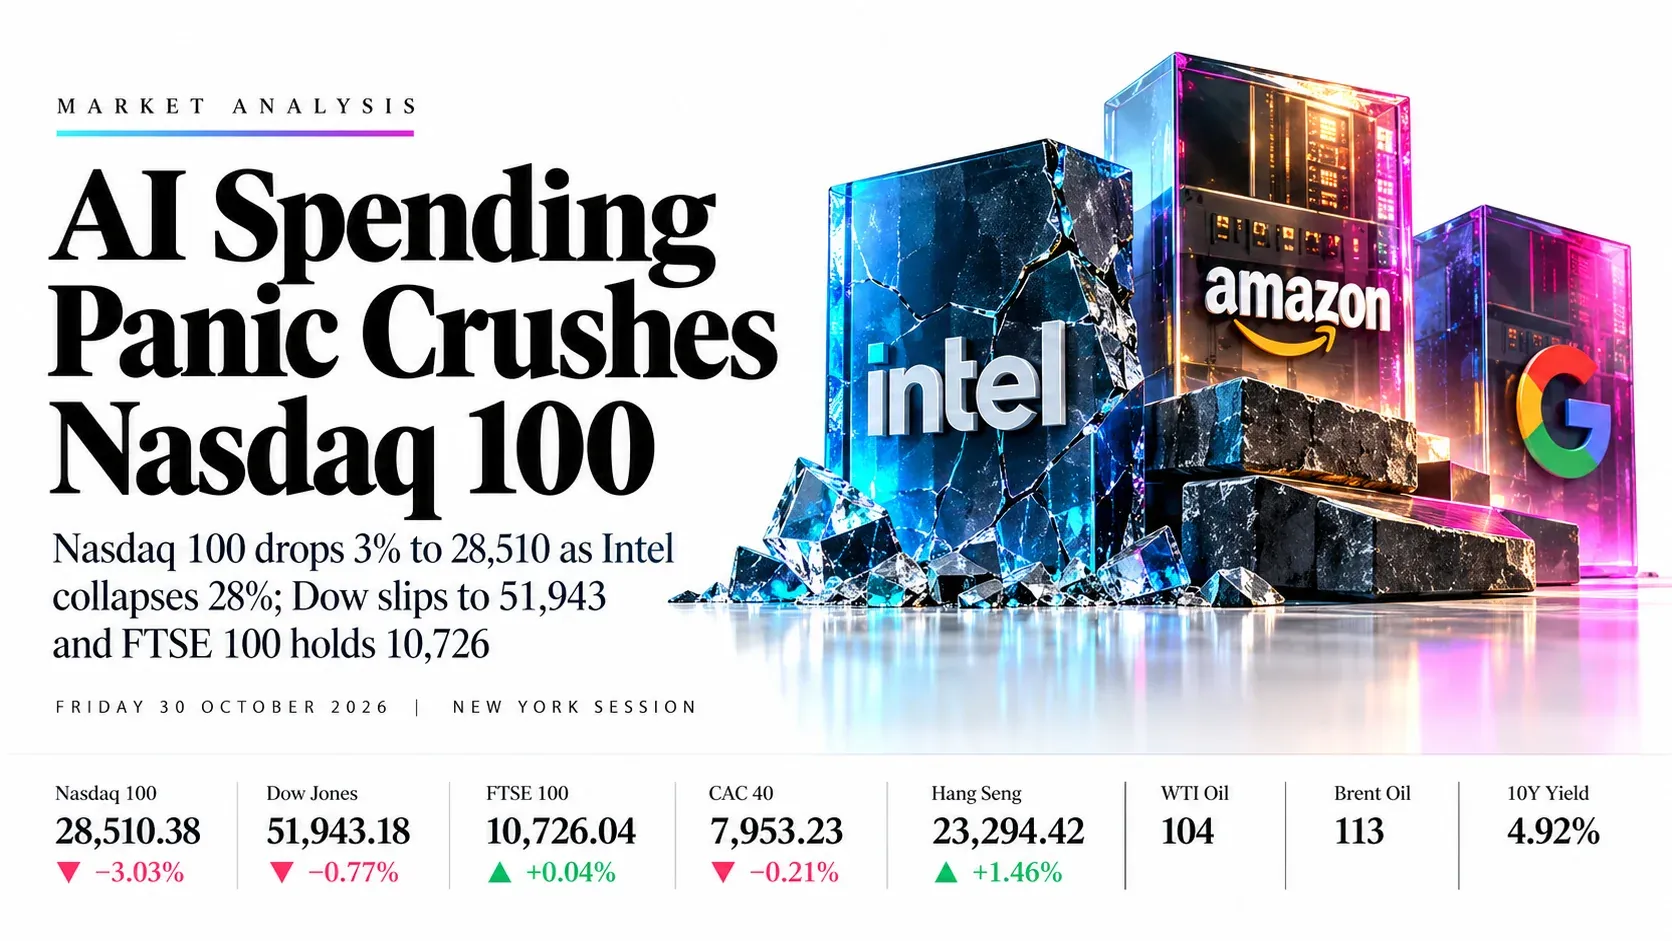
AI Spending Panic Crushes Nasdaq 100 by 3% to 28,510 as Intel Collapses 28%; Dow Slips to 51,943 and FTSE 100 Holds 10,726 | Technical Analysis – Index Report | 30 Oct 2026
Indices Today | Friday 30 October 2026 | New York session
AI Spending Panic Crushes Nasdaq 100 by 3% to 28,510 as Intel Collapses 28%; Dow Slips to 51,943 and FTSE 100 Holds 10,726
Market Overview
Wall Street’s AI trade is under fire. The Nasdaq 100 has lost almost 900 points to 28,510.38 (−3.03%), the worst index on the board, after Intel plunged about 28% on a weak outlook and Amazon’s $77bn of quarterly capex reopened the question of when AI spending pays off, one day after Alphabet’s record one-day fall. The Dow is down a far milder 0.77% at 51,943.18 as energy and defensive stocks cushion the blue chips, so the damage is concentrated in tech rather than spread across the market. Europe is split, with the FTSE 100 flat at 10,726.04 (+0.04%) and the CAC 40 down 0.21% at 7,953.23, while the Hang Seng closed 1.46% higher at 23,294.42. Momentum is weakest where the selling is heaviest: RSI is 35.85 on the Nasdaq 100 and 39.23 on the Hang Seng, against 47.34 on the Dow, 51.36 on the CAC 40 and 52.43 on the FTSE 100 as of about 16:10 GMT.
Rates and oil leave little room for a bounce. WTI near 104 and Brent near 113 keep inflation pressure high, and December Fed hike odds sit around 80% to 85%, yet the 10-year yield has slipped to about 4.92% as money rushes into bonds. The Employment Cost Index and Chicago PMI came in line, so neither shifts the Fed outlook. The next tests are Fed speaker Musalem at 16:30 GMT, the London and Paris close at 16:30 GMT and the US close at 20:00 GMT, where a hold above 28,000 on the Nasdaq 100 decides whether this is a sharp tech pullback or the start of a deeper break.
Key highlights
- Dow Jones: Price is 51,943.18 under three averages at 52,009 to 52,374; 51,300 is the triangle floor.
- Nasdaq 100: Price is 28,510.38 under the broken channel floor, with RSI 35.85; 28,470 and 28,000 are the supports.
- FTSE 100: Price is 10,726.04 on the 10,675 to 10,704 averages inside an ascending triangle.
- CAC 40: Price is 7,953.23 retesting the broken channel roof, with 7,860 the level to hold.
- Hang Seng: Price closed at 23,294.42 off the channel floor, with 23,737 the cap and RSI at 39.23.
What’s Moving Indices Today
Nasdaq 100 drops 3% as Intel sinks about 28% and Amazon falls on $77bn of quarterly capex
Intel’s outlook missed estimates and Amazon’s third-quarter capital spending of $77.3bn revived doubts about the payoff from AI, a day after Alphabet’s record one-day fall. The S&P 500 is down about 1.3% to 1.5% near its 100-day average, and a $6.3bn Binance hack has pushed bitcoin down about 4% and Coinbase down 11%.
Dow slips 0.8% as energy earnings and a rotation out of tech cushion the blue chips
The Dow is falling far less than the Nasdaq 100: Amazon is a heavy drag, while Chevron and Exxon Mobil rose after earnings beats on strong refining margins. Defensive buying is visible, with pharma and utilities holding up.
Oil near 104 and 10-year yield near 4.92% frame the session as December Fed hike bets stay around 80% to 85%
WTI is near 104 and Brent January near 113 on Hormuz tanker incidents, yet the 10-year Treasury yield is at a seven-week low as investors buy bonds against the equity sell-off. The US Employment Cost Index came in at 0.8% as expected and Chicago PMI at 55.3 against 55.8 expected, so neither changed the Fed outlook.
FTSE 100 holds a small gain as AstraZeneca and BT rise and NatWest falls 8%
AstraZeneca rose about 5% after a third-quarter profit beat with guidance unchanged, and BT gained on a report that Virgin Media O2 is close to a deal to use its Openreach network. NatWest fell about 8% after a net interest income miss, with Lloyds down about 3.5% and Rolls-Royce about 4.6%; the FTSE is heading for its first monthly gain in three months.
CAC 40 slips 0.2% as French GDP contracts 0.1% and Sanofi offsets tech weakness
INSEE reported France’s economy shrank 0.1% in the third quarter, while the euro zone grew 0.4% against 0.2% expected. Sanofi rose about 4.9% on third-quarter revenue growth of 14.3% at constant rates and Crédit Agricole reported net income up 17.9%, but Schneider Electric and Legrand fell near 3% with AI-linked names.
Hang Seng closes 1.46% higher at 23,294.42 on energy, insurers and shipping
Financial, energy, consumer and shipping shares led the rebound, helped by a 57% jump in Sinopec’s third-quarter profit, while AI hardware stocks kept falling after the US tech rout. The Hang Seng Tech Index rose 0.3% to 3,754.90, near a two-year low, and the Bank of Japan held rates steady.
Key Drivers for the Rest of Today
Seven things that set direction for the rest of the session in the Dow Jones, Nasdaq 100, FTSE 100, CAC 40 and Hang Seng. All times are GMT.
- AI spending and Big Tech headlines
- Ongoing
- Any time
- Intel, Amazon and Alphabet results drive the Nasdaq 100 first and spill into every index
- Hormuz and Houthi oil headlines
- Ongoing
- Any time
- WTI near 104 and Brent near 113; higher oil weighs on US and European equities and lifts FTSE energy
- December Fed hike bets
- Ongoing
- Any time
- Around 80% to 85%; the 10-year near 4.92% shows bond buying against the tech sell-off
- Fed’s Musalem speaks
- 16:30
- Fri 30 Oct, 16:30 GMT
- First Fed comments since the hold; a hawkish hint after Daly at 16:00 GMT would hit tech again
- London and Paris cash close
- 16:30
- Fri 30 Oct, 16:30 GMT
- FTSE 100 and CAC 40 cash sessions end; later moves run on the CFD feed
- Brent expiry and month-end flows
- Late
- Fri 30 Oct, into 20:00 GMT
- Brent December expires today; month-end rebalancing can distort the last hours
- US cash close
- 20:00
- Fri 30 Oct, 20:00 GMT
- The Nasdaq 100 closes a month with more than $2 trillion of value lost
Swipe the strip to see every driver.
Trade Setups for Today
Ranked in the order Dow Jones, Nasdaq 100, FTSE 100, CAC 40 and Hang Seng, valid for the rest of today’s session. A 1-hour close beyond the stop cancels the idea.
| Instrument | Direction | Entry | Stop | Target 1 | Target 2 | Reward:risk | Conviction |
|---|---|---|---|---|---|---|---|
| Dow Jones | Short | 52,120 | 52,420 | 51,600 | 51,300 | 1.7 / 2.7 | Low |
| Nasdaq 100 | Short | 28,900 | 29,160 | 28,470 | 28,000 | 1.7 / 3.5 | Medium |
| FTSE 100 | Long | 10,675 | 10,600 | 10,800 | 10,890 | 1.7 / 2.9 | Medium |
| CAC 40 | Long | 7,900 | 7,840 | 7,990 | 8,056 | 1.5 / 2.6 | Low |
| Hang Seng | Short | 23,650 | 23,900 | 23,050 | 22,700 | 2.4 / 3.8 | Low |
Reward:risk is the distance from entry to each target divided by the distance from entry to the stop. Prices are feed prices from the daily charts at about 16:10 GMT on 30 October. The London and Paris cash markets close at 16:30 GMT and Hong Kong has closed, so the FTSE 100, CAC 40 and Hang Seng ideas run on the CFD feed into the US close at 20:00 GMT. Every entry sits away from the current price and needs a bounce or a pullback to trigger. Levels are conditional technical references, not recommendations.
Risk Scenario Analysis
AI spending headlines, Hormuz news and Fed speakers at 16:30 GMT are the swing factors for the rest of today.
Tech rout deepens, oil climbs: weaker equities across the board
More weak AI-spending headlines or a Hormuz escalation would push the Nasdaq 100 and Dow to lower supports and keep European and Hong Kong CFDs under pressure.
- Dow Jones51,300, then 50,600
- Nasdaq 10028,470, then 28,000
- FTSE 10010,675, then 10,480
- CAC 407,860, then 7,690
- Hang Seng22,950, then 22,520
Tech steadies, oil eases: a relief bounce into resistance
A bounce in Amazon and Intel, softer Fed comments or Hormuz calm would let the oversold Nasdaq 100 retrace toward its broken channel floor while the FTSE 100 and CAC 40 test their highs.
- Dow Jones52,220, then 52,374
- Nasdaq 10028,900, then 29,554
- FTSE 10010,779, then 10,890
- CAC 407,992, then 8,056
- Hang Seng23,400, then 23,737
Dow Jones | TVC feed
Dow Jones Analysis: Price Slips Under Three Averages at the Edge of a Symmetrical Triangle
51,943.18 −405.06 (−0.77%) at about 16:10 GMT Previous close 52,348.24
Outlook: Bias is lower while 52,220 caps rallies, but the Dow is holding up far better than the Nasdaq 100. The index is down 0.8% near 51,943 as Amazon’s capex shock drags, while Chevron and other energy names gain on higher oil and a rotation out of tech cushions the blue chips.

Key levels
- Support 2
- 50,600
- Support 1
- 51,300
- Resistance 1
- 52,009
- Resistance 2
- 52,374
- Price (51,943.18) is under all three averages clustered at 52,009 to 52,374, and the falling triangle roof near 52,300 turned back today’s open; the rising line near 51,300 is the floor.
- RSI 47.34 is under its signal at 54.11 and below 50; a close under 51,300 breaks the triangle toward 50,600, while a move over 52,374 reopens 53,000.
Setup: Short at 52,120, stop 52,420, targets 51,600 and 51,300. Reward:risk 1.7 / 2.7, low conviction. A bounce into the 52,009 to 52,220 average zone that stalls is the entry. Energy earnings and the rotation out of tech can keep the Dow firm, and a 1-hour close over 52,420 cancels it.
Nasdaq 100 | NASDAQ feed
Nasdaq 100 Analysis: Price Breaks the Floor of a Rising Channel on a 3% Gap Down
28,510.38 −892.13 (−3.03%) at about 16:10 GMT Previous close 29,402.51
Outlook: Bias is lower while 28,900 caps rallies. The Nasdaq 100 is down 3% near 28,510 after Intel fell about 28% on its outlook and Amazon dropped on $77bn of quarterly capex, the second heavy tech sell-off in a row after Alphabet’s record fall; the index is on course to lose more than $1 trillion in value today.

Key levels
- Support 2
- 28,000
- Support 1
- 28,470
- Resistance 1
- 28,900
- Resistance 2
- 29,554
- Price (28,510.38) opened at 28,604.92 and stayed near the low of 28,471.36, so the broken channel floor near 28,900 is now resistance, with all three averages above at 29,554 to 29,939.
- RSI 35.85 is under its signal at 42.78 and close to oversold; a close under 28,470 targets 28,000 and then the July low near 27,100, while a recovery over 28,900 opens 29,554.
Setup: Short at 28,900, stop 29,160, targets 28,470 and 28,000. Reward:risk 1.7 / 3.5, medium conviction. A bounce back to the broken channel floor is the entry, because selling a 3% gap at the lows chases the move. Short covering into the close or a calm in Amazon and Intel can squeeze it, and a 1-hour close over 29,160 cancels it.
FTSE 100 | FTSE feed
FTSE 100 Analysis: Price Holds Above Three Averages Inside an Ascending Triangle
10,726.04 +3.97 (+0.04%) at about 16:10 GMT Previous close 10,722.07
Outlook: Bias is mildly higher while 10,675 holds. The FTSE 100 is flat near 10,726 after a high of 10,778.72 while the CAC 40 and DAX trade lower, as gains in AstraZeneca and BT offset heavy falls in NatWest, Lloyds and Rolls-Royce.

Key levels
- Support 2
- 10,480
- Support 1
- 10,675
- Resistance 1
- 10,779
- Resistance 2
- 10,890
- Price (10,726.04) is just above all three averages at 10,674 to 10,704, which have held every dip today, and the rising floor near 10,480 is well below.
- RSI 52.43 is under its signal at 54.42 and flat; a close over 10,779 targets 10,890, while a close under 10,675 puts 10,480 in play.
Setup: Long at 10,675, stop 10,600, targets 10,800 and 10,890. Reward:risk 1.7 / 2.9, medium conviction. A dip into the averages is the entry. Banks are weak, and a US-led risk-off move after the 16:30 GMT cash close can pull the CFD lower; a 1-hour close under 10,600 cancels it.
CAC 40 | TVC feed
CAC 40 Analysis: Price Retests the Broken Roof of a Falling Channel With RSI Above 50
7,953.23 −16.78 (−0.21%) at about 16:10 GMT Previous close 7,970.01
Outlook: Bias is neutral to higher while 7,860 holds, but follow-through is thin. The CAC 40 is down 0.2% near 7,953 as Sanofi’s 4.9% jump offsets falls in Schneider Electric and Legrand, while French GDP shrank 0.1% in the third quarter against euro zone growth of 0.4%.

Key levels
- Support 2
- 7,690
- Support 1
- 7,860
- Resistance 1
- 7,992
- Resistance 2
- 8,056
- Price (7,953.23) is above the channel roof near 7,900 and the 7,859.68 short average, but under the 8,056 and 8,260 averages, which cap any extension.
- RSI 51.36 is above its signal at 43.88; a close over 7,992 opens 8,056, while a close back under 7,860 returns price inside the channel and targets 7,690.
Setup: Long at 7,900, stop 7,840, targets 7,990 and 8,056. Reward:risk 1.5 / 2.6, low conviction. A retest of the broken roof is the entry. Weak French growth and falling tech names can pull price back inside the channel, and a 1-hour close under 7,840 cancels it.
Hang Seng | HSI feed
Hang Seng Analysis: Price Bounces Off the Floor of a Falling Channel With RSI at 39.23
23,294.42 +335.77 (+1.46%) at the 08:00 GMT close Previous close 22,958.65
Outlook: Bias stays lower inside the channel while 23,737 caps rallies. The Hang Seng closed up 1.46% as energy, insurers and shipping shares rose, but AI hardware stocks stayed weak, the Tech index sits near a two-year low, and mainland investors have sold a net HK$24bn of Hong Kong shares this month.

Key levels
- Support 2
- 22,520
- Support 1
- 22,950
- Resistance 1
- 23,400
- Resistance 2
- 23,737
- Price (23,294.42) is in the lower third of the channel and 1.9% under the 23,737 short average, while the 24,576 and 24,616 averages sit on the channel roof, so rallies meet heavy supply.
- RSI 39.23 has turned up through its signal at 36.86 but is still under 50; a close over 23,400 opens 23,737, while a drop back under 22,950 targets the June low near 22,520.
Setup: Short at 23,650, stop 23,900, targets 23,050 and 22,700. Reward:risk 2.4 / 3.8, low conviction. A rally into the 23,737 average is the entry. Hong Kong is closed, so the idea runs on the CFD feed, oversold bounces can extend, and a 1-hour close over 23,900 cancels it.
Conclusion
The tech sell-off dominates, so we prefer selling bounces in the Nasdaq 100 near 28,900 (medium conviction) and the Dow near 52,120 (low conviction), with the Hang Seng near 23,650 a low-conviction short on the CFD feed. The FTSE 100 near 10,675 is the buy-the-dip idea on its averages, and the CAC 40 near 7,900 is a low-conviction long on the channel retest. The session risks are Musalem at 16:30 GMT, the London and Paris close at 16:30 GMT, Hormuz headlines and month-end flows into 20:00 GMT. A 1-hour close over 29,160 in the Nasdaq 100 or under 10,600 in the FTSE 100 would change the picture.
Trade the Dow Jones, Nasdaq 100, FTSE 100, CAC 40 and Hang Seng with Capital Street FX.
Frequently Asked Questions
Why is the Nasdaq 100 falling today?
Intel’s weak outlook and Amazon’s $77bn quarterly capex have renewed worries about AI spending after Alphabet’s record drop. The index is down about 3% near 28,510 and on course to lose more than $1 trillion in value today.
Where is support for the Nasdaq 100 and the Dow?
The Nasdaq 100 has 28,470 and then 28,000, with 28,900 as resistance. The Dow has the triangle floor near 51,300 and then 50,600, with 52,009 to 52,374 overhead.
Why is the FTSE 100 holding up?
AstraZeneca, BT and defensive stocks are offsetting banks, and the index has little direct tech exposure. It is flat near 10,726 and the 10,675 to 10,704 averages are first support.
What does the French GDP contraction mean for the CAC 40?
France shrank 0.1% in the third quarter while the euro zone grew 0.4%, which adds to political and budget worries. Sanofi’s jump is holding the index near 7,953, with 7,860 as the level to defend.
Why did the Hang Seng rebound?
Energy, insurers, consumer and shipping shares rose, helped by Sinopec’s profit jump. The index closed at 23,294.42, but AI hardware stocks and net selling by mainland investors keep the trend under 23,737 lower.