From Pharaoh’s Granaries to the Petrodollar | Daily Blog | 24-09-2026
From Pharaoh’s Granaries to the Petrodollar Do markets move in supercycles — and are we inside one?
Joseph told Pharaoh to store grain through seven fat years for the seven lean ones to come. In 1377, Ibn Khaldun watched dynasties rise and decay over three generations. Since then the centre of the world’s money has passed from Genoa to Amsterdam, London and New York; sterling left gold and went back; the dollar was tied to gold, cut loose, and tied to oil instead. Through all of it, the price of raw materials and the value of money have moved together in long waves lasting a decade or more. This article asks whether those waves are real, how to recognise one, whether one is under way today, what is driving it, and where it may be heading.
- Do supercycles exist in commodities, in currencies and in markets generally? Sections 02–04
- How do you tell one from an ordinary bull market or a one-off shock? Section 05
- Is one under way now, and what is its theme? Section 06
- Where are we in it, and what could come next? Sections 07–08
The Oldest Pattern in Markets
Long before anyone traded a futures contract, people noticed that plenty and scarcity arrive in runs. The story of Joseph in Genesis is, at heart, a story about positioning ahead of a cycle: store grain while it is cheap and abundant, because lean years will follow. Medieval scholars saw the same rhythm in the rise and fall of dynasties. Victorian economists saw it in the price of wheat and the purchasing power of gold. Twentieth-century traders saw it in oil, in the dollar, and in the long bear markets that followed every boom.
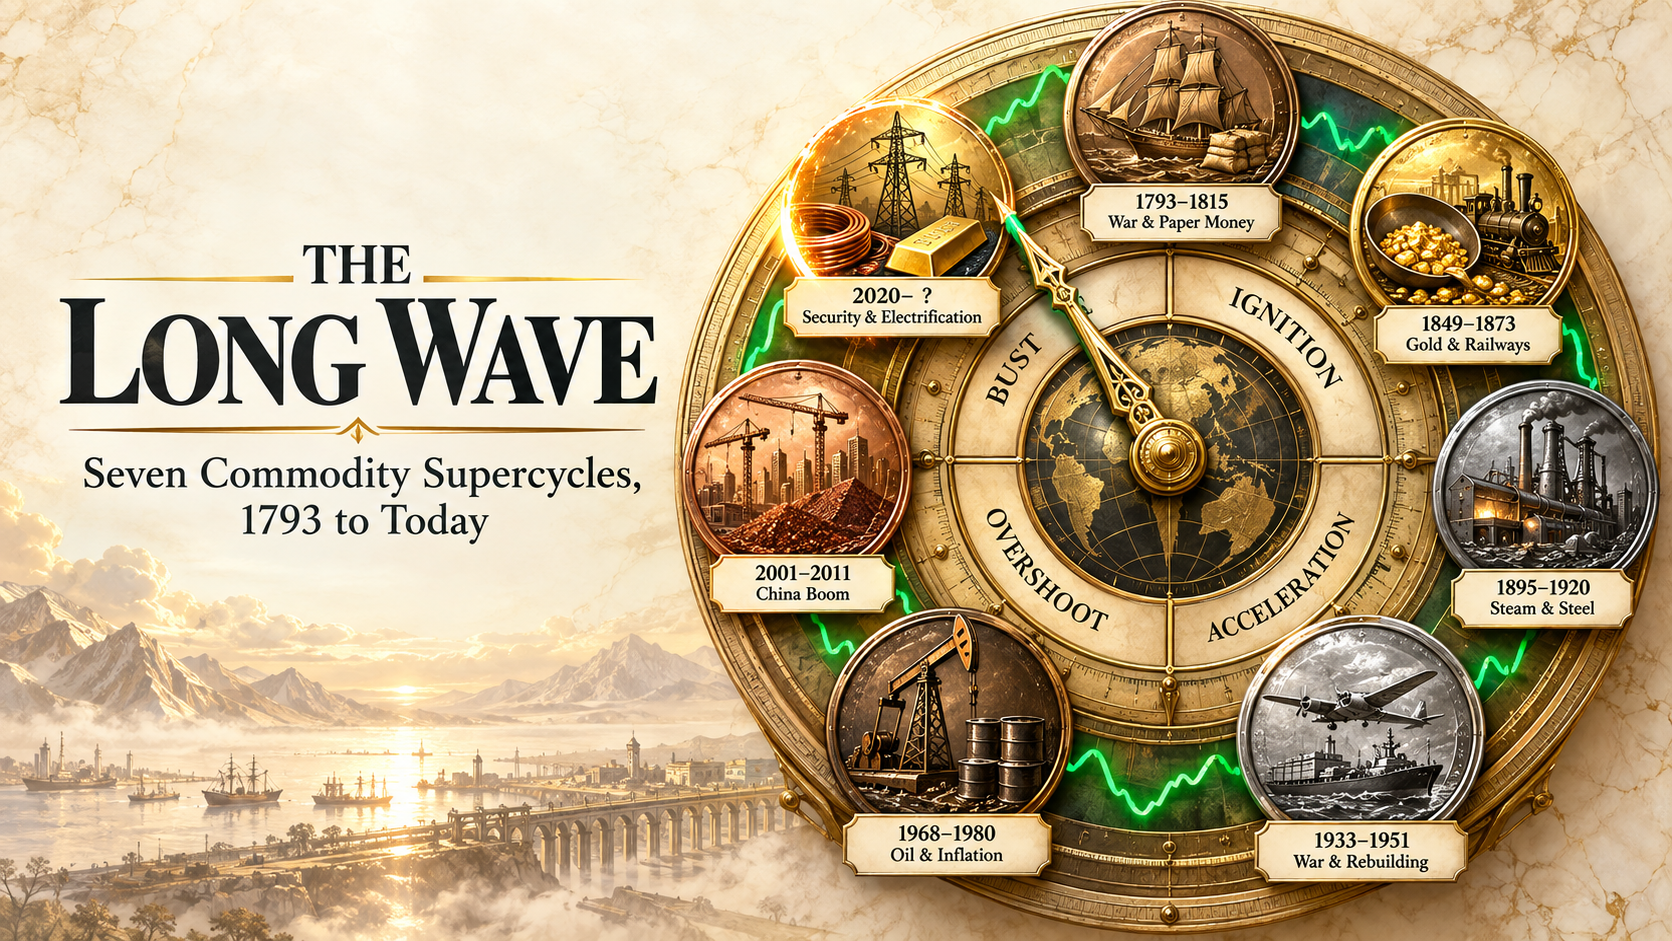
The recurring shape is easy to describe. For a decade or more, the prices of raw materials rise together, well above their long-run trend. Capital floods into the industries that produce them. Then new supply arrives, money tightens, and prices fall for years, sometimes for a generation. The bust starves those industries of investment, and the shortage that follows plants the seed of the next boom. Economists have documented seven of these waves since 1793: the paper-money inflation of the Napoleonic Wars, the gold rushes and railways of the mid-nineteenth century, the age of steam and steel that ended after the First World War, reflation and reconstruction around the Second World War, the inflation and oil shocks of the 1970s, and China’s urbanisation in the 2000s. The seventh is the subject of Section 06.
These are never only commodity stories. In almost every wave, the money changed at the same time as the metal. Britain suspended gold in 1797 and returned to it in 1821. Roosevelt devalued the dollar against gold in 1934. Nixon cut the dollar loose from gold in 1971, and within three years it had been tied to oil instead. In 2022 the freezing of Russia’s central bank reserves made governments everywhere rethink what a safe reserve asset is. The same forces set the path of interest rates, bond yields and the equity sectors tied to raw materials. A supercycle is a commodity story, a currency story and a market story at once.
There is also a serious case that all of this is an illusion. People are very good at finding patterns in noise. Seven episodes in 230 years is a small sample, the dates move depending on which price index you use, and each wave had its own unrepeatable cause, whether a world war, an oil embargo, or a billion people moving to cities. Section 02 takes that objection seriously before the article draws any conclusions.
The article then works through the question in order. Section 02 explains where the theory came from and where it is weak. Section 03 tells the story of the seven waves from 1793 to today, in sequence, so that you can see how each one ended and the next began. Section 04 follows the currency underneath them. Section 05 turns that history into a six-lens test for telling a genuine supercycle from an ordinary bull market. Section 06 applies the test to the period since 2020, to judge whether a cycle is under way and what its theme is. Sections 07 and 08 set out where it could go next and how a trader might position. Prices in this period have already swung sharply in both directions, which is exactly why a framework matters more than any single price level.
What the article finds
- Supercycles are real as regimes, not as clocks. Seven decade-plus upswings are documented since 1793. None repeated on a fixed schedule, but each had the same structure: a demand shock meeting supply that could not respond for years.
- Commodities and currencies move as one system. The largest modern commodity booms, in the 1970s and the 2000s, both ran inside long periods of dollar weakness. The strongest dollar rallies ended them.
- A six-lens test separates regimes from rallies. Demand shock, scarcity, money, statecraft, the capital cycle and breadth. A genuine supercycle scores well on at least four, including the first two.
- On that test, the period since 2020 qualifies as a seventh cycle. Its theme is security and electrification: energy security, rearmament, grid and data-centre building, and a change in how central banks hold reserves.
- Its weakest point is money. Unlike the 1970s and 2000s, this cycle has not had a weak dollar behind it. The framework places it in its middle years, a phase in which sharp reversals are normal; Section 07 sets out what would confirm the cycle and what would break it.
The Soviet Economist, the Austrian Who Saved Him, and the Two Who Said He Was Wrong
The belief that human affairs move in long rhythmic waves is older than economics. In 1377, the North African scholar Ibn Khaldun described dynasties rising and decaying over roughly three generations as prosperity bred complacency and tax burdens grew. Genesis 41 gave us Joseph’s seven fat years and seven lean ones — the oldest documented recommendation to store commodities against a future scarcity that experience predicted. The intuition that boom follows bust, and that the cycles are longer than any single political career, is ancient.
But the modern, quantitative investigation of long commodity cycles began with a 30-year-old Soviet economist working in Moscow in the early 1920s. Nikolai Dmitriyevich Kondratiev had assembled wholesale price series, interest rate data, and production statistics stretching back through the 18th and 19th centuries. What he found were unmistakable long rhythms — he called them bolshie tsikly, or “long waves” — cycling roughly every 50 to 60 years, visible across multiple countries and multiple commodity classes simultaneously. He published his major work, The Major Economic Cycles, in 1925.
The political consequences were immediate and fatal to the man, if not the idea. If capitalism moved in self-correcting waves — recovering from its downturns rather than collapsing toward destruction — then Marxist-Leninist orthodoxy was directly contradicted. Kondratiev was arrested in 1930, sentenced in a Stalinist show trial, and shot in 1938. He was 46 years old.
His ideas survived through the Austrian-American economist Joseph Schumpeter, who named the waves “Kondratieff Waves” in Kondratiev’s honour in his 1939 masterwork Business Cycles. Schumpeter gave the theory its most compelling mechanism: each long wave was powered by a cluster of radical innovations — steam and textiles, then railways and steel, then electricity and chemicals, then the automobile and oil. These technology revolutions did not merely create new products. They reorganised entire economies, destroyed old industries, attracted vast capital, and generated multi-decade demand for the raw materials needed to build and power the new world. The wave crested when the transformation matured; the bust planted the seeds of the next innovation cluster.
Meanwhile, a rival tradition was developing in a very different corner of economics. In 1950, two economists working independently — Raúl Prebisch at the UN Economic Commission for Latin America, and Hans Singer at the UN Secretariat in New York — both published papers arguing that commodity prices had been drifting downward against manufactured goods prices over the long run. This became the Prebisch-Singer Hypothesis: that commodity exporters (mostly developing nations) faced a structural deterioration in their terms of trade. In this framework, commodity booms are temporary, cyclical reversals of a secular downtrend — not supercycles at all, but temporary noise around a falling mean.
These two traditions — Kondratiev’s long cycles versus Prebisch-Singer’s secular decline — define the intellectual tension that still underlies the supercycle debate. The modern resolution, supported by academic research from Cuddington and Jerrett (2008, IMF) and Erten and Ocampo (2013), is that both can be simultaneously true: there is a long-run declining trend in real commodity prices (consistent with Prebisch-Singer), superimposed on which there are large-amplitude cycles of 20–70 years that can run counter to the trend for a decade or more. The supercycle is not a contradiction of the secular decline. It is a powerful interruption of it.
The term “supercycle” itself became common in financial markets during the early 2000s. Citigroup’s Alan Heap used it in a widely circulated 2005 research note arguing that China was powering a new commodities super cycle. Jim Rogers had already made the bull case in his 2004 book Hot Commodities. By 2008, the concept had become mainstream — just in time for the 2008 crash to test whether true believers would maintain conviction through a 40–50% commodity correction before the bull resumed. Most did not.
“A supercycle is not a forecast. It is a framework for asking the right questions about why prices are where they are and whether the regime that put them there is still intact.”
The Case For: Why Supercycles Should Exist
The structural argument is straightforward. Commodity supply — mines, oil fields, refineries — is inelastic. You cannot double copper output in 18 months. A new copper mine requires 10 to 16 years from discovery to production. Oil projects in complex geologies take longer. When demand shifts structurally upward — driven by a new industrial giant or a technological revolution — the supply response lags by a decade or more. During that lag, prices rise and remain elevated. Eventually, supply catches up. The boom ends. The bust that follows destroys the capital investment that would have kept supply growing, planting the seed of the next shortage.
This mechanism is observable and repeatable. It is not a mystery or a statistical artefact. It follows from the geology and engineering of extractive industries, combined with the psychology of capital markets that systematically over-invests near peaks and under-invests near troughs.
The Case Against: Why Scepticism is Warranted
The sceptical case is equally coherent. Statistical filters can find cycles in random data — this is a known problem in econometrics called “spurious periodicity.” Seven episodes in two centuries provide too few observations to establish statistical periodicity with rigour. Dates shift materially depending on which commodity index, price deflator, and cycle definition you choose. And perhaps most damning: no analyst has consistently identified supercycle turning points in real time. The pattern is almost always clearer in retrospect than in the moment. The strongest form of the sceptical argument is simply that each “supercycle” was driven by a single unrepeatable shock — a world war, an oil embargo, China’s unique once-in-history urbanisation — and that labelling these diverse episodes as a recurring phenomenon is intellectual post-hoc rationalisation.
A Working Answer
The right position is neither credulous nor sceptical. Supercycles are best understood as regimes: multi-year alignments of a large demand shock, constrained supply, supportive monetary conditions, and state action, that persist until the alignment breaks. They are not clocks. They do not arrive on schedule. But when the alignment of forces is strong enough, the resulting price regime is real, persistent, and large enough to matter enormously for investors, companies, and governments. The question is not “will the next supercycle arrive in 50 years?” It is “do the conditions for a sustained commodity price regime exist right now?”
The gold band marks the 20–70 year window where academic research has found supercycles in price data. Cycles outside this band exist in other fields but lack commodity price evidence.
Sources: Cuddington & Jerrett (2008); Erten & Ocampo (2013); Kondratiev (1925); Modelski (1987); Turchin & Nefedov (2007); Dalio (2021). Only the Markets group has been tested on actual commodity price data.
Seven Waves · Two Hundred and Thirty Years of Commodity History
The history of commodity and currency cycles since the late 18th century is not a collection of unrelated episodes. It is a single continuous story in which each wave’s ending creates the conditions for the next wave’s beginning. What follows is that story, told in sequence — with the monetary dimension woven in throughout, because you cannot separate what happened to commodity prices from what was happening to money at the same time.
Shaded bands mark documented commodity upswings. The strip below shows monetary regimes — from the gold standard era through Bretton Woods to the floating dollar and de-dollarization. The overlap between weak-dollar eras and commodity booms is not coincidental.
Commodity price line is stylised. Dollar regime bar: before 1914 = gold standard; 1944–71 = Bretton Woods fixed rates; thereafter alternating weak/strong dollar cycles. The two largest modern booms (1968–80, 2001–11) both sat inside prolonged dollar downtrends.
Wave 1 · War and Paper Money · 1793–1815
The story begins in an era before industrial commodities mattered at scale — when the key traded goods were grain, metals, timber, and shipping. The French Revolutionary and Napoleonic wars, which consumed the major European powers from 1793 to 1815, were the trigger. Britain’s war effort demanded materials it could not produce quickly enough, and in 1797 the government suspended gold convertibility — meaning the Bank of England could print money without the constraint of gold reserves. Prices began to climb.
The intellectual response to this inflation was as significant as the inflation itself. David Ricardo‘s 1810 pamphlet on the high price of bullion launched what we now call monetary economics: the systematic analysis of the relationship between money supply, prices, and exchange rates. Ricardo’s arguments — that inflation is ultimately a monetary phenomenon driven by excess money creation — were as relevant to the Fed’s 2022 dilemma as to Britain in 1810.
Commodity prices peaked around 1813–1814 as Napoleon’s position deteriorated. After Waterloo in 1815, Britain returned to the gold standard in 1821, imposing a deflationary discipline that drove prices lower for years. The wave ended. But it taught the first recorded lesson of supercycle investing: the same governments that spend money into existence during a boom will eventually impose the discipline that ends it. Debt-funded wars inflate. Peace deflates.
A footnote that became a lesson: Mount Tambora erupted in April 1815 — the largest volcanic eruption in recorded history — producing the “Year Without a Summer” in 1816. Crop failures across Europe and North America sent grain prices spiking violently. The first documented case of a volcanic climate shock producing a commodity price crisis on a continental scale.
Wave 2 · Gold Rushes and Railways · 1849–1873
The trough of the 1820s–40s deflation created the conditions for the next wave. The discoveries of gold in California (1848) and Australia (1851) were not merely commercial events — they were monetary events. They expanded the world’s supply of money metal at precisely the moment when a new technology was creating voracious new demand for industrial commodities. The railway age, which had begun tentatively in Britain in the 1830s, was now sweeping across Europe and North America. Iron, steel, coal, copper, and timber were consumed in quantities that strained existing supply chains. Railway construction was not just transportation — it was the greatest single act of industrial commodity demand the world had yet seen.
The US Civil War (1861–65) added a demand shock within the demand shock. The Union blockade of Confederate ports strangled cotton exports and produced the Lancashire cotton famine — mills across northern England idle for lack of raw cotton, prices trebling, factory workers in poverty despite working in what was then the world’s most advanced industrial region. Stanley Jevons measured the fall in gold’s purchasing power against a basket of goods in 1863, providing the first quantitative evidence of a gold-supply-driven commodity cycle.
The wave ended when Germany unified and adopted the gold standard in 1871–73, absorbing enormous quantities of gold to back its new Reichsmark while simultaneously dumping silver — previously a monetary metal — onto world markets. The Panic of 1873 followed. What Victorians called the “Great Depression” (before the 1930s claimed that name) lasted until about 1896: two decades of falling prices, agricultural distress, and political upheaval.
The Great Deflation and the Cross of Gold · 1873–1896
The two-decade deflation that followed Wave 2 deserves its own attention because it shows what a commodity bust looks like when it runs its full course — and because it produced political consequences that resonate today. Prices in Britain and the United States fell by roughly a third over twenty years. Cheap grain from the American prairies arrived in European markets via steamships, the Suez Canal (opened 1869), and new railway connections. Technological progress in agriculture improved yields. The monetary base shrank relative to economic activity. It was the first great global supply glut.
American farmers caught between falling grain prices and fixed debt were enraged. The political expression of their rage was the demand for bimetallism — backing the dollar with both gold and silver, which would expand the money supply and, they hoped, reflate prices. William Jennings Bryan, at the 1896 Democratic National Convention in Chicago, delivered the most famous economic speech in American history: “You shall not press down upon the brow of labour this crown of thorns. You shall not crucify mankind upon a cross of gold.” Bryan lost the election. But new gold from the Witwatersrand fields in South Africa (discovered 1886) and the cyanide extraction process accomplished what silver would have: expanded money supply, lifted prices, and ended the deflation. The trough of 1896 is where most modern academic dating of commodity supercycles begins.
Wave 3 · Steam, Steel and the First Industrial Supercycle · c.1895–1920
From the trough of 1896, a genuine industrial supercycle emerged for the first time in history. The United States was transforming at breathtaking speed. Andrew Carnegie’s Homestead steel plant in Pennsylvania was the most technologically advanced manufacturing facility in the world. John D. Rockefeller’s Standard Oil controlled 90% of US refining capacity. Between 1869 and 1900, the number of American railroad miles tripled, then tripled again. The internal combustion engine, electrical power grids, and mass-production manufacturing were remaking the economy simultaneously. JP Morgan’s 1901 creation of US Steel — the world’s first billion-dollar company — absorbed Carnegie’s empire for $480 million and symbolised the scale of commodity demand this transformation was generating.
Germany was industrialising in parallel. The Kaiser’s naval arms race with Britain drove steel and coal demand. Europe was also electrifying, with copper the critical material for every wire, motor, and generator. The Klondike gold rush of 1896–99 loosened monetary conditions. And then World War I — the most industrialised conflict in history — consumed materials at a rate that peacetime markets could never have anticipated.
The cycle peaked in 1917–1920 as wartime demand hit its apex. The 1920–21 deflation that followed was brutal: US wholesale prices fell by more than a third in 18 months. The cycle had ended. But the world that emerged — electrified, motorised, with global shipping networks carrying bulk commodities across oceans — was entirely different from the world of 1895. The wave had rewritten the infrastructure of civilisation.
The Interlude: 1920–1933 and the Great Depression
The 1920s were a false recovery. Agricultural prices never returned to wartime levels; farmers across the US Midwest faced a grinding deflation throughout the decade while stock markets boomed. The 1929 crash and ensuing Great Depression produced the deepest commodity price collapse in modern history: iron ore prices fell 70%, copper 75%, wheat 65%, oil 65%. At the trough of 1932, commodity markets were as depressed as they had been in 1896 — but with no Witwatersrand discoveries in sight. It required a deliberate act of monetary policy to break the deflationary spiral, and that act set the stage for the next wave.
Wave 4 · Reflation, War and Reconstruction · 1933–1951
On April 5, 1933, President Franklin Roosevelt issued Executive Order 6102 making it illegal for US citizens to own gold coins or bullion. He then raised the official gold price from $20.67 to $35 per troy ounce — a deliberate 69% devaluation of the dollar against gold designed to break the deflationary spiral. Commodity prices, priced in dollars, immediately rose. This was the first time a US president had explicitly used the currency as a commodity price policy tool. It would not be the last.
Rearmament followed deflation. By the mid-1930s, Germany, Japan, Italy, and then the Allied powers were racing to rebuild their militaries, creating fresh demand for steel, aluminium, copper, and petroleum. The Second World War then consumed industrial materials at civilisational scale: the United States produced 300,000 military aircraft, 102,000 tanks, and 2.4 million trucks between 1939 and 1945. American steel output peaked at 80 million tonnes in 1944 — a record that stood for decades. Aluminium, barely 100,000 tonnes annually before the war, reached 700,000 tonnes by 1943 as aircraft construction demanded it.
The wave’s second, more sustained phase came from postwar reconstruction. The Marshall Plan channelled $13.3 billion in American aid into European economies between 1948 and 1952. West Germany’s Wirtschaftswunder saw industrial production quadruple between 1950 and 1960. Japan’s recovery was equally extraordinary. Both rebuilt economies consumed steel, cement, copper, and energy continuously for over a decade. In July 1944, delegates from 44 nations had gathered at Bretton Woods, New Hampshire, to design a new monetary order with the dollar at its centre — convertible to gold at $35 per ounce, and the anchor of every other currency. The arrangement gave the postwar commodity boom a stable monetary floor. It also planted the seed of the monetary crisis that would ignite the next wave.
Wave 5 · The Dollar Crisis, OPEC, and the Age of Inflation · 1968–1980
This is the wave that most directly shaped the modern financial system — and the one with the most to teach about the relationship between currencies and commodity markets.
By the late 1960s, the United States was simultaneously fighting an expensive war in Vietnam and financing President Johnson’s Great Society social programmes. The resulting fiscal deficits were producing dollar outflows in excess of US gold reserves. France under de Gaulle was aggressively converting dollar holdings into gold. The arithmetic of Bretton Woods was becoming impossible: the US owed more gold than it held.
On the evening of Sunday, August 15, 1971, President Nixon addressed the nation to announce what he called a “new economic policy.” In three minutes, he ended the Bretton Woods system: the US would no longer convert dollars into gold. The world’s monetary system, anchored to a physical commodity for more than two centuries in various forms, became a system of pure government promises. The dollar fell. Commodity prices, no longer anchored to a fixed gold price, began their ascent.
What transformed a currency devaluation into a civilisational commodity shock was geopolitics. On October 6, 1973 — Yom Kippur — Egypt and Syria launched a surprise attack on Israel. The US airlifted military supplies to Israel. Arab members of OPEC responded on October 17 by announcing production cuts of 5% per month. Saudi Arabia imposed a complete embargo. Oil stood at $2.90 per barrel in September 1973. By December 22, OPEC’s posted price was $11.65 — a near-quadrupling in under three months. Sheikh Ahmed Yamani, Saudi Arabia’s oil minister, was the public face of the most effective commodity cartel in history. Yamani understood something that most market participants did not: OPEC had not merely raised the price of oil. It had demonstrated that physical commodity supply could be weaponised as geopolitical leverage. The precedent would echo for fifty years.
The downstream consequences were profound. The US experienced fuel shortages for the first time since World War II. Queues stretched for miles at petrol stations. The economy entered stagflation — the previously considered impossible combination of high inflation and stagnant growth. A second oil shock arrived in 1979 when the Iranian Revolution removed Iranian oil from world markets. Oil climbed from $15 to $35 per barrel. Gold, which had been fixed at $35 per ounce under Bretton Woods, soared to $850 per troy ounce in January 1980 — a 24-fold increase in nine years. Silver, manipulated by the Hunt Brothers of Texas who attempted to corner the entire silver market, briefly approached $50.
The monetary response that ended the wave was as dramatic as the shock that started it. Paul Volcker, appointed Federal Reserve Chairman by President Carter in August 1979, raised the Federal Funds Rate to an extraordinary 20% by June 1981. The resulting recession was the sharpest since the Great Depression. Unemployment hit 10.8%. But inflation was broken. The dollar soared. And commodity prices entered a prolonged bear market that would last through the rest of the 1980s and most of the 1990s, punctuated by oil’s collapse below $10 per barrel in 1986 as Saudi Arabia opened the taps on production, flooding a market already weakened by conservation and new supply from the North Sea and Alaska.
One further monetary innovation defined the period. In 1974, Secretary of State Henry Kissinger negotiated a secret agreement with Saudi Arabia: the Kingdom would price all oil sales exclusively in US dollars and recycle the resulting surpluses into US Treasury bonds. In exchange, the US provided military security guarantees for the Saudi regime. This arrangement — the petrodollar system — was the replacement for gold convertibility. Every nation that needed oil needed dollars. The dollar remained the world’s reserve currency not through gold but through oil. It was a geopolitical stroke of genius. It was also a system that required permanent US current account deficits and an asymmetric relationship between the US and oil-producing nations that would eventually generate its own contradictions.
Wave 6 · The China Supercycle · 2001–2011
After Volcker’s rate shock, the 1980s and 1990s were a commodity desert. A strong dollar, falling inflation, the collapse of the Soviet Union, and new supply from shale and offshore fields kept commodity prices structurally depressed. Junior mining stocks traded at distressed valuations. Exploration budgets were gutted. A generation of mining engineers left the industry. The capital starvation of the 1990s — rational at the individual company level — was planting the seeds of the next supply shortage.
The trigger arrived on December 11, 2001: China’s accession to the World Trade Organisation. Within weeks, China’s export-led manufacturing machine began to accelerate at a pace that no supply chain, logistics network, or commodity producer had anticipated. But the deeper driver was not trade policy. It was demography and urbanisation at civilisational scale. China was moving 800 million people — the equivalent of two and a half United States — from subsistence farming to urban industrial life over two decades. Each new city dweller needed housing, roads, electricity, appliances, and transportation. Each required steel, cement, copper, aluminium, and oil.
The numbers that resulted were almost incomprehensible. Between 2002 and 2011, China consumed more cement than the United States had used in the entire 20th century. China’s share of global copper consumption rose from 12% in 2000 to 40% by 2011. Iron ore demand grew 800%. Alan Heap at Citigroup named it the “commodities super cycle” in 2005. Jim Rogers had already moved to Singapore in 2007, buying a mansion and enrolling his daughters in Mandarin school, so convinced was he of the commodity thesis. Ivan Glasenberg built Glencore into the world’s largest commodity trading empire. Tom Albanese and Marius Kloppers ran Rio Tinto and BHP respectively through their most profitable decade in history.
Oil reached an all-time nominal record of $147.27 per barrel on July 11, 2008. Copper peaked at $8,985 per tonne that same year. The Global Financial Crisis then crashed both — copper fell to $2,800 per tonne in months, oil to $32. But China’s 4 trillion yuan ($586 billion) fiscal stimulus, announced in November 2008, was almost entirely infrastructure-focused. It rescued the commodity cycle: copper returned to all-time highs within two years, reaching $10,190 per tonne in February 2011. Iron ore peaked at $187 per tonne the same year.
The symbol of excess was Rio Tinto’s acquisition of Canadian aluminium producer Alcan in 2007 for $38 billion — the largest mining deal in history at that point, completed at the very top of the cycle. The resulting $14 billion in write-downs became the canonical example of how supercycles punish those who mistake a regime for a permanent state of affairs. Tom Albanese resigned in 2013. The lesson was brutal and precise: the cycle does not care about your acquisition price.
The cycle ended as China’s infrastructure build-out matured. The country had built the physical skeleton of a modern economy. Commodity intensity per unit of GDP declined structurally. By 2015, copper had halved from its 2011 peak. Iron ore had fallen 70%. A decade of underinvestment in new mine supply followed — rational at the individual level, catastrophic at the system level. The capital starvation of 2014–2020 planted the seeds of the next shortage. The pattern repeated.
Each cycle’s end created the conditions for the next beginning. Note how monetary regimes correlate with commodity cycle intensity.
| # | Name | Upswing | Duration | Primary Trigger | Monetary Context | Lead Commodity | How It Ended |
|---|---|---|---|---|---|---|---|
| 1 | War & Paper Money | 1793–1815 | 22 yr | Napoleonic Wars; gold suspension 1797 | Sterling off gold; inflationary | Grain, metals, shipping | Waterloo; return to gold 1821; long deflation |
| 2 | Gold Rushes & Railways | 1849–1873 | 24 yr | California/Australian gold; railways; US Civil War | Gold expansion; monetary easing | Iron, cotton, coal | German gold standard 1871; Panic of 1873 |
| 3 | Steam, Steel & WWI | c.1895–1920 | 25 yr | US/German industrialisation; WWI | Gold standard (constrained but held) | Steel, copper, oil | 1920–21 deflation; US prices −33% |
| 4 | Reflation & Reconstruction | 1933–1951 | 18 yr | FDR gold revaluation; WWII; Marshall Plan; Korea | Dollar devalued 69%; Bretton Woods 1944 | Aluminium, oil, steel | Peace; stable dollar; stockpile release |
| 5 | OPEC & Stagflation | 1968–1980 | 12 yr | Dollar collapse; Nixon Shock 1971; OPEC 1973/79 | Dollar off gold; weak; inflationary | Oil, gold ($35→$850), silver | Volcker rate shock; dollar surges; oil −73% by 1986 |
| 6 | China Supercycle | 2001–2011 | 10 yr | China WTO 2001; 800M people urbanising | Weak dollar 2002–2011 | Iron ore (+900%), copper (+500%) | China rebalancing; shale; supply glut; strong dollar |
| 7 | Security & Electrification | 2020–? | 6+ yr ongoing | Underinvestment exposed; grids; AI; rearmament; de-dollarization | Strong dollar — missing tailwind | Gold, copper, uranium | Unknown |
Upswing durations appear to be compressing (22, 24, 25, 18, 12, 10 years). One interpretation: faster capital markets and information flows compress the supply response cycle. With seven data points, treat this as a hypothesis. The key observation: every cycle with a weak-dollar backdrop (cycles 5 and 6) produced the largest commodity price moves. Cycle 7’s missing dollar tailwind is the most important risk factor to monitor.
Note that gold fell 47% from 1974 to 1976 — in the middle of the 1970s bull market, not at its end. Mid-cycle corrections inside supercycles can be as violent as final busts.
Approximate peak-to-trough falls. Understanding these drawdowns is as important as understanding the upswing — because they are the mechanism by which capital exits the sector, creating the next decade’s supply shortage and seeding the following cycle.
The Dollar Is Not a Spectator — It Shapes Every Commodity Cycle
The historical narrative above contains a recurring subplot that is easy to miss: every time you see a commodity boom, there is a monetary story underneath it. Sterling comes off gold and Napoleonic War commodity prices surge. US gold reserves are discovered and the money supply expands as railways consume iron. The dollar leaves gold and OPEC quadruples oil prices. China’s WTO entry coincides with a decade of dollar weakness. The currency is not a sideshow. It is the undertow that amplifies or suppresses every commodity cycle.
The mechanism is simple mathematics. Almost every globally traded commodity — crude oil, copper, iron ore, gold, soybeans — is priced in US dollars on international markets. When the dollar weakens, it takes more dollars to buy the same barrel of oil or tonne of copper. This raises the dollar price of the commodity even if nothing has changed in the physical supply-demand balance. For buyers outside the United States, a weaker dollar simultaneously makes commodities cheaper in their own currencies, stimulating demand. A weaker dollar is therefore a double tailwind: it raises the commodity price in dollar terms while simultaneously stimulating global demand. A stronger dollar is an equivalent headwind in both directions.
“The dollar is our currency, but it’s your problem.”
John Connally, US Treasury Secretary, to European finance ministers, 1971Four Monetary Eras and Their Commodity Consequences
The Gold Standard Era (pre-1914). Before World War I, most major industrial economies operated under the international gold standard: currencies were convertible to a fixed weight of gold, and therefore to each other at fixed exchange rates. Under this regime, commodity price moves were driven by genuine supply and demand dynamics — there was no currency debasement to amplify cycles. The commodity waves of 1793–1815 and 1849–1873 were “real” in the purest sense. The gold standard’s disciplinary power also meant that booms ended quickly when they met monetary constraint — governments could not sustain inflationary wars indefinitely without consequences. The system’s collapse in World War I opened the door to the modern era of currency-commodity co-dependency.
Bretton Woods and the Dollar’s First Reserve Era (1944–1971). The Bretton Woods agreement of July 1944 created a postwar monetary order with the dollar at its centre. Harry Dexter White won the argument against Keynes’s proposed “bancor” (a supranational reserve currency) by virtue of the US holding two-thirds of the world’s gold. Every currency was pegged to the dollar; the dollar was pegged to gold at $35 per ounce. Under this arrangement, commodity price inflation was broadly contained — the monetary anchor held. The system also generated what economist Barry Eichengreen called an “exorbitant privilege” for the United States: the ability to run deficits and have the rest of the world absorb them by accumulating dollars they could not easily convert to anything else.
The Petrodollar System and the Floating-Dollar Era (1971–2022). Nixon’s 1971 dollar-gold severance created an immediate problem: what would sustain global demand for dollars if they were no longer convertible to gold? The answer was geopolitical. The 1974 petrodollar agreement with Saudi Arabia — oil priced in dollars only, dollar surpluses recycled into US Treasuries — replaced the gold anchor with an oil anchor. The dollar remained indispensable not through convertibility but through necessity. Every nation that needed oil needed dollars. This arrangement sustained US financial hegemony for fifty years, but it created a structural dependency on Middle Eastern political stability and a structural requirement for the US to run current account deficits large enough to supply the world with dollars.
The De-dollarization Era (2022–present). The February 2022 freezing of approximately $300 billion in Russian central bank reserves — held in Western financial institutions and rendered inaccessible by US and allied sanctions — was a watershed event in monetary history. Not because the amount was large relative to total reserves. But because it demonstrated, with unprecedented clarity, that the world’s reserve asset could be weaponised. Nations across Asia, the Middle East, and the Global South began privately — then publicly — reassessing the wisdom of holding the majority of their reserves in US Treasuries.
The 2022 Russian reserve freeze triggered the most sustained structural shift in central bank reserve management since Bretton Woods ended.
World Gold Council data. 2025 estimate. The 2022–2025 average of 1,117 tonnes is 136% above the 2010–2021 average of 473 tonnes. This is not a temporary tactical allocation — it is a structural repricing of monetary trust.
The consequences are visible in data. Central banks purchased over 1,000 tonnes of gold annually in 2022, 2023, 2024, and 2025 — roughly double the long-run average. The dollar’s share of global reserves has declined from 73% in 2000 to approximately 58% today. China and Russia now settle roughly 90% of bilateral trade in rubles and yuan. The BIS-backed mBridge cross-border payment platform has reached minimum viable product status, processing transactions outside the SWIFT dollar clearing system. The proposed BRICS “Unit” — a reserve asset backed 40% by gold and 60% by national currencies — is being piloted in 2026.
None of this means the dollar is about to collapse. Sterling retained significant reserve-currency status for decades after Britain’s relative economic decline. But the direction of travel is unmistakable: the dollar is losing the reserve monopoly that sustained the petrodollar system. The structural consequence for commodity markets is positive: a secularly weakening dollar provides the same kind of monetary tailwind that amplified cycles 5 and 6. The complication in the current cycle is that the dollar has been strong since 2022 — rising as the Fed tightened aggressively — creating an unusual situation where the structural de-dollarization trend and the cyclical dollar strength are running in opposite directions simultaneously.
The dollar retains its dominant share, but the trend is clear and the February 2022 reserve freeze accelerated it.
IMF COFER data (quarterly). Gold (yellow) rising as share of total reserves. Euro (blue) broadly stable. Dollar declining. The pace of decline accelerated post-2022. Sources: IMF, World Gold Council, analyst estimates for 2026.
How to Tell a Real Supercycle from a Bull Market: The Six-Lens Test
Having established that supercycles exist as historical regimes (if not as predictable clocks), and having traced the seven waves of the past 230 years, we can now ask the practical question: how do you know when you are in one? What distinguishes a genuine multi-decade commodity price regime from a cyclical bull market, a speculative spike, or a geopolitical shock that will resolve in months?
Looking across all seven documented waves, the same six conditions keep appearing at their foundations. Not every cycle scores high on all six — but every genuine supercycle scores above a minimum threshold on at least four, and particularly on the first two.
The Threshold Rule
A supercycle regime is present when Shock and Scarcity both score at least 3 out of 5, and when four or more of the six lenses score 3 or higher. A cycle that fails this test may still be a strong bull market — but it lacks the structural foundations for a multi-decade regime. Use the interactive tool below to score any historical cycle or the current market.
Toggle historical cycles on to overlay them against the current assessment. Move the sliders to adjust scores and see how the verdict changes.
Historical scores are analyst judgement and are debatable. “Now” scores start at Research Desk assessment. Drag sliders to test sensitivity. A supercycle verdict requires Shock ≥3, Scarcity ≥3, and ≥4 of 6 lenses at 3+.
September 2026: Running Today’s Market Through the Framework
Wave 7 began at the April 2020 trough — when oil traded below zero, copper had fallen to $2.10, and gold stood near $1,500 after a brief pandemic panic. The ignition came in 2021 as supply chains fractured under reopening demand. The acceleration arrived in February 2022 when Russia’s invasion of Ukraine, the ensuing sanctions, and the freezing of Russian central bank reserves simultaneously delivered a physical commodity supply shock and a monetary trust crisis. Six years in, this is where we stand.
Iron ore’s lagging performance reflects China’s property sector stress — a key risk to the thesis. The sequence (precious metals first, then industrial metals and energy) is consistent with mid-cycle supercycle dynamics. Agricultural commodities have not yet broadly joined — if they do, Breadth scores 4–5 and the regime becomes unambiguous.
Scoring the Current Cycle Against the Six Lenses
Shock: 3/5. The demand engine is real but structurally different from 2001. China is no longer the single dominant buyer. In its place come four separate drivers: electricity grid expansion (copper, aluminium, silver), AI data centre infrastructure (copper, aluminium, uranium for power), NATO rearmament and Middle East conflict (steel, rare earths, energy), and monetary reserve diversification (gold, silver). Four smaller engines, each independently significant, together approach the scale of the China demand shock — but none is as singular or as concentrated. Score 3, not 5.
Scarcity: 5/5. The strongest lens. Mine supply is structurally constrained by a decade of capital underinvestment. Copper exploration spending fell 75% between 2012 and 2020. The IEA projects a 30% copper supply gap by 2035 — meaning demand will exceed supply by nearly a third even if every approved mine is built on schedule. Ore grades are declining at existing mines. China controls 70%+ of rare earth processing and has demonstrated willingness to use export controls. There is no quick fix: time to production is 10–16 years for copper, 8–15 for uranium. Score 5.
Money: 2/5. The most important weakness in the current cycle. The Federal Reserve raised rates to 3.75–4.00% on September 16, 2026 — its first hike in three years — in response to energy-driven inflation. The dollar index hit a 13-month high in summer 2026. Real yields are positive. Both large previous booms sat inside weak-dollar, negative-real-yield environments. This one does not. This is the single most important variable to watch: if the dollar turns and real yields fall, this score upgrades to 4, and the cycle’s intensity would increase dramatically. Score 2.
Statecraft: 5/5. Overwhelming. The US-Iran conflict is in its seventh month, disrupting Hormuz shipping. Russian reserve assets remain frozen. Critical mineral export controls between China and Western nations are reshaping supply chains. Central banks are persistent gold buyers. NATO’s rearmament push has become structural defence policy. Industrial policy — the US Chips Act, the EU Critical Raw Materials Act, India’s PLI schemes — is redirecting investment in ways that will shape commodity demand for a generation. Score 5.
Capital Cycle: 5/5. The bust that followed 2011–2016 starved mining and energy of investment for a decade. Junior mining stocks lost 80–95% of their value. Entire exploration teams left the industry. A generation of geologists and mining engineers chose other careers. The capital starvation was the most severe since the 1990s commodity bear market, and the recovery in capital spending has only begun. Score 5.
Breadth: 3/5. Metals and energy are broadly elevated. Precious metals are at or near all-time highs. Industrial metals have set records. Uranium has tripled from its lows. But agricultural commodities — after the Ukraine-driven spike of 2022–23 — have partially retraced, and food is not the defining commodity of this cycle’s early phase. The commodity complex is broad but not universally elevated. Score 3.
Verdict: Supercycle regime present. Shock ≥3 ✓, Scarcity ≥3 ✓, 5 of 6 lenses at ≥3 (threshold: 4) ✓. ⚠ The absent monetary tailwind (Money score: 2) is the cycle’s structural vulnerability. The two largest historical booms both had Money scoring 4–5. A Fed pivot or sustained dollar decline would upgrade this to 4, materially accelerating cycle intensity.
The Cycle Clock: Where Are We?
Supercycles pass through four recognisable phases. The current cycle started at the 2020 trough, ignited in 2021–22, and is now approximately six years in. The China supercycle at the same age (year 6 ≈ 2007) still had a final surge to new highs in 2008, a crash, a China-stimulus recovery, and then the 2011 peak. The analogy suggests we are in the acceleration phase — possibly midway through a cycle that has several years remaining. That analogy is illustrative, not a forecast.
Three Scenarios: What Happens Next, and What to Watch For
A framework is only useful if it generates specific conditional predictions. Based on the six-lens assessment, three paths are plausible from September 2026. They are ordered by current analyst probability weighting. They are not forecasts — they are conditional stories that tell you what to watch for and what to do when the signposts appear.
Probability estimates are analyst judgement. Signposts that shift probabilities are described in each scenario panel above. The Path 1 “Shakeout” reflects the Fed’s September 2026 rate hike, the dollar at a 13-month high, and the futures market already pricing oil lower by year-end. Path 2 requires the dollar to roll over. Path 3 requires China demand collapse and supply surprise simultaneously.
What Would Prove This View Wrong
Three specific developments would force a fundamental reassessment. A sustained rise in real yields and the dollar that persists after energy prices fade — showing the monetary headwind is structural, not cyclical. A Chinese hard economic landing that breaks the Shock lens at its foundations, removing the largest single-country buyer of industrial commodities from the global market for a decade. A supply flood — a surge of new mine approvals and a collapse in copper and uranium investment costs — that ends the Scarcity lens that is currently the strongest pillar of the entire thesis. Establish your thresholds before you need them.
Three Specific Trades — Entry, Stop, Target, and Sizing
The framework points to a cycle that is structurally up but cyclically choppy. A hawkish Fed, a strong dollar, and a near-term energy price spike layered on top of the structural bull case creates a specific environment: the right time to buy dips in structurally scarce metals, to fade the energy war premium, and to size for a multi-year hold rather than a quick trade. The three ideas below are anchored to prices as of September 23–24, 2026. Re-base to market before acting.
Trigger Rules — When to Act
Entry, Scale-Up and Exit Triggers
Add to gold and copper: if the DXY dollar index closes a week below 98 while real yields decline, add the second tranche in both positions to full size. The missing monetary tailwind has arrived.
Copper breakout add: a weekly close above 6.90 (above the all-time record) with rising exchange inventory drawdowns allows a small additional tranche, stop at 6.60.
De-risk trigger: if the US 10-year yield closes a week above 5.0%, or gold closes a week below 4,000, cut metals exposure by 50% and re-score all six lenses from scratch. The Failure scenario is gaining weight.
Exit oil short: a daily Brent close above 113.50 ends the trade unconditionally. Hormuz is the key binary risk for this idea.
Position-Size Calculator
Uses midpoint of entry zone. Standard contracts: gold 100 oz, copper 25,000 lb, Brent 1,000 bbl. Ignores fees, slippage, and margin. Risk 0.5–1% per idea; keep total open commodity risk under 2.5% of capital.
A Map of Phase-Based Positioning
| Cycle Phase | Typical Rewards | Typical Mistake | Signpost to Watch |
|---|---|---|---|
| Ignition | Gold, distressed commodity producers, energy at trough valuations | Dismissing the move as a temporary bounce; waiting for cheaper prices that never arrive | Commodity prices sustaining above 10% of 30-year real trend for 2+ years |
| Acceleration ← We Are Here | Metals & miners, commodity-export currencies (AUD, BRL, CLP), staged accumulation on pullbacks | Chasing spikes with leverage; selling the first 20% correction as “the end of the cycle” | Dollar turning; agricultural commodities joining; breadth score reaching 4+ |
| Overshoot | Systematic profit-taking, defined-risk options, rotating to quality balance sheets | Buying major acquisitions at cycle-peak prices — the Rio Tinto/Alcan pattern of 2007 | Record M&A; “this time is different” language in mainstream press; Money score 5/5 |
| Bust | Dollar, government bonds, patience, building watchlist for next ignition | Buying the first 30% drop; averaging down into structural oversupply | LME inventories rebuilding; new mine capex surging; demand growth decelerating |
Architects, Oracles, and Antagonists
Every supercycle has its theorists who saw it coming, its practitioners who built empires on it, and its policymakers whose decisions shaped its trajectory. These are the figures who made the history this article describes.
Frequently Asked Questions
Sources, Caveats and Methodology
Academic Sources
Kondratiev, N.D. (1925). The Major Economic Cycles. · Schumpeter, J.A. (1939). Business Cycles. McGraw-Hill. · Prebisch, R. (1950). The Economic Development of Latin America and its Principal Problems. ECLA. · Singer, H.W. (1950). “The Distribution of Gains between Investing and Borrowing Countries.” American Economic Review. · Grilli, E.R. and Yang, M.C. (1988). “Primary Commodity Prices, Manufactured Goods Prices, and the Terms of Trade.” World Bank Economic Review. · Cuddington, J.T. and Jerrett, D. (2008). “Super Cycles in Real Metals Prices?” IMF Staff Papers, 55(4). · Erten, B. and Ocampo, J.A. (2013). “Super Cycles of Commodity Prices since the Mid-Nineteenth Century.” World Development, 44. · Turchin, P. and Nefedov, S. (2007). Secular Cycles. Princeton. · Arrighi, G. (1994). The Long Twentieth Century. Verso. · Dalio, R. (2021). Principles for Dealing with the Changing World Order. · Eichengreen, B. (2011). Exorbitant Privilege. Oxford. · Rogers, J. (2004). Hot Commodities. Random House. · Heap, A. (2005). “China — The Engine of a Commodities Super Cycle.” Citigroup Smith Barney.
Market Data
All commodity prices, yields, and exchange rates as of September 23–24, 2026: Trading Economics, ICE, LME, CME Group, US Treasury. World Bank Commodity Markets Outlook (Q3 2026). IMF COFER database (reserve currency shares). World Gold Council (central bank gold purchases 2015–2025). IEA Critical Minerals Report (copper demand projections). Federal Reserve (FOMC September 16, 2026 decision).
Caveats
Supercycle dates, six-lens scores, and cycle classifications are analyst judgement — they differ materially between sources and should not be treated as settled fact. Historical price levels are rounded from standard references. The stylised commodity price chart is illustrative, not plotted data. Trade levels will be stale; re-anchor to current market prices before acting. Nothing in this article is personal financial advice. The framework is a tool for structured thinking, not a predictive algorithm.