Capital Street FX

us session weekly 7 12 sep 2026

Week Ahead, 7–12 September: August CPI and PPI Headline a Labor Day-Shortened Week Ahead of the Fed’s September Meeting | Technical Analysis – Us Session | 05-09-2026

September 5, 2026
Pawan Kshetri
Week Ahead, 7–12 September 2026: August CPI, PPI, and a Labor Day-Shortened Week Set the Stage for the Fed’s September Meeting | CSFX US Session Weekly
Week Ahead · US Market Preview
Week Ahead: Monday 7 – Saturday 12 September 2026 · Labor Day-Shortened US Trading Week

Week Ahead, 7–12 September: August CPI and PPI Headline a Labor Day-Shortened Week Ahead of the Fed’s September Meeting

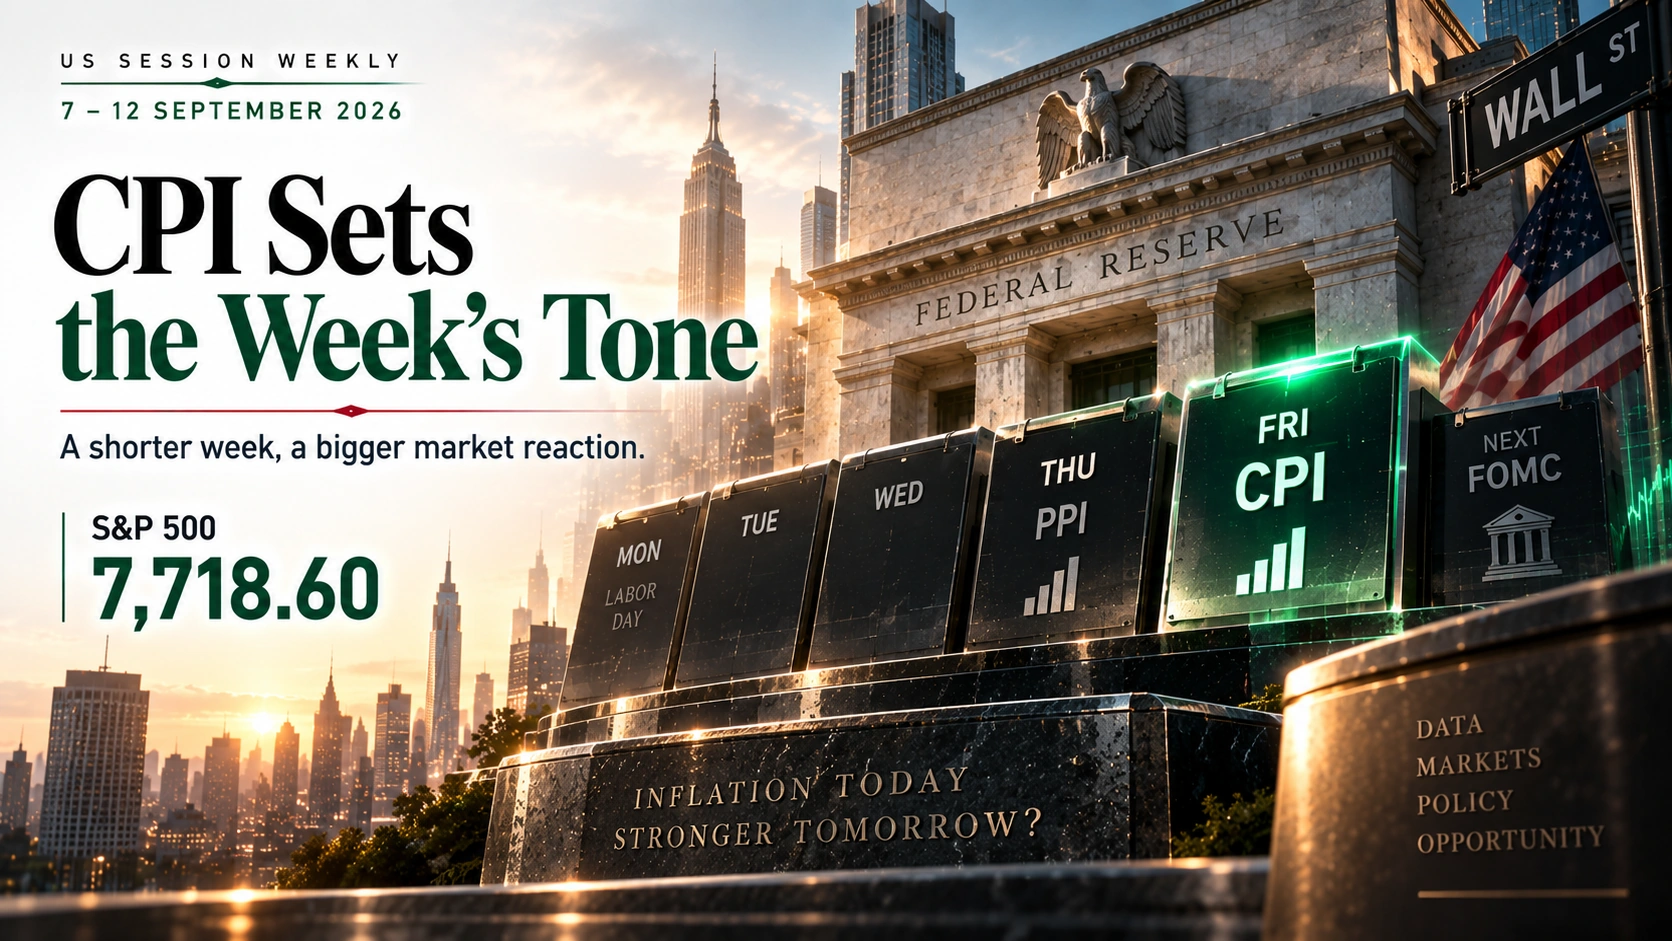
Mon 7 Sep: Markets Closed for Labor Day · Tue 8 Sep: NFIB & Consumer Credit · Thu 10 Sep: August PPI & Jobless Claims · Fri 11 Sep: August CPI & Prelim Michigan Sentiment
Entering the week: S&P 500 7,718.60 · US 10Y Yield 4.78% · Gold $4,430.33 · USD/CAD 1.3838 · USD/CHF 0.8092 · Natural Gas $2.94 · BTC/USD $79,650 · XRP $1.40. Full US session trade ideas and economic calendar for the week ahead
S&P 500· US 10Y· Gold· USD/CAD· USD/CHF· BTC / XRP
Last Week at a Glance · 31 August – 4 September 2026
S&P 500
7,718.60
▼ Pulled back from a mid-week record close near 7,748
The index touched a fresh high mid-week before Friday’s stronger-than-expected August jobs report reignited rate-hike concerns and triggered a broad pullback into the weekend.
US 10Y Yield
4.78%
▲ Firmed sharply after Friday’s jobs beat
Yields climbed toward the top of their recent range as futures markets repriced meaningfully higher odds of a Fed rate hike at the September meeting.
Gold (XAU/USD)
$4,430.33
■ Roughly flat on the week
Gold rebounded early in the week on dovish-leaning Fed commentary, then gave back gains as Friday’s jobs data revived hawkish repricing and a firmer dollar.
USD/CAD
1.3838
▼ Down modestly on the week
The pair eased for most of the week on broad dollar softness before stabilizing Friday as the jobs report offered some support to the greenback.
Bitcoin (BTC)
$79,650
▼ Slid from highs near $82,000 on Friday’s data
BTC broke above short-term resistance mid-week before Friday’s hot jobs print sent it briefly below $80,000, a sharp reversal tied to the sudden jump in rate-hike odds.
XRP
$1.40
▼ Cooled after peaking near $1.70 in late August
XRP is consolidating after its best August performance since 2021, pulling back from a strong summer rally as broader crypto risk appetite faded into Friday’s close.
The week of 31 August–4 September 2026 delivered a genuine tug-of-war between softening and strengthening labor-market signals. Early in the week, ADP’s private-payrolls report showed the softest hiring pace in months, and the ISM manufacturing PMI cooled to 54.6 from 55.6 — still in expansion territory, but a step down. Factory orders, by contrast, rebounded more than expected in July, and Friday’s official August jobs report from the Bureau of Labor Statistics landed materially stronger than economists had forecast, catching a market that had been leaning toward a softer labor picture off guard. The surprise strength sent Treasury yields sharply higher, pushed CME FedWatch-style pricing for a September Fed rate hike up notably from where it stood just a week earlier, and triggered a broad “sell the good news” reaction across risk assets — equities slipped from record levels, Bitcoin briefly broke below $80,000, and XRP extended its pullback from August’s rally highs. Gold’s path over the week captured the same whiplash: an early rebound on dovish-leaning Fed commentary gave way to a flat-to-lower finish once Friday’s data revived hawkish repricing. The set-up into the new week centers on a Labor Day market closure Monday, followed by a four-day stretch that delivers August producer prices Thursday and the week’s headline event — August consumer prices — on Friday, all unfolding inside the Fed’s official blackout period ahead of its 15–16 September policy meeting.
📋 This Week at a Glance · 7–12 September 2026
Key Events This Week: Markets Closed Monday, NFIB & Consumer Credit Tuesday, PPI & Jobless Claims Thursday, CPI & Michigan Sentiment Friday — 7–12 September
The week of 7–12 September 2026 opens with US stock and bond markets fully closed Monday in observance of Labor Day, compressing an already data-heavy week into four trading sessions. The S&P 500 enters the week at 7,718.60 after Friday’s pullback from record territory, with the 10-year Treasury yield at 4.78% following its sharpest weekly move higher in some time. Tuesday brings the NFIB Small Business Optimism Index for August and the July Consumer Credit report, offering an early read on small-business sentiment and household borrowing appetite. Wednesday is quiet on the data front. The week’s tone shifts decisively on Thursday, when the Bureau of Labor Statistics releases the Producer Price Index for August alongside the latest weekly jobless claims figures, followed by wholesale trade and existing home sales data — a dense session that sets up Friday’s headline event. Friday morning brings the Consumer Price Index for August, the release markets have circled all week as the clearest test yet of whether Friday’s blockbuster jobs report was a one-off or the start of a genuine reacceleration in the economy’s momentum. The preliminary University of Michigan Consumer Sentiment reading for September follows shortly after, rounding out the week. All of this unfolds inside the Federal Reserve’s official communications blackout period, which began Saturday, 6 September, and runs through the FOMC’s 15–16 September meeting — meaning no Fed officials will speak publicly to contextualize the data, leaving the numbers to move markets largely on their own.
🏛️ Markets Closed Monday — Labor Day 📊 August PPI Thursday 🎯 August CPI Friday — Week’s Key Event 🔇 Fed Blackout Period Ahead of 15-16 Sep FOMC 💼 Jobs-Data Whiplash Continues 🪙 BTC & XRP Cool From August Highs
What This Means for the Broader US Market

Friday’s CPI print is the single most important data point of the week for every US asset class: a hot core reading, arriving so soon after last week’s stronger-than-expected jobs report, would reinforce the market’s newly hawkish repricing of the Fed’s September decision and could extend the pullback in equities, Bitcoin, and XRP while pushing the dollar and Treasury yields higher. A cooler-than-expected CPI, on the other hand, would help offset last week’s hawkish jobs surprise and could support a relief rally back toward recent record highs in stocks, alongside renewed dollar softness. Thursday’s PPI report is the week’s dress rehearsal for CPI, and with the Fed in its pre-meeting blackout period, there will be no policymaker commentary to soften or amplify the market’s reaction — leaving the data to speak entirely for itself heading into the 15–16 September FOMC meeting.

Why Traders Choose CSFX
0.0 Pips Spreads
Trade 2000+ markets with tight, consistent pricing.
1:10000 Leverage
Trade all markets with high, flexible leverage power.
2000+ Instruments
Access all markets in one powerful trading account.
24/7 Live Support
Real help, any time you need it, day or night.
Section 1 · About the US Market This Week
The US session enters the week of 7 September with the S&P 500 at 7,718.60 after pulling back from record territory, Treasury yields firmer at 4.78% following Friday’s jobs-data surprise, and no FOMC meeting until 15–16 September. Gold holds at $4,430.33. USD/CAD trades at 1.3838. USD/CHF sits at 0.8092. Natural gas is at $2.94/MMBtu. Bitcoin trades near $79,650 after briefly slipping below $80,000, and XRP sits at $1.40, consolidating after its strongest August since 2021.

The S&P 500 heads into the week working off a sharp Friday reversal from record highs, after an unexpectedly strong August jobs report scrambled the market’s assumptions about the Fed’s next move. With Monday’s Labor Day closure compressing the week, the single biggest question for US equities is whether Friday’s Consumer Price Index confirms the labor market’s newfound strength is accompanied by resurgent inflation pressure, or whether it offers a cooler counterpoint that lets the “soft landing” narrative regain its footing.

The US 10-year Treasury yield at 4.78% has moved to the upper end of its recent range as futures markets meaningfully increased the probability they assign to a Fed rate hike at the 15–16 September meeting. With Fed officials barred from public commentary during the blackout period that began this past weekend, Thursday’s Producer Price Index and Friday’s Consumer Price Index are the only scheduled opportunities this week for the market to reassess that pricing before the meeting itself.

Elsewhere, Gold at $4,430.33 is caught between the same forces buffeting the rest of the market — a safe-haven bid on any growth-scare headlines, offset by the pull of higher real yields whenever hike odds firm. USD/CAD at 1.3838 and USD/CHF at 0.8092 both reflect a dollar that softened for most of last week before stabilizing on Friday’s data, leaving this week’s CPI print as the next major directional catalyst for both pairs. In crypto, Bitcoin near $79,650 and XRP at $1.40 are both digesting sharp reversals from their respective August highs, with the same CPI-driven repricing of Fed policy expectations the most likely trigger for their next meaningful move.

S&P 500
7,718.60
▼ Off record highs after Friday’s jobs-data reversal
Friday’s CPI print is the week’s key swing factor
US 10Y Yield
4.78%
▲ Near the top of its recent range
Fed in blackout period ahead of 15-16 Sep FOMC
Gold (XAU/USD)
$4,430.33
■ Roughly flat after a whipsaw week
Caught between safe-haven bid and firmer real yields
USD/CAD
1.3838
▼ Softer dollar tone into the new week
Friday’s CPI is the next major catalyst for the pair
USD/CHF
0.8092
▲ Franc softened slightly on the jobs beat
Watching for confirmation from CPI on hike odds
Natural Gas
$2.94
▲ Grinding higher into the shoulder season
Weekly EIA storage data due Thursday
Bitcoin (BTC)
$79,650
▼ Sharply reversed from ~$82,000 on Friday
A cool CPI print is the most likely recovery trigger
XRP
$1.40
▼ Consolidating after its best August since 2021
Broader risk appetite tied to this week’s CPI outcome
Section 2 · What Could Impact the US Market Next Week

Three Forces That Will Drive the US Session — 7 to 12 September 2026

The scheduled US-session catalysts that will set the direction across equities, rates, commodities, and digital assets for the week of 7–12 September 2026

📊
Force 1 · August CPI Tests Whether the Jobs Surprise Was a One-Off
Friday’s Consumer Price Index arrives just days after a stronger-than-expected August jobs report scrambled rate-hike odds. Cleveland Fed nowcasting points to headline inflation running near 3.4% year-over-year and core near 2.4%, but any upside surprise would compound last week’s hawkish repricing heading straight into the Fed’s 15–16 September meeting.
🔇
Force 2 · A Fed Blackout Period Leaves the Data to Speak Alone
The Fed’s pre-meeting communications blackout began Saturday, 6 September, and runs through the 15–16 September FOMC decision. With no policymakers available to contextualize Thursday’s PPI or Friday’s CPI, CSFX expects markets to react more mechanically — and potentially more sharply — to each release than they would with Fed commentary available to smooth the reaction.
🏛️
Force 3 · A Compressed, Labor Day-Shortened Trading Week
With US markets fully closed Monday for Labor Day, the week’s data and any position-adjusting flow are squeezed into four sessions. CSFX sees this compression as a factor that could amplify moves around Thursday’s PPI and Friday’s CPI, as desks catch up on positioning in a shorter window than usual.

Section 3 · Trade Setups

US Session Weekly Trade Ideas

Eight instrument-specific setups with entry, stop, and target levels for the week of 7–12 September 2026. All levels for reference only; not financial advice.

S&P 500
7,718.60
▼ Pulled back from record territory on Friday’s jobs data
■ NEUTRAL / BUY DIPS TO 7,600
Entry (Long)
7,600
Stop Loss
7,460
Take Profit
7,850

Thesis — Buy Confirmed Dips; Friday’s CPI Is the Week’s Pivot Point

The S&P 500’s Friday pullback from record highs reflects a genuine repricing of rate-hike risk rather than a change in the underlying earnings picture, and CSFX would treat a confirmed dip toward 7,600 as a buying opportunity contingent on Friday’s CPI print not compounding last week’s hawkish jobs surprise. A hot core CPI reading would likely extend the pullback and put the recent record close at 7,748 further out of reach in the near term.

S&P 500 weekly chart
Chart by TradingView
US 10-Year Treasury Yield
4.78%
▲ Firmed sharply after Friday’s jobs beat
▲ BULLISH YIELD / FADE DECLINES TOWARD 4.65%
Entry (Long Yield)
4.65%
Stop Loss
4.50%
Take Profit
4.95%

Thesis — CPI Confirmation of the Jobs Surprise Argues Against Chasing Yields Lower

With futures markets already leaning toward a meaningfully higher probability of a September rate hike after Friday’s jobs report, CSFX sees the risk-reward favoring a fade of any near-term yield pullback toward 4.65% ahead of Friday’s CPI. A hotter-than-expected core reading would likely push the 10-year back toward its recent highs near 4.95%, while a cooler print could unwind some of last week’s move.

US 10-Year Treasury Yield weekly chart
Chart by TradingView
Gold (XAU/USD)
$4,430.33
■ Roughly flat after a whipsaw week
▲ BULLISH / BUY DIPS TO $4,330
Entry (Long)
$4,330
Stop Loss
$4,180
Take Profit
$4,650

Thesis — Buy Dips Into CPI; A Cool Print Would Reignite the Rally

Gold’s flat finish last week masks a genuine tug-of-war between safe-haven demand and firmer real yields, and CSFX treats dips toward $4,330 as accumulation opportunities into Friday’s CPI. A softer-than-expected inflation print would likely unwind some of last week’s hawkish repricing and extend gold’s advance, while a hot print would keep the metal capped near recent levels.

Gold (XAU/USD) weekly chart
Chart by TradingView
USD/CAD
1.3838
▼ Softer dollar tone heading into the week
▲ BULLISH USD / BUY DIPS TO 1.3720
Entry (Long)
1.3720
Stop Loss
1.3620
Take Profit
1.3950

Thesis — Buy Dips; A Hot CPI Would Extend the Dollar’s Friday Bounce

USD/CAD’s modest pullback last week came alongside broad dollar softness that only partially reversed after Friday’s jobs beat. CSFX sees dips toward 1.3720 as a buying opportunity, contingent on Friday’s CPI reinforcing rather than unwinding the market’s newly hawkish Fed pricing.

USD/CAD weekly chart
Chart by TradingView
USD/CHF
0.8092
▲ Firmed modestly on Friday’s jobs data
▲ BULLISH / BUY DIPS TO $0.7980
Entry (Long)
0.7980
Stop Loss
0.7890
Take Profit
0.8200

Thesis — Buy Dips; Hawkish Repricing Argues for Dollar Resilience Against the Franc

USD/CHF’s bounce off recent lows tracks the broader firming in US rate expectations following Friday’s jobs report. CSFX favors buying dips toward 0.7980 into Friday’s CPI, with a soft inflation print — which would likely unwind some of the dollar’s recent gains — the main risk to this view.

USD/CHF weekly chart
Chart by TradingView
Natural Gas (Henry Hub)
$2.94
▲ Grinding higher as the forward curve steepens into winter
■ NEUTRAL / BUY DIPS TO $2.75
Entry (Long)
$2.75
Stop Loss
$2.55
Take Profit
$3.20

Thesis — Buy Dips; Forward Curve Steepening Points to Firmer Winter Pricing

Natural gas continues to firm as the market’s attention shifts from the tail end of the cooling season toward winter heating demand, with the forward curve steepening into the fourth quarter. CSFX would treat dips toward $2.75 as a buying opportunity, watching Thursday’s weekly EIA storage data for confirmation that the surplus to the five-year average continues to narrow.

Natural Gas weekly chart
Chart by TradingView
BTC/USD
$79,650
▼ Sharply reversed from ~$82,000 on Friday’s jobs data
■ NEUTRAL / BUY DIPS TO $75,000
Entry (Long)
$75,000
Stop Loss
$70,500
Take Profit
$86,000

Thesis — Buy Dips; A Cool CPI Print Is the Most Likely Recovery Trigger

Bitcoin’s sharp Friday reversal from breakout highs near $82,000 tracked the broader risk-off move sparked by stronger-than-expected jobs data. CSFX would treat dips toward $75,000 as a buying opportunity, with a softer-than-expected CPI print the most likely catalyst for BTC to reclaim its recent highs, while a hot inflation print risks a deeper retracement.

BTC/USD weekly chart
Chart by TradingView
XRP
$1.40
▼ Consolidating after its best August since 2021
■ NEUTRAL / BUY DIPS TO $1.25
Entry (Long)
$1.25
Stop Loss
$1.10
Take Profit
$1.65

Thesis — Buy Dips Within the Range; Broader Risk Appetite Is the Key Swing Factor

XRP is consolidating a strong summer advance, with last week’s pullback tied more to the broader crypto risk-off move than to any token-specific development. CSFX favors buying dips toward $1.25 within the current range, treating a cooler-than-expected CPI print — and the broader risk-appetite lift that would likely follow — as the more probable near-term catalyst than any XRP-specific news this week.

XRP/USD weekly chart
Chart by TradingView

Section 4 · Key Catalysts

What Could Move the US Market Next Week

The macro, labor-market, and policy catalysts CSFX is watching for the week of 7–12 September 2026

Inflation August CPI & Core CPI — Friday Morning
The single biggest catalyst of the week. Arriving just days after a stronger-than-expected August jobs report, Friday’s CPI print will be read as the clearest signal yet of whether the economy’s momentum is reaccelerating alongside inflation, or whether the labor-market surprise was an outlier. Cleveland Fed nowcasting points to headline inflation near 3.4% year-over-year.
Inflation August PPI & Core PPI — Thursday Morning
The Producer Price Index lands the morning before CPI and offers an early read on pipeline inflation pressures. A hot PPI print would raise the bar for a benign CPI outcome the following day, compounding the market’s already-hawkish post-jobs-report positioning.
Central Bank Federal Reserve Blackout Period Continues
The Fed’s pre-meeting communications blackout began Saturday, 6 September, and runs through the 15–16 September FOMC decision. With no policymakers available to speak publicly, CSFX expects this week’s data to drive market pricing with less of the moderating context that Fed commentary often provides.
Labor Market Aftershocks From Friday’s Stronger-Than-Expected Jobs Report
Last week’s official August jobs report landed well above forecasts, reversing a run of softer signals from ADP payrolls and the ISM manufacturing survey. CSFX is watching whether this week’s data corroborates the stronger headline number or reinforces the softer undertone seen elsewhere in recent labor-market indicators.
Housing Existing Home Sales — Thursday
August existing home sales, released alongside PPI and jobless claims on Thursday, offer a read on whether the housing market is holding up under a 10-year yield sitting near 4.78%, ahead of what could be an even higher-rate backdrop if the Fed leans hawkish on 15–16 September.
Crypto BTC & XRP Await a CPI-Driven Risk-Appetite Signal
Both Bitcoin and XRP reversed sharply from their respective highs on Friday’s jobs-data surprise, leaving both without a token-specific catalyst this week. CSFX sees Friday’s CPI print as the most likely trigger for either a renewed risk-on move or a deeper pullback across both assets.

Section 5 · Economic Calendar

US Session Economic Calendar — 7–12 September 2026

Key scheduled US releases for the week, with times in US Eastern Time (ET)

Day Time (ET) Release Impact Period CSFX View
Monday, 7 September
MonAll Day US Stock & Bond Markets Closed — Labor Day CLOSEDN/A No trading and no scheduled economic releases; the week’s data compresses into four sessions starting Tuesday.
Tuesday, 8 September
Tue6:00 AM NFIB Small Business Optimism Index MEDAugust A read on small-business sentiment that will be weighed against Friday’s jobs surprise for a fuller picture of the labor market’s underlying health.
Tue3:00 PM Consumer Credit LOWJuly A gauge of household borrowing appetite, offering an early data point on consumer financial health heading into Friday’s CPI.
Wednesday, 9 September
Wed— No Noteworthy Economic Reports Scheduled LOWN/A A quiet mid-week session ahead of Thursday’s dense data slate; Fed officials remain silent under the pre-meeting blackout.
Thursday, 10 September
Thu8:30 AM Weekly Jobless Claims HIGHWeek Ending 5 Sep The latest weekly labor-market pulse check, read directly against last week’s stronger-than-expected August jobs report for signs of confirmation or divergence.
Thu8:30 AM Producer Price Index (PPI) & Core PPI HIGHAugust The week’s dress rehearsal for Friday’s CPI. A hot pipeline-inflation print would raise the bar for a benign consumer-price outcome the next morning.
Thu10:00 AM Wholesale Trade LOWJuly A secondary read on inventory and sales trends across the wholesale sector, rounding out the week’s broader activity picture.
Thu10:00 AM Existing Home Sales MEDAugust A housing-market gauge that will be read against a 10-year yield sitting near 4.78%, for signs of whether elevated borrowing costs are weighing on transaction volumes.
Friday, 11 September
Fri8:30 AM Consumer Price Index (CPI) & Core CPI HIGHAugust The week’s single biggest catalyst. Markets will parse the print closely for confirmation, or contradiction, of last week’s hawkish jobs-data surprise ahead of the 15–16 September FOMC meeting.
Fri10:00 AM University of Michigan Consumer Sentiment (Preliminary) MEDSeptember The first read on September consumer sentiment, offering an early signal on how households are processing the recent run of labor-market and inflation data.
Fri2:00 PM Treasury Balance LOWAugust A routine fiscal-accounts release that closes out the week’s calendar with limited direct market impact.

Section 6 · FAQ

US Session — Trader Questions Answered

Key questions from CSFX clients ahead of August CPI and the Fed’s 15–16 September meeting

Why is Friday’s CPI report such a big deal this week?
Because it arrives just days after a stronger-than-expected August jobs report scrambled the market’s expectations for the Fed’s September decision. Friday’s inflation data is the clearest opportunity this week to see whether that labor-market strength is being accompanied by resurgent price pressures, which would reinforce the market’s newly hawkish positioning, or whether inflation is cooling in a way that offsets the jobs surprise.
Why did rate expectations shift so much after last week’s jobs report?
The official August jobs report came in well above economists’ forecasts, a sharp contrast to the softer signals seen earlier in the week from ADP’s private-payrolls data and the ISM manufacturing survey. That surprise strength led futures markets to meaningfully raise the odds they assign to a Fed rate hike at the September meeting, triggering higher Treasury yields and a broad pullback across equities and crypto.
What is the Fed’s blackout period, and why does it matter this week?
It’s the period immediately before a Federal Open Market Committee meeting during which Fed officials refrain from public speeches or commentary on monetary policy. This year’s blackout began Saturday, 6 September, and runs through the 15–16 September meeting, meaning that no policymaker will be available to contextualize this week’s PPI or CPI releases — leaving the data to move markets without any moderating commentary from the Fed itself.
Why are US markets closed on Monday?
Monday, 7 September 2026 is Labor Day, a full US stock and bond market holiday observed by the NYSE, Nasdaq, and the broader Treasury market. No equity or bond trading takes place, and the week’s economic calendar is compressed into the four sessions from Tuesday through Friday.
What is CSFX’s single highest-conviction trade for the week of 7–12 September?
CSFX’s highest-conviction setup is buying confirmed S&P 500 dips toward 7,600, contingent on Friday’s CPI not compounding last week’s hawkish jobs surprise. The second-highest-conviction idea is buying gold dips toward $4,330, given the tug-of-war between safe-haven demand and firmer real yields that is likely to persist until the inflation picture is clearer.
CSFX View · Week of 7 September 2026

CSFX View: August CPI Is the Week’s Deciding Vote on the Fed’s September Path


The week of 7–12 September 2026 hands the US session a compressed, four-day trading week that nonetheless carries outsized weight: August’s Producer Price Index on Thursday and Consumer Price Index on Friday will be read as the market’s clearest chance to confirm or push back against last week’s stronger-than-expected jobs report, all unfolding while the Federal Reserve sits in its official blackout period ahead of the 15–16 September meeting. The S&P 500 at 7,718.60 enters the week off a Friday pullback from record territory, the US 10-year Treasury yield at 4.78% sits near the top of its recent range, and gold at $4,430.33 is holding roughly flat after a week that saw it whipsaw between safe-haven demand and firmer real yields. USD/CAD at 1.3838 and USD/CHF at 0.8092 both reflect a dollar that softened for most of last week before stabilizing Friday, while Bitcoin near $79,650 and XRP at $1.40 are both digesting sharp reversals from their respective August highs.

CSFX’s framework for the week centers on a single pivot point: Friday’s CPI print, read against the backdrop of last week’s jobs-data surprise. In equities, CSFX favors buying confirmed S&P 500 dips toward 7,600, contingent on CPI not compounding the market’s newly hawkish Fed pricing. In rates, the sharp move higher in yields argues against chasing a pullback toward 4.65% ahead of Friday’s data. In FX, both USD/CAD and USD/CHF favor buying dips given the dollar’s post-jobs-report resilience, though a cool CPI print is the key risk to both views. In commodities, gold’s dips remain buyable given the persistent safe-haven bid, while natural gas continues to firm as the market’s focus shifts toward winter heating demand. In crypto, both BTC and XRP are buy-the-dip trades within their current ranges, with a cooler-than-expected CPI print the most likely trigger for a renewed risk-on move across both assets.

CSFX’s highest-conviction setups for the week are: buying confirmed S&P 500 dips toward 7,600 around Friday’s CPI, and buying gold dips toward $4,330 into the same release. USD/CAD is a buy-the-dip trade toward 1.3720 as dollar resilience persists; the US 10-year yield is a fade of pullbacks toward 4.95% if CPI runs hot; USD/CHF favors dips toward 0.7980; BTC is a buy on dips to $75,000 pending a cooler CPI outcome; and XRP is a buy on dips to $1.25 within its current range. CSFX will issue intra-week alerts if Thursday’s PPI or Friday’s CPI surprise materially in either direction, or if any early signal emerges on the Fed’s likely posture heading into the 15–16 September meeting.