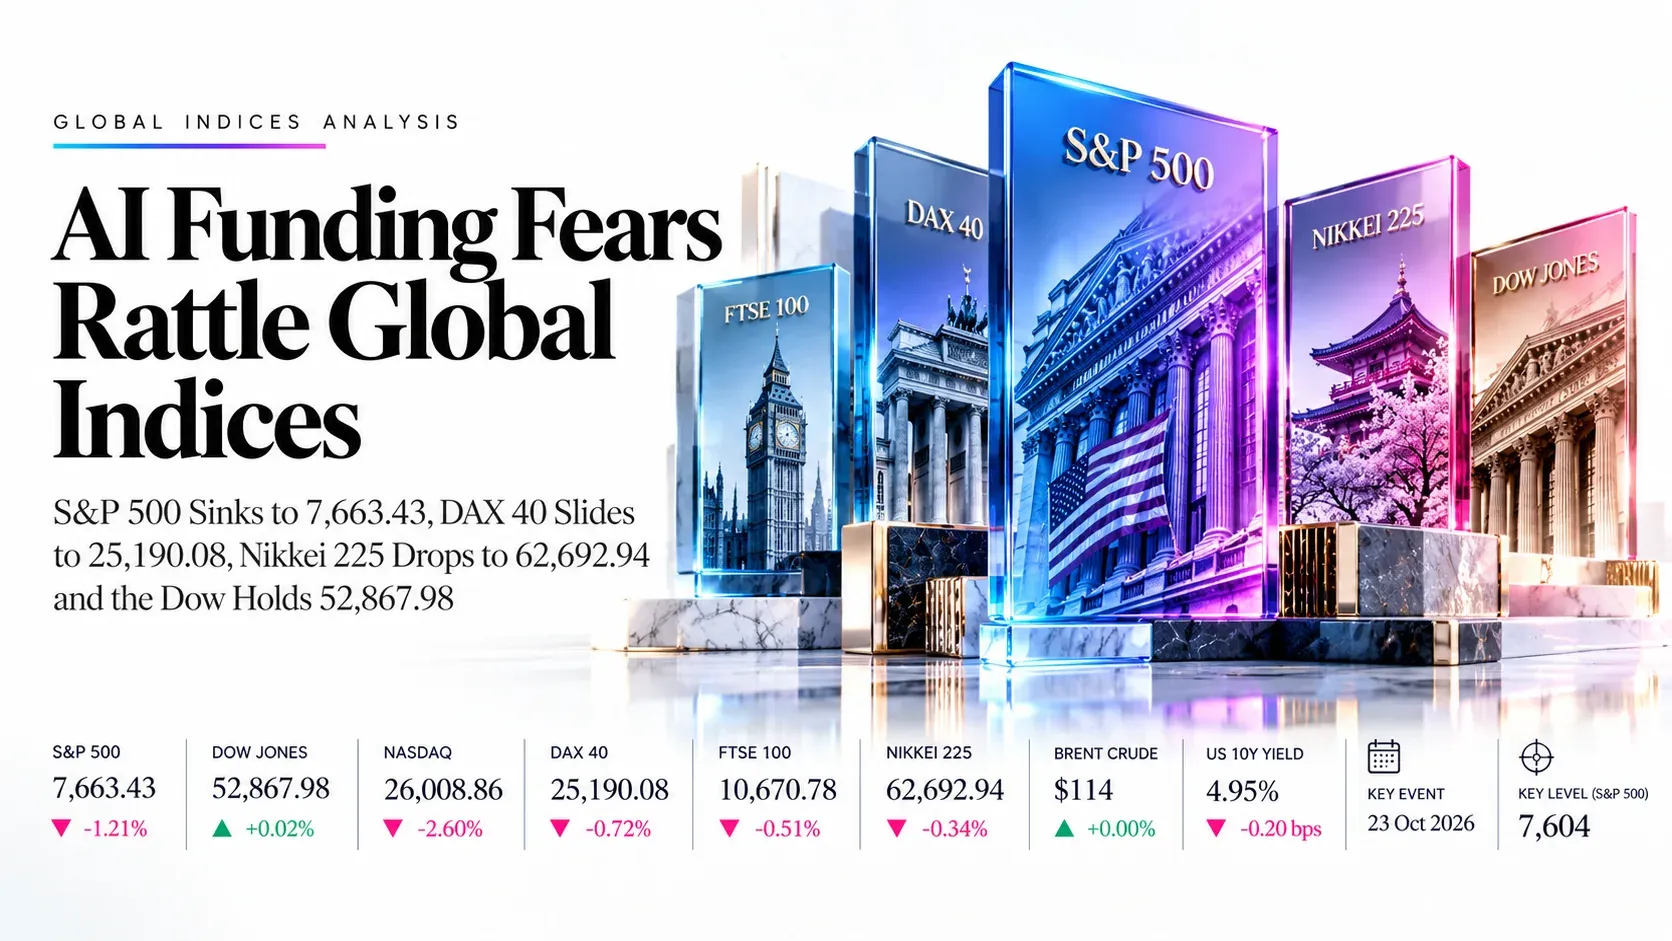
AI Sell-Off Rattles Global Indices: S&P 500 Sinks to 7,663.43, DAX 40 Slides to 25,190.08, Nikkei 225 Drops to 62,692.94 and the Dow Holds 52,867.98 | Technical Analysis – Index Report | 23 Oct 2026
Indices Today | Friday 23 October 2026
AI Sell-Off Rattles Global Indices: S&P 500 Sinks to 7,663.43, DAX 40 Slides to 25,190.08, Nikkei 225 Drops to 62,692.94 and the Dow Holds 52,867.98
Market Overview
Equities are on the defensive after an AI-funding sell-off hit Wall Street on Thursday. At about 09:25 GMT the FTSE 100 was 10,670.78 (−0.51%) and the DAX 40 25,190.08 (−0.72%), the Nikkei 225 closed Tokyo at 62,692.94 (−0.34%) after falling as much as 2.3%, and the Thursday US closes were S&P 500 7,663.43 (−1.21%), Dow Jones 52,867.98 (+0.02%) and Nasdaq 26,008.86 (−2.60%), its worst day since June. Meta fell almost 7%, the Philadelphia Semiconductor Index lost 6.7%, the 10-year Treasury yield dropped about 20 basis points to near 4.95% and Brent hit a five-month high near $114 after Houthi attacks on Saudi energy sites. We read the session as a tech-led risk-off with rotation into defensives, so the Dow holds up while the S&P 500, Nikkei and DAX stay heavy; US flash PMIs at 13:45 GMT and the Fed, Microsoft, Alphabet, Amazon, ECB and Bank of Japan next week are the next tests.
Key highlights
- FTSE 100: Price is 10,670.78 under the 10,705 average and above the 10,653 and 10,635 averages; UK retail sales fell 0.4% in September.
- DAX 40: Price is 25,190.08 under all three averages and the channel roof; euro-zone composite PMI fell to 51.9.
- Dow Jones: Price is 52,867.98 above all three averages after a breakout; 52,358 is the key floor.
- S&P 500: Price is 7,663.43 under the 7,733 and 7,703 averages with RSI 45.18; 7,604 is the next support.
- Nikkei 225: Price is 62,692.94 under a broken triangle floor with RSI 35.95; the 61,462 low held today.
What’s Moving Indices Today
AI funding fears hand the Nasdaq its worst day since June
The Nasdaq Composite fell 2.60% to 26,008.86 and the Philadelphia Semiconductor Index lost 6.7% on Thursday. Meta dropped almost 7% after its first cash outflow in over a decade and a plan to issue non-voting shares, Amazon fell 4.57%, Nvidia 4.40% and Tesla 3.08% after cutting its 2026 capital spending forecast. The S&P 500 closed at 7,663.43 and the VIX rose 14% to 19.03.
Rotation into defensives keeps the Dow flat while the S&P 500 falls
The Dow closed up 0.02% at 52,867.98 as money moved out of growth tech rather than out of stocks. Procter & Gamble rose on better-than-expected results and Lockheed Martin gained about 7%, and the 10-year yield fell almost 20 basis points to about 4.95%, its biggest one-day drop since March 2023. Dow futures were about 0.4% lower this morning.
Nikkei falls as much as 2.3%, then pares losses to close at 62,692.94
Tokyo recovered from a low of 61,462.61 as selling in tech and AI stocks eased, but the index lost about 4% on the week, its second weekly decline, with Hitachi, Disco and Nintendo under pressure. Japan’s core inflation rose above the Bank of Japan’s 2% target, which cements hike expectations, and reports that the US and Israel may resume strikes on Iran after the 3 November US elections added to caution.
Euro-zone PMIs miss and French debt stress keeps European stocks heavy
The euro-zone composite PMI fell to 51.9 from 53.1 against 52.7 expected, with services at 51.7 and manufacturing at 52.4, and the German composite slipped to 52.8 against 53.3 expected even as German manufacturing rose to 54.2. The DAX lost 1.07% on Thursday and the Euro Stoxx 50 fell 1.96%; Kering is down about 12% today, Volkswagen workers threaten strikes and French debt risk premiums are at euro-zone crisis levels.
UK retail sales miss and Barclays cuts jobs, while oil supports energy stocks
UK retail sales volumes fell 0.4% in September against a 0.1% fall expected, and 0.7% excluding fuel. Barclays plans to cut about 5,000 jobs, banks and miners fell on Thursday, and UK consumer confidence tumbled ahead of the budget; BP and Shell rose with Brent near $114, and UK inflation at 3.5% keeps a Bank of England hike on the table for November.
Brent holds a five-month high and the Fed meets on 28 October
Houthi attacks on a Saudi Aramco field and Dammam airport pushed Brent to about $114 and WTI above $100, and gold is offered just above $4,000. Markets price roughly one more quarter-point Fed hike before year-end, so higher energy prices and the 28 October decision, with Microsoft and Alphabet earnings the same day, are the main risks next week.
Key Drivers Ahead
Six events that set direction for the FTSE 100, DAX 40, Dow Jones, S&P 500 and Nikkei 225. All times are GMT.
- Euro-zone flash PMI
- 51.9
- Fri 23 Oct, 08:00 GMT (out)
- Composite missed 52.7; DAX 40 and FTSE 100
- US flash PMIs
- 13:45
- Fri 23 Oct, 13:45 GMT
- S&P Global manufacturing and services; Dow and S&P 500
- US Michigan sentiment
- 14:00
- Fri 23 Oct, 14:00 GMT
- Consumer sentiment and inflation expectations, 30 minutes after the US open
- Fed, Microsoft and Alphabet
- 28 Oct
- Wed 28 Oct, 18:00 GMT
- Fed decision; earnings after the US close test AI spending
- ECB, US GDP and PCE, Amazon
- 29 Oct
- Thu 29 Oct, 12:30 and 13:15 GMT
- US Q3 GDP and September PCE at 12:30; ECB decision at 13:15
- Bank of Japan
- 30 Oct
- Fri 30 Oct, Tokyo session
- Core inflation above 2% keeps a hike in view; Nikkei 225
Swipe the strip to see every driver.
Trade Setups for Today
Ranked in the order FTSE 100, DAX 40, Dow Jones, S&P 500 and Nikkei 225, valid for today’s session and the Monday open. A 1-hour close beyond the stop cancels the idea.
| Instrument | Direction | Entry | Stop | Target 1 | Target 2 | Reward:risk | Conviction |
|---|---|---|---|---|---|---|---|
| FTSE 100 | Long | 10,640 | 10,560 | 10,760 | 10,880 | 1.5 / 3.0 | Low |
| DAX 40 | Short | 25,280 | 25,450 | 24,950 | 24,750 | 1.9 / 3.1 | Medium |
| Dow Jones | Long | 52,550 | 52,250 | 53,250 | 53,900 | 2.3 / 4.5 | Medium |
| S&P 500 | Short | 7,720 | 7,785 | 7,604 | 7,500 | 1.8 / 3.4 | Medium |
| Nikkei 225 | Short | 63,500 | 64,400 | 61,460 | 60,400 | 2.3 / 3.4 | Medium |
Reward:risk is the distance from entry to each target divided by the distance from entry to the stop. Prices are read at about 09:22 to 09:24 GMT on 23 October from TradingView daily charts; every entry sits away from the current price and needs a bounce or a pullback to trigger. The S&P 500 and Dow Jones quotes are Thursday’s closes, so their entries can gap at the US open. Levels are conditional technical references, not recommendations.
Risk Scenario Analysis
US flash PMIs, Brent and Treasury yields are the swing factors today, with the Fed, big-tech earnings, the ECB and the Bank of Japan the main events next week.
Risk-off deepens: tech sells off again, Brent holds near $114 and PMIs slow
Another AI-led leg lower, French stress or soft US PMIs would pressure the Nikkei, DAX and S&P 500 most, while the Dow and FTSE 100 hold up better.
- FTSE 10010,635, then 10,450
- DAX 4024,950, then 24,750
- Dow Jones52,358, then 51,707
- S&P 5007,604, then 7,500
- Nikkei 22561,460, then 60,400
Risk-on rebound: tech steadies, PMIs hold up and oil eases
Stable chip stocks, firm US PMIs and a pullback in Brent would let the indices recover part of Thursday’s losses and push yields back up.
- FTSE 10010,705, then 10,880
- DAX 4025,447, then 25,621
- Dow Jones53,250, then 53,900
- S&P 5007,733, then 7,757
- Nikkei 22564,000, then 66,173
FTSE 100 Index | UK 100, FTSE feed
FTSE 100 Analysis: Price Slips Back to a Cluster of Averages Under the Flat Roof of a Rising Triangle
10,670.78 −54.25 (−0.51%) at about 09:22 GMT Day range 10,669.18–10,748.42
Outlook: Bias is neutral to lower while 10,705 caps rallies. UK retail sales fell 0.4% in September against a 0.1% fall expected, Barclays plans 5,000 job cuts and banks and miners are weak, while Brent near $114 supports BP and Shell and limits the damage.
Key levels
- Support 2
- 10,450
- Support 1
- 10,635
- Resistance 1
- 10,705
- Resistance 2
- 10,880
- Price (10,670.78) is under the 10,705 average and above the 10,653 and 10,635 averages; the rising line from the March low near 10,450 and the October low near 10,360 are the deeper supports.
- RSI 49.12 is under its signal line at 50.85 and flat near the midline; a daily close above 10,880 would aim at the 11,000 roof, while a close under 10,560 would put the rising line at risk.
Setup: Long at 10,640, stop 10,560, targets 10,760 and 10,880. Reward:risk 1.5 / 3.0, low conviction.
DAX 40 Index | DAX, XETR feed
DAX 40 Analysis: Price Sits on the Low of the Day Under All Three Averages Inside a Falling Channel
25,190.08 −181.67 (−0.72%) at about 09:23 GMT Day range 25,188.88–25,329.32
Outlook: Bias is lower while 25,447 caps rallies. The euro-zone composite PMI fell to 51.9 against 52.7 expected, German composite PMI slipped to 52.8, Kering lost about 12% and French debt stress is weighing on the region after Thursday’s 1.07% fall.
Key levels
- Support 2
- 24,750
- Support 1
- 24,950
- Resistance 1
- 25,276
- Resistance 2
- 25,447
- Price (25,190.08) is under the 25,276, 25,447 and 25,621 averages and the channel roof; the October low near 24,750 is the first major support and the channel floor near 24,400 the next.
- RSI 45.85 is under its signal line at 47.51 and tilted down; a daily close above 25,621 would break the channel roof and cancel the bearish case.
Setup: Short at 25,280, stop 25,450, targets 24,950 and 24,750. Reward:risk 1.9 / 3.1, medium conviction.
Dow Jones Industrial Average | DJIA, TVC feed
Dow Jones Analysis: Price Breaks Above a Falling Triangle Line and Holds Above All Three Averages
52,867.98 +11.89 (+0.02%) at the Thursday 22 Oct close Day range 52,508.38–52,927.88
Outlook: Bias is higher while 52,358 holds. Money rotated out of AI-heavy tech into defensives on Thursday, so the Dow ended flat while the S&P 500 fell 1.21% and the Nasdaq 2.60%; Procter & Gamble and Lockheed Martin rose on results.
Key levels
- Support 2
- 51,707
- Support 1
- 52,358
- Resistance 1
- 53,250
- Resistance 2
- 53,900
- Price (52,867.98) is above the 52,358, 52,297 and 51,707 averages; the rising line from the March low near 50,800 and the October low near 50,500 are far below, so the 52,300 zone is the first support.
- RSI 62.76 is above its signal line at 50.43, so momentum favours buyers; a daily close above 53,250 would aim at the 53,900 September high, but a close back under 52,358 would put the breakout in doubt.
Setup: Long at 52,550, stop 52,250, targets 53,250 and 53,900. Reward:risk 2.3 / 4.5, medium conviction.
S&P 500 Index | SPX, SP feed
S&P 500 Analysis: Price Falls Under Two Averages at the Middle of a Rising Channel After a 1.21% Drop
7,663.43 −93.74 (−1.21%) at the Thursday 22 Oct close Day range 7,637.36–7,702.94
Outlook: Bias is lower while 7,733 caps rallies. Meta fell almost 7% on its first cash outflow in over a decade, the Philadelphia Semiconductor Index lost 6.7% and the 10-year Treasury yield fell about 20 basis points to near 4.95%; futures are about flat this morning.
Key levels
- Support 2
- 7,500
- Support 1
- 7,604
- Resistance 1
- 7,703
- Resistance 2
- 7,733
- Price (7,663.43) is under the 7,733 and 7,703 averages and above the 7,604 average; a daily close under 7,604 would aim at the 7,500 September low and the channel floor.
- RSI 45.18 is under its signal line at 54.10 and has turned down from neutral; a close back above 7,757, Wednesday’s close, would take the pressure off.
Setup: Short at 7,720, stop 7,785, targets 7,604 and 7,500. Reward:risk 1.8 / 3.4, medium conviction.
Nikkei 225 Index | NI225, TVC feed
Nikkei 225 Analysis: Price Breaks the Floor of a Symmetrical Triangle and Rebounds From 61,462 Under All Three Averages
62,692.94 −214.90 (−0.34%) at the Tokyo close, 06:00 GMT Day range 61,462.61–62,786.89
Outlook: Bias is lower while 64,000 caps rallies. The index fell as much as 2.3% in Tokyo before recovering to a 0.34% loss, ended the week about 4% lower, and Japan’s core inflation above the Bank of Japan’s 2% target keeps a rate hike in view.
Key levels
- Support 2
- 60,400
- Support 1
- 61,460
- Resistance 1
- 64,000
- Resistance 2
- 66,173
- Price (62,692.94) is under the 66,173, 66,669 and 66,748 averages and the broken triangle floor; a daily close under 61,460 would aim at the 60,400 August low.
- RSI 35.95 is under its signal line at 50.54 and close to oversold, so sharp bounces are likely; a close back above 66,173 would put the breakdown in doubt.
Setup: Short at 63,500, stop 64,400, targets 61,460 and 60,400. Reward:risk 2.3 / 3.4, medium conviction.
Conclusion
Tech-led risk aversion is hitting the S&P 500, Nikkei 225 and DAX 40 harder than the Dow Jones and FTSE 100, so we prefer selling DAX 40 bounces under 25,450, S&P 500 bounces under 7,785 and Nikkei 225 bounces under 64,400, and buying Dow Jones pullbacks to 52,550 while 52,250 holds. The FTSE 100 long from 10,640 is a lower-conviction trade because the UK retail sales miss and bank weakness offset the energy support. The nearest risks are the US flash PMIs at 13:45 GMT and Michigan sentiment at 14:00 GMT, then the Fed and big-tech earnings on 28 October, the ECB and Amazon on 29 October and the Bank of Japan on 30 October. A daily S&P 500 close under 7,604 would confirm the break of the channel’s middle.
Trade FTSE 100, DAX 40, Dow Jones, S&P 500 and Nikkei 225 with Capital Street FX.
Frequently Asked Questions
Why did the S&P 500 fall while the Dow Jones was flat?
The sell-off was concentrated in AI and chip stocks: the Nasdaq fell 2.60% and the Philadelphia Semiconductor Index 6.7%, with Meta down almost 7%. The Dow has few of those names and gained from Procter & Gamble and Lockheed Martin, so it closed up 0.02% at 52,867.98 while the S&P 500 lost 1.21% to 7,663.43.
Why is the Nikkei 225 down about 4% this week?
Tech and AI shares led the fall, with the index dropping as much as 2.3% today before closing 0.34% lower at 62,692.94. Price is under a broken triangle floor and all three averages; a close under 61,460 would aim at 60,400, while Japanese core inflation above 2% keeps a Bank of Japan hike in view.
Why are the DAX 40 and FTSE 100 lower today?
Euro-zone and German PMIs missed forecasts, French debt stress and a 12% fall in Kering weigh on the DAX at 25,190.08, and UK retail sales fell 0.4% in September against a 0.1% fall expected. The FTSE 100 at 10,670.78 is cushioned by BP and Shell with Brent near $114 but pressured by Barclays and the miners.
How do the Fed, ECB and Bank of Japan decisions next week affect these indices?
The Fed decides at 18:00 GMT on 28 October, with Microsoft and Alphabet reporting that day, the ECB decides on 29 October at 13:15 GMT and the Bank of Japan meets on 30 October. A hawkish Fed or weak AI-spending guidance would hit the S&P 500 and Nikkei, while a Bank of Japan hike signal would add pressure on Japanese stocks.