Week Ahead, 7–12 September: ECB Rate Decision Frames the European Session as German Data and UK Growth Numbers Round Out the Week | Technical Analysis – European Session | 05-09-2026
Week Ahead, 7–12 September: ECB Rate Decision Frames the European Session as German Data and UK Growth Numbers Round Out the Week
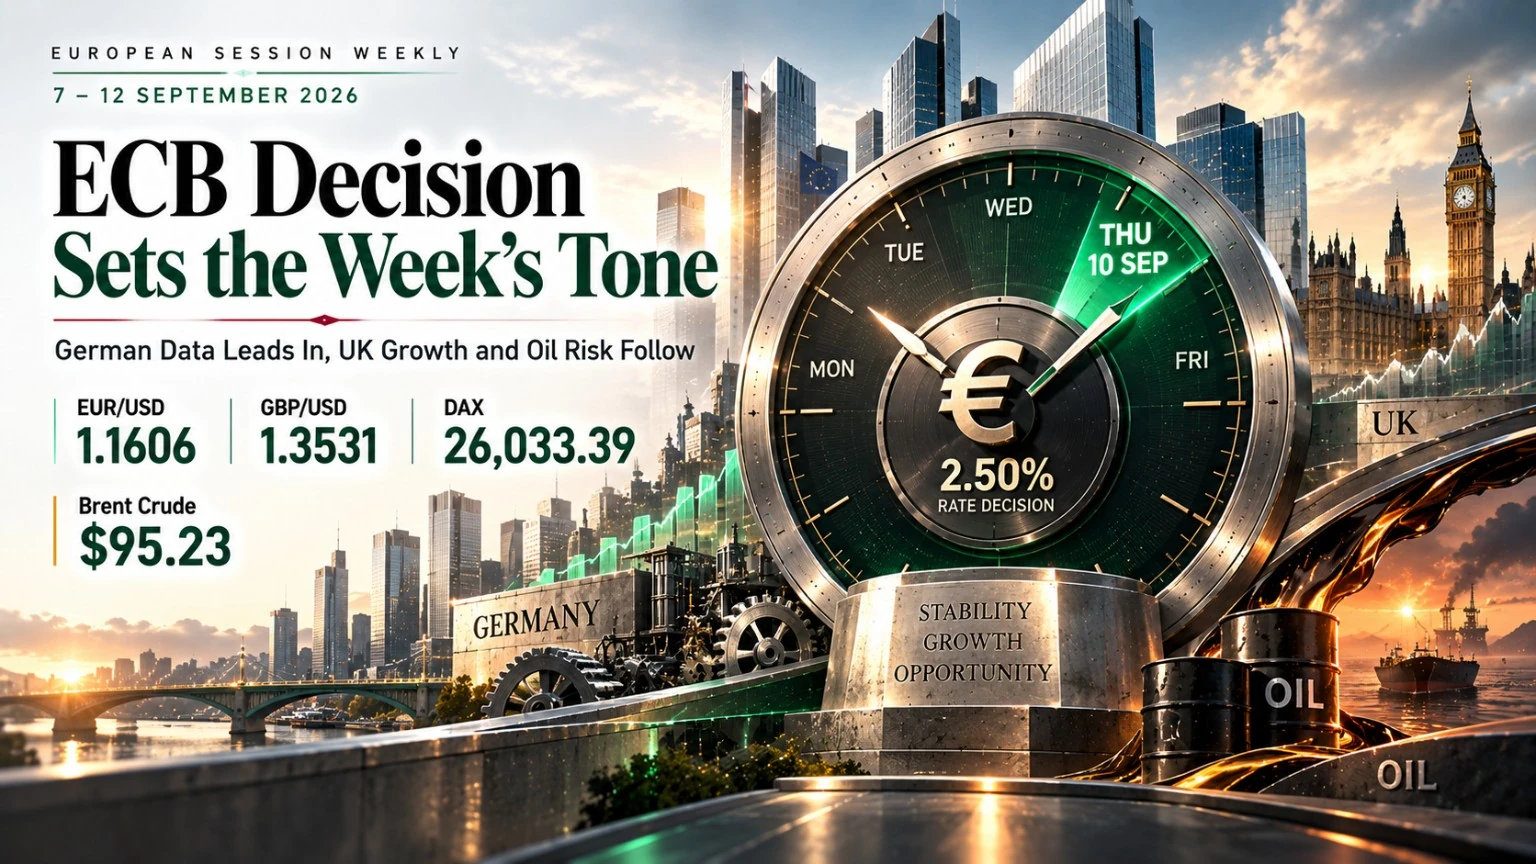
German Industrial Production Mon 7 Sep · German Trade Balance Tue 8 Sep · ECB Rate Decision Thu 10 Sep · UK GDP & Production Data Fri 11 Sep · Full European session economic calendar for week of 7–12 September 2026
1. EUR/USD — can the euro hold its ground into the ECB’s second hike of the cycle? EUR/USD at 1.1606 enters the week on the back foot after Friday’s stronger-than-expected US August payrolls report reinforced the dollar and pulled the pair off its recent highs. Thursday’s ECB decision is this week’s clearest domestic catalyst; with a 25-basis-point hike to a 2.50% deposit rate almost fully priced by markets, CSFX sees President Lagarde’s press conference — and specifically any signal on the fully-priced follow-up December hike — as the detail most likely to move the pair, rather than the decision itself.
2. GBP/USD — a quiet domestic calendar leaves the pound trading on the dollar and Friday’s growth data. GBP/USD at 1.3531 holds a touch below recent highs with the Bank of England’s Monetary Policy Committee not due again until 17 September, after holding the Bank Rate at 3.75% in a divided 6–3 vote in July. Friday’s UK GDP, industrial production, and manufacturing production data for July are the week’s key domestic inputs; CSFX expects the pair to otherwise track broader dollar sentiment and Thursday’s ECB decision more than any single UK release.
3. DAX and STOXX 600 — German data flow meets a market digesting higher bond yields. DAX 40 at 26,033.39 sits just below its record closing high of 26,569.99 set on 28 August, while the broader STOXX 600 at 647.46 has pulled back roughly 0.9% over the past week as a global government-bond yield surge weighed on sentiment. Monday’s German industrial production figures and Tuesday’s trade balance are the week’s first tests of whether German factory momentum — recently boosted by defence-related orders — is holding up, ahead of Thursday’s ECB decision.
4. FTSE 100 and Brent Crude — a live Middle East risk premium meets Friday’s UK data. FTSE 100 at 10,828.14 holds close to record territory, supported by its energy and mining weighting, while Brent Crude at $95.23 remains elevated after renewed Iranian strikes on Kuwait and a resumption of US strikes on Iranian targets reignited the ongoing Strait of Hormuz crisis. CSFX sees continued headline sensitivity around the Gulf, alongside Sunday’s OPEC+ meeting outcome, as the dominant swing factor for both instruments this week.
Three Forces That Will Drive the European Session — 7 to 12 September 2026
The scheduled European-session catalysts that will set the direction across FX, equities, and commodities for the week of 7–12 September 2026
European Session Weekly Levels & Bias
Six instrument-specific reference levels for the week of 7–12 September 2026. All levels for reference and informational purposes only; not financial advice. Visit capitalstreetfx.com for live signals and other markets.
What to Watch — Thursday’s ECB Decision Is the Week’s Key Swing Factor
EUR/USD slipped back below 1.1650 after Friday’s US August payrolls report printed well above expectations, reinforcing the dollar into the weekend. With a 25-basis-point ECB hike to 2.50% almost fully priced, CSFX sees the reaction hinging less on the decision itself and more on whether Lagarde’s press conference confirms or pushes back on the fully-priced December follow-up hike, with a hawkish tone supporting a retest of 1.1680 and a more cautious tone risking a slide toward 1.1550.

What to Watch — Friday’s UK Growth Data Is the Week’s Key Domestic Release
Sterling holds just below recent highs, with the Bank of England on hold at 3.75% since a divided 6–3 vote in July and its next decision not due until 17 September. Friday’s UK GDP, industrial production, manufacturing production, and non-EU trade balance data for July are the week’s clearest domestic catalyst; CSFX sees the pair otherwise tracking Thursday’s ECB decision and broader dollar sentiment more than any single UK release.

What to Watch — Monday’s Production Data and Tuesday’s Trade Balance Set the Tone
The DAX sits just below its 28 August record closing high of 26,569.99, having cooled slightly alongside a broader government-bond yield surge over the past week. Monday’s German industrial production figures for July and Tuesday’s foreign trade data are the clearest domestic catalysts; CSFX sees confirmation of broadening factory momentum as the more likely trigger for a fresh push toward the record high, with a soft print risking a retest of the 25,700 area into Thursday’s ECB decision.

What to Watch — A Pan-European Read on the Same German Data and ECB Decision
The broader STOXX 600 has pulled back from its 52-week high of 663.41 as rising global government-bond yields weighed on sentiment over the past week, even as the index still carries an 11% year-to-date gain led by semiconductor names like ASML and Infineon. CSFX sees Monday and Tuesday’s German data, alongside Thursday’s ECB decision, as the two catalysts most likely to set the index’s direction into the weekend.

What to Watch — Friday’s UK Data Meets a Live Middle East Risk Premium
The FTSE 100 closed essentially flat on Friday, holding above 10,800 as investors weighed a resilient energy and mining weighting against a Bank of England signalling it may be ready to hike if inflation keeps climbing. With no BoE meeting this week, CSFX sees the index’s heavy energy exposure as the key link to Gulf headline flow, alongside Friday’s UK GDP and production data for July.
What to Watch — Gulf Headline Risk Remains the Dominant Swing Factor
Brent has traded with a firm bid after Kuwait reported it was fending off fresh Iranian missile and drone attacks, and the US resumed strikes on Iranian targets following roughly a month of relative calm in the Strait of Hormuz crisis. CSFX sees Sunday’s OPEC+ meeting outcome and any further escalation around the strait as the clearest swing factors for the week, while a diplomatic de-escalation remains the primary downside risk into Friday’s close.

What Could Move European Markets Sharply This Week
The scheduled and unscheduled events that CSFX is watching most closely for the European session, 7–12 September 2026
European Session — Economic Calendar, 7–12 September 2026
All times approximate, Central European Time (CET/CEST) unless noted. Key releases for EUR/USD, GBP/USD, DAX 40, STOXX 600, FTSE 100, and Brent Crude.
| Day | Time (CET) | Release | Impact | Forecast | CSFX View |
|---|---|---|---|---|---|
| Monday, 7 September | |||||
| Mon | ~08:00 CET | Germany Production Index (July) | MED | N/A | The week’s first read on German factory momentum, following June’s third straight monthly gain, and a lead-in for DAX and STOXX 600 positioning ahead of Thursday’s ECB decision. |
| Tuesday, 8 September | |||||
| Tue | ~08:00 CET | Germany Foreign Trade Balance (July) | MED | N/A | Exports and imports data that adds context on external demand for German manufacturing, with limited standalone market impact expected ahead of the ECB decision. |
| Wednesday, 9 September | |||||
| Wed | All Day | Pre-ECB Positioning Across EUR and European Rates | LOW | N/A | A largely quiet scheduled calendar leaves the session to trade on positioning ahead of Thursday’s decision and continued Middle East headline flow. |
| Thursday, 10 September | |||||
| Thu | ~14:15 CET | ECB Interest Rate Decision | HIGH | +25bp to 2.50% | The week’s single most important scheduled event; a hike is almost fully priced, so the reaction hinges on Lagarde’s tone in the press conference that follows. |
| Thu | ~14:45 CET | ECB Press Conference (President Lagarde) | HIGH | N/A | CSFX watches for any signal on the fully-priced follow-up December hike and how the Governing Council frames the inflationary impact of the Middle East energy shock. |
| Thu | Evening CET | US Producer Price Index (August) | MED | N/A | A dollar-side input landing after the European close, setting up positioning ahead of Friday’s more closely watched US CPI report. |
| Friday, 11 September | |||||
| Fri | ~08:00 CET | UK GDP MoM, Industrial & Manufacturing Production, Goods Trade Balance Non-EU (July) | HIGH | N/A | The week’s key domestic catalyst for GBP/USD and the FTSE 100, and the last major UK data before the Bank of England’s 17 September decision. |
| Fri | Evening CET | US Consumer Price Index (August) | HIGH | N/A | Lands late in the European session; CSFX sees this as the dominant dollar-side crosscurrent for EUR/USD and GBP/USD into the weekend, roughly a week ahead of the Fed’s own meeting. |
| Saturday, 12 September | |||||
| Sat | All Day | No European Trading Session | LOW | N/A | Markets are closed, but weekend commentary on the ECB decision, UK data, and Middle East developments can still shape Monday’s open. |
European Session — Trader Questions Answered
Key questions from CSFX clients ahead of the ECB rate decision, German data flow, and UK growth numbers
CSFX View: ECB’s Second Hike, German Data, and UK Growth Numbers Set the Tone for the Week Ahead
The week of 7–12 September 2026 opens the European session with EUR/USD at 1.1606, softer after Friday’s much stronger-than-expected US August payrolls report reinforced the dollar, while GBP/USD at 1.3531 holds just below recent highs with the Bank of England on hold until 17 September. The DAX at 26,033.39 sits just below its 28 August record closing high, and the broader STOXX 600 at 647.46 has pulled back roughly 0.9% over the past week as a global government-bond yield surge weighed on sentiment, heading into Monday’s German industrial production data and Tuesday’s trade balance. The FTSE 100 at 10,828.14 holds close to record territory, supported by energy and mining names, as Brent Crude at $95.23 stays elevated after renewed Iranian strikes on Kuwait and a resumption of US strikes on Iranian targets reignited the ongoing Strait of Hormuz crisis.
Thursday is the pivot point for the entire week: the ECB is widely expected to deliver its second 25-basis-point hike of the current tightening cycle, taking the deposit rate to 2.50%, after August’s flash inflation print hit a three-year high of 3.3% year-on-year on the back of a 14.3% jump in energy inflation. EUR/USD’s path through the back half of the week depends heavily on how President Lagarde frames the fully-priced follow-up hike expected at December’s meeting, while Friday’s UK GDP, industrial production, and trade data provide the week’s clearest domestic catalyst for GBP/USD and the FTSE 100 ahead of the Bank of England’s own 17 September decision. In equities, the DAX and STOXX 600 look to Monday and Tuesday’s German data for confirmation that factory momentum is broadening beyond defence-linked orders, while the FTSE 100 and Brent Crude remain most exposed to any fresh escalation around the Strait of Hormuz.
CSFX’s key levels for the week: watch 1.1550 support and 1.1680 resistance on EUR/USD ahead of Thursday’s ECB decision, and 1.3420 support and 1.3620 resistance on GBP/USD given Friday’s UK data dump. The DAX is a watch between 25,700 support and its 26,570 record-high resistance pending this week’s German releases, with the STOXX 600 tracking between 638.00 and 663.00 on the same data. The FTSE 100’s next test is 11,000 resistance with 10,650 as key support if sentiment sours, while Brent Crude trades between $88.00 support and $99.00 resistance as Gulf headline risk stays elevated. CSFX will issue intra-week alerts if the ECB’s tone on December diverges materially from current pricing, if Monday or Tuesday’s German data surprises sharply in either direction, if Friday’s UK growth figures diverge meaningfully from recent trend, or if the Strait of Hormuz situation escalates further. Follow all updates at capitalstreetfx.com.
New clients can also take advantage of a limited-time deposit bonus when they open an account this week, on top of the usual account benefits — tight spreads, high leverage, and access to 2000+ instruments across FX, commodities, indices, and crypto. Full terms and other promotions are available on the CSFX website.
Trade European Markets at CSFX →