Global Relief Rally Reaches Europe as Bond Yields Ease, the Dollar Slips and Brent Crude Falls Back Toward $95 Ahead of Friday’s Payrolls | Technical Analysis – European Session | 03-09-2026
Global Relief Rally Reaches Europe as Bond Yields Ease, the Dollar Slips and Brent Crude Falls Back Toward $95 Ahead of Friday’s Payrolls
EUR/USD · GBP/USD · Silver · Crude Oil · DAX 40 · EU 10Y Yield · ETH/USD · Dogecoin — live European market outlook today, updated through the trading session
European Market News — Live Now, 3 September 2026
Top-moving headlines shaping the European market outlook today, updated through the morning
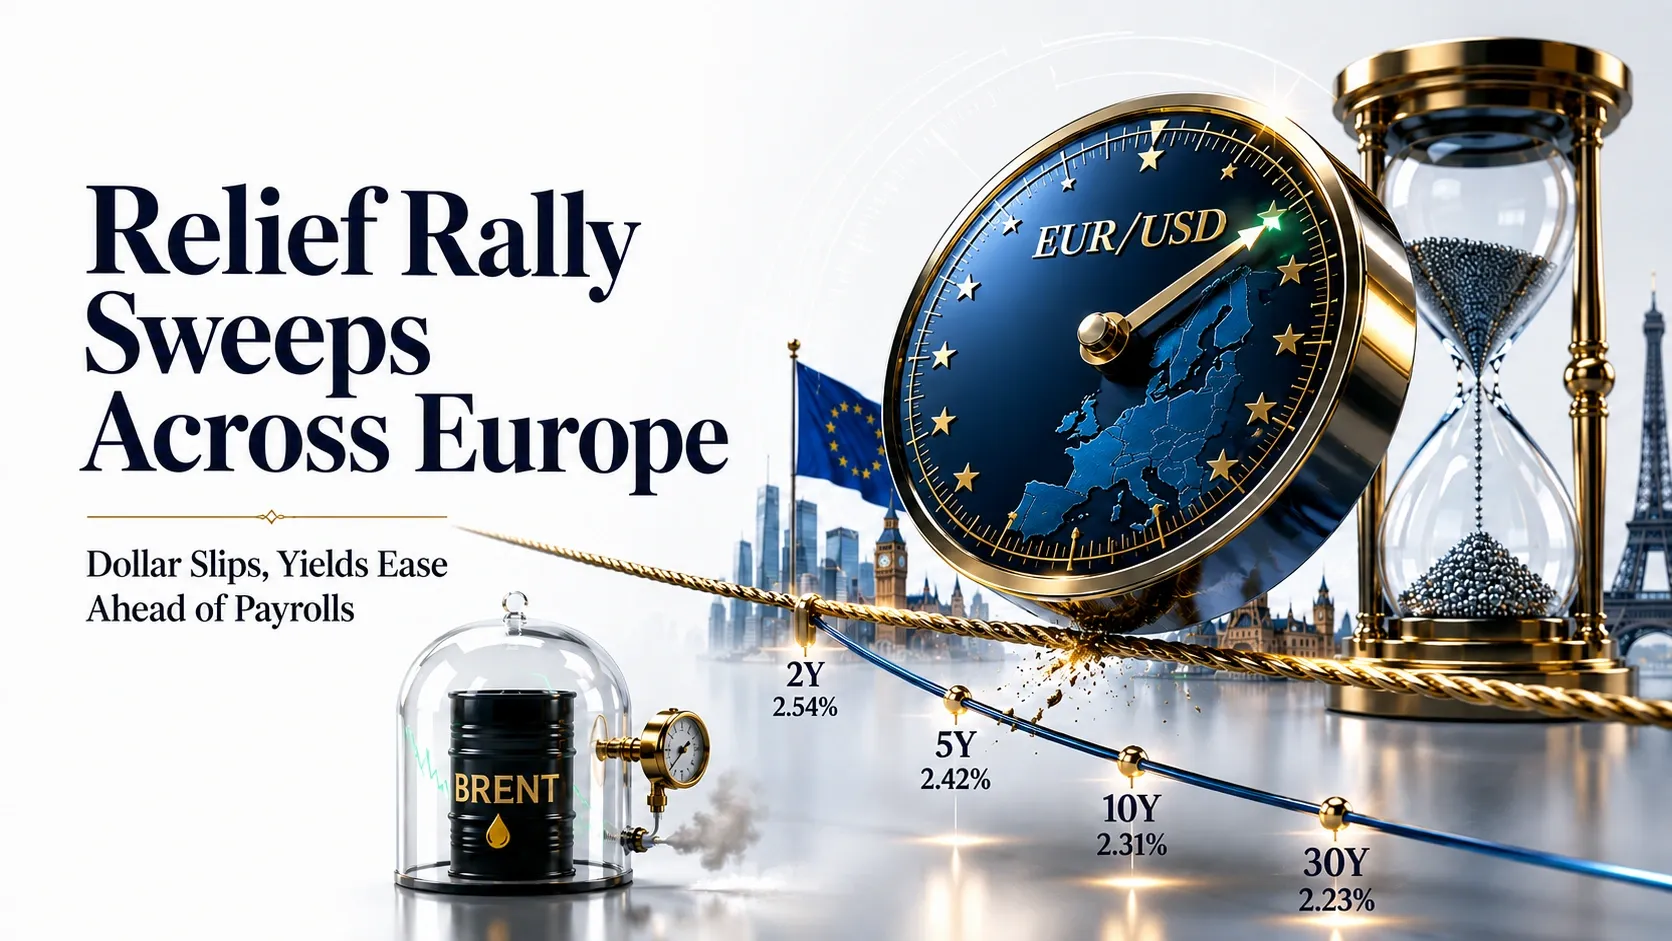
Relief Rally Reaches Europe: Shares and Bonds Extend Asia Rebound, Brent Eases Toward $95
Shares and bonds staged a broad relief rally in Asia overnight and are carrying into the European morning, as Japanese government bond yields slid from historic peaks and Treasury yields eased. Brent crude has slipped roughly 0.4% to near $95.25, snapping its three-day rally, after Trump’s comments that renewed Iran strikes would likely be “short-lived” eased the geopolitical risk premium, though he separately warned of an “economic D-Day” campaign against Tehran.
GeopoliticsDollar Index Slips to Near 99.4, Yen Jumps to Three-Week High as Fed Bets Cool
US private payrolls rose by just 38,000 in August, missing the roughly 47,000-48,000 consensus and marking the slowest pace of hiring since January, according to Wednesday’s ADP National Employment Report. New York Fed President John Williams reinforced the dovish shift, and Fed Governor Christopher Waller is due to speak later today; the Dollar index has eased roughly 0.2% while the yen has jumped to its strongest level since mid-August, with Friday’s Non-Farm Payrolls now the decisive data point.
RatesGerman Bund Yields Ease From 2011 Highs as European Futures Point to a Firmer Open
Germany’s 10-year Bund yield, which touched 3.38% on Wednesday — its highest since April 2011 — is easing back as the global bond selloff pauses, tracking a similar pullback in Japanese and US Treasury yields overnight. Euro Stoxx 50, DAX and FTSE futures are each pointing to a modestly firmer cash open, building on Wednesday’s STOXX 600 close after a volatile week driven by the Middle East escalation.
BondsEUR/USD Holds Near 1.1598, GBP/USD Firmer Near 1.3500 as Dollar Retreats
EUR/USD is trading around 1.1598 in early European trade, edging higher as a broad Dollar retreat and the softer ADP print weigh on the Greenback across G10 currencies. GBP/USD is similarly firmer near 1.3500-1.3502 even as UK 10-year gilt yields hold close to 5.25%-5.29%, their highest level since 2007.
ForexDAX 40 Futures Point Higher Near 25,870-25,900 After Three Sessions of Losses
Germany’s DAX 40 is indicated to open modestly higher, with futures pointing to a level near 25,870-25,900, as easing bond yields and a calmer oil market lift rate-sensitive banks and industrials following Wednesday’s close at 25,839.33. The index remains roughly 3% below its late-August record levels as investors continue to digest the Middle East escalation and a hawkish ECB-Fed backdrop.
EquitiesSilver Holds Near $65.88 as Softer US Data Revives Demand for Non-Yielding Metals
Silver is trading near $65.88 an ounce, up roughly 0.87% on the day, rebounding as the cooler ADP print and receding Fed-hike odds ease the headwind from a firmer Dollar. ETH/USD is holding near $2,395-2,400 and Dogecoin is firmer near $0.082-0.083, both steadier after a choppy start to September for crypto risk appetite.
Commodities & CryptoLive · Updated through the European morning session, Thursday 3 September 2026
European Economic Calendar This Week — 3 September 2026
Key releases and events shaping price action through the rest of the week
| Time | Event | Forecast / Detail | Impact | Market Read |
|---|---|---|---|---|
| 🇺🇸Wednesday, 2 Sept (Recap) | US ADP Employment Change (August) | +38K actual vs ~+47-48K consensus, slowest since January | 🔴 CRITICAL | Sparked a global bond relief rally and eased September Fed hike bets |
| 🇺🇸Wednesday, 2 Sept (Recap) | NY Fed President John Williams Strikes “Wait and See” Tone | Signals no commitment yet to a September rate move | 🔴 CRITICAL | Reinforces the dovish repricing that followed the soft ADP print |
| 🇮🇷Ongoing (Overnight) | Trump Calls Renewed Iran Strikes “Short-Lived” | Reiterates claim US controls the Strait of Hormuz; separately warns of “economic D-Day” pressure on Iran | 🔴 CRITICAL | Eased oil’s risk premium but the conflict remains unresolved |
| 🇩🇪Today (Ongoing) | German 10Y Bund Yield Easing From 2011 High | Touched 3.38% Wednesday, highest since April 2011; easing today | 🔴 CRITICAL | Tracks the broader global bond relief rally |
| 🇺🇸Friday, 4 September | US Non-Farm Payrolls (August) | Now the week’s decisive US data risk after the soft ADP print | 🔴 CRITICAL | A weak print would further unwind September Fed hike pricing |
| 🇪🇺Tue-Wed, 15-16 September | ECB Governing Council Meeting | ~80% probability of a 25bp hike to 2.50%; deposit rate seen near 2.70% by December | 🔴 CRITICAL | Remains the dominant near-term catalyst for EUR/USD direction |
| 🇬🇧Ongoing | UK 10Y Gilt Yield Near 2007 Highs | Holding around 5.25%-5.29% after Wednesday’s escalation-driven selloff | 🟢 MEDIUM | Keeps a lid on FTSE 100 and Sterling-sensitive sectors despite today’s calmer tone |
| 🇯🇵Later this month | Bank of Japan Policy Meeting | Yen rallying sharply into the decision on rising rate-hike bets | 🟢 MEDIUM | Indirect driver of broader G10 FX volatility this week |
European Session Trade Ideas — EUR/USD, GBP/USD and More
Technical setups and fundamental context across the session’s eight key instruments
EUR/USD
Why This Setup
The soft ADP print and NY Fed’s “wait and see” tone are a genuine tailwind, unwinding some of the Dollar bid that had built on hawkish September Fed pricing, while an ECB still on course for a 15-16 September hike adds further support; Friday’s Non-Farm Payrolls is a real source of two-way risk that could reverse the move quickly if it surprises to the upside.

GBP/USD
Why This Setup
The softer US data and receding Fed hike bets are a genuine tailwind for Cable, while UK 10-year gilt yields near their highest since 2007 still price a BoE hike by year-end and offer some independent support; renewed Middle East escalation or a hot Friday payrolls print are a real source of two-way risk that could revive the broad Dollar bid.

Silver
Why This Setup
The soft ADP print and NY Fed’s cautious tone are a genuine tailwind, easing the cost-of-carry headwind that had pressured the metal earlier in the week, while silver’s structural industrial-demand story adds further support; a hot Friday Non-Farm Payrolls print reviving hawkish Fed bets is a real source of two-way risk.

Crude Oil
Why This Setup
Trump’s comments that renewed Iran strikes will likely be short-lived and a record 17-million-barrel Hormuz transit volume are a genuine headwind for the geopolitical risk premium, though the conflict remains unresolved and Trump’s parallel threat of an “economic D-Day” campaign against Iran is a real source of two-way risk that could reignite the rally on any fresh escalation headline.

DAX 40
Why This Setup
Easing German Bund yields and a calmer oil market are a genuine tailwind for rate-sensitive banks and industrials after three straight sessions of losses, though the index remains roughly 3% below its late-August record and any fresh Hormuz escalation or hot Friday payrolls print is a real source of two-way risk that could revive the sell-off.

EU 10Y Yield
Why This Setup
The soft ADP print and easing oil-driven inflation premium are a genuine headwind for yields after this week’s sharp run-up, though an ECB still widely expected to hike on 15-16 September and any renewed Hormuz escalation are a real source of two-way risk that could quickly push Bund yields back toward their 2011 highs.

ETH/USD
Why This Setup
August’s strong monthly gain of more than 32% and the softer ADP-driven pullback in Fed hike odds are a genuine tailwind for institutional risk appetite, though the pause in fresh US spot Ethereum ETF inflows and Friday’s Non-Farm Payrolls are a real source of two-way risk that could reverse the recent stabilization.

Dogecoin
Why This Setup
Dogecoin’s classification as a digital commodity under the joint SEC-CFTC framework and August’s rally of more than 20% remain genuine tailwinds for institutional access, though thin liquidity and any fresh Fed-driven risk-off swing into Friday’s Non-Farm Payrolls are a real source of two-way risk for the meme-coin complex.

European Session FAQ — 3 September 2026
Quick answers to the questions traders are asking this session
Why did Trump say the renewed Iran strikes would be “short-lived”?
Why did the soft ADP print trigger a global bond relief rally?
Why is Crude Oil falling after a three-day rally?
Why is EUR/USD rebounding today?
Why are German Bund yields easing from their 2011 highs?
Why is the DAX 40 attempting to stabilize today?
Why is GBP/USD firmer despite elevated UK gilt yields?
What should traders watch for the rest of the European session?
European Session Summary — Thursday, 3 September 2026 (Live Update)
Thursday’s European session is opening on a firmer footing as a relief rally that began in Asian trading carries through into the European morning, with the Dollar index easing roughly 0.2% to near 99.4 and the yen jumping to its strongest level since mid-August. The move follows a soft US ADP employment report showing private payrolls rose by just 38,000 in August against a roughly 47,000-48,000 consensus, with New York Fed President John Williams reinforcing the dovish shift by urging a “wait and see” approach and Fed Governor Christopher Waller due to speak later today, ahead of Friday’s US Non-Farm Payrolls report, which has now become the week’s decisive data point. President Trump’s overnight comments that renewed US strikes on Iran would likely be “short-lived” continue to ease the geopolitical risk premium, even as the conflict remains far from resolved and he separately warned of an “economic D-Day” campaign against Tehran.
Germany’s 10-year Bund yield, which touched 3.38% on Wednesday — its highest since April 2011 — is easing back as the bond selloff pauses, tracking a similar pullback in US and Japanese yields overnight, while UK 10-year gilt yields remain pinned near 5.25%-5.29%, their highest since 2007. EUR/USD is trading around 1.1598 as the broad Dollar retreat unwinds part of the hawkish-Fed-driven bid from earlier in the week, and GBP/USD is firmer near 1.3500-1.3502 on the same Dollar softness, even as elevated gilt yields continue to cap UK rate-sensitive equities.
Crude Oil is retreating from its five-week highs, with Brent easing toward $95.25 and WTI near $89.94 after surging almost 9% over the prior three sessions, while Silver is holding around $65.88 an ounce as receding Fed-hike odds revive demand for the non-yielding metal. Germany’s DAX 40 is indicated to open near 25,870-25,900, tracking Wednesday’s 25,839.33 close after three consecutive sessions of losses, with Euro Stoxx 50 and FTSE futures also pointing to a modestly firmer cash open. Crypto markets are steadier, with ETH/USD holding near $2,395-2,400 and Dogecoin firmer near $0.082-0.083, both consolidating after a choppy start to September.
Highest-conviction session idea: favour the relief-rally trades — buying dips in EUR/USD, GBP/USD, DAX 40 and the crypto majors, and fading Crude Oil and EU 10Y Yield rallies — while staying alert to any reversal in tone from Washington or Tehran that could reignite the geopolitical risk premium into Friday’s Non-Farm Payrolls.
For the individual instruments: EUR/USD buy dips toward 1.1540, stop 1.1470, target 1.1750 — the soft ADP print and cautious Fed tone are a genuine tailwind, though Friday’s payrolls report is a real source of two-way risk. GBP/USD buy dips toward 1.3420, stop 1.3330, target 1.3650 — the broad Dollar retreat is a genuine tailwind, though elevated gilt yields and any renewed Dollar bid are a real source of two-way risk. Silver buy dips toward $63.80, stop $61.50, target $69.50 — easing Fed-hike odds are a genuine tailwind, though a hot payrolls print is a real source of two-way risk. Crude Oil sell rallies toward $92.50, stop $95.50, target $85.00 — Trump’s de-escalation signal is a genuine headwind for the risk premium, though the conflict remains unresolved and is a real source of two-way risk. DAX 40 buy dips toward 25,500, stop 25,150, target 26,400 — easing yields are a genuine tailwind, though any fresh escalation headline is a real source of two-way risk. EU 10Y Yield sell rallies toward 3.42%, stop 3.50%, target 3.15% — the bond relief rally is a genuine headwind for yields, though the looming ECB hike is a real source of two-way risk. ETH/USD buy dips toward $2,280, stop $2,120, target $2,650 — easing Fed-hike bets are a genuine tailwind, though the ETF inflow pause is a real source of two-way risk. Dogecoin buy dips toward $0.0740, stop $0.0680, target $0.0950 — its digital-commodity classification is a genuine tailwind, though thin liquidity into payrolls is a real source of two-way risk. The decisive variable for the rest of the day is whether today’s relief rally holds into Friday’s Non-Farm Payrolls, or whether fresh Middle East headlines reassert the risk-off tone that dominated earlier in the week. Size positions accordingly, and note that fast-moving geopolitical and data headlines carry genuine event risk that could exaggerate moves in either direction.
Ready to act on today’s setups? Open an Account with Capital Street FX and trade every instrument covered in this report on our Zero Account‘s 0.0 Pips Spreads and 1:10000 Leverage, across 2000+ Instruments, with a welcome deposit bonus and 24/7 Live Support on hand for every session.
Not sure which account fits your style? Compare our Account Types side by side with our Account Comparison tool, browse current Promotions / Bonus offers, and trade from our Trading Platform suite. Funding is simple via our Deposit & Withdrawal options. For ongoing coverage, explore our Forex Analysis Pages, Commodity Analysis Pages and Crypto Analysis Pages, plus our Daily Market Analysis and Weekly Market Analysis reports and the full Economic Calendar. New to trading? Visit our Trading Education / Blog, or reach our Contact Us / Live Support team any time.
Access Live European Markets →