Week Ahead, 21–25 September: Flash PMIs, Ifo and a Trump–Gulf Summit Take Over as European Markets Catch Their Breath After Last Week’s Central-Bank Triple-Header | Technical Analysis – European Session | 19-09-2026
Week Ahead, 21–25 September: Flash PMIs, Ifo and a Trump–Gulf Summit Take Over as European Markets Catch Their Breath After Last Week’s Central-Bank Triple-Header
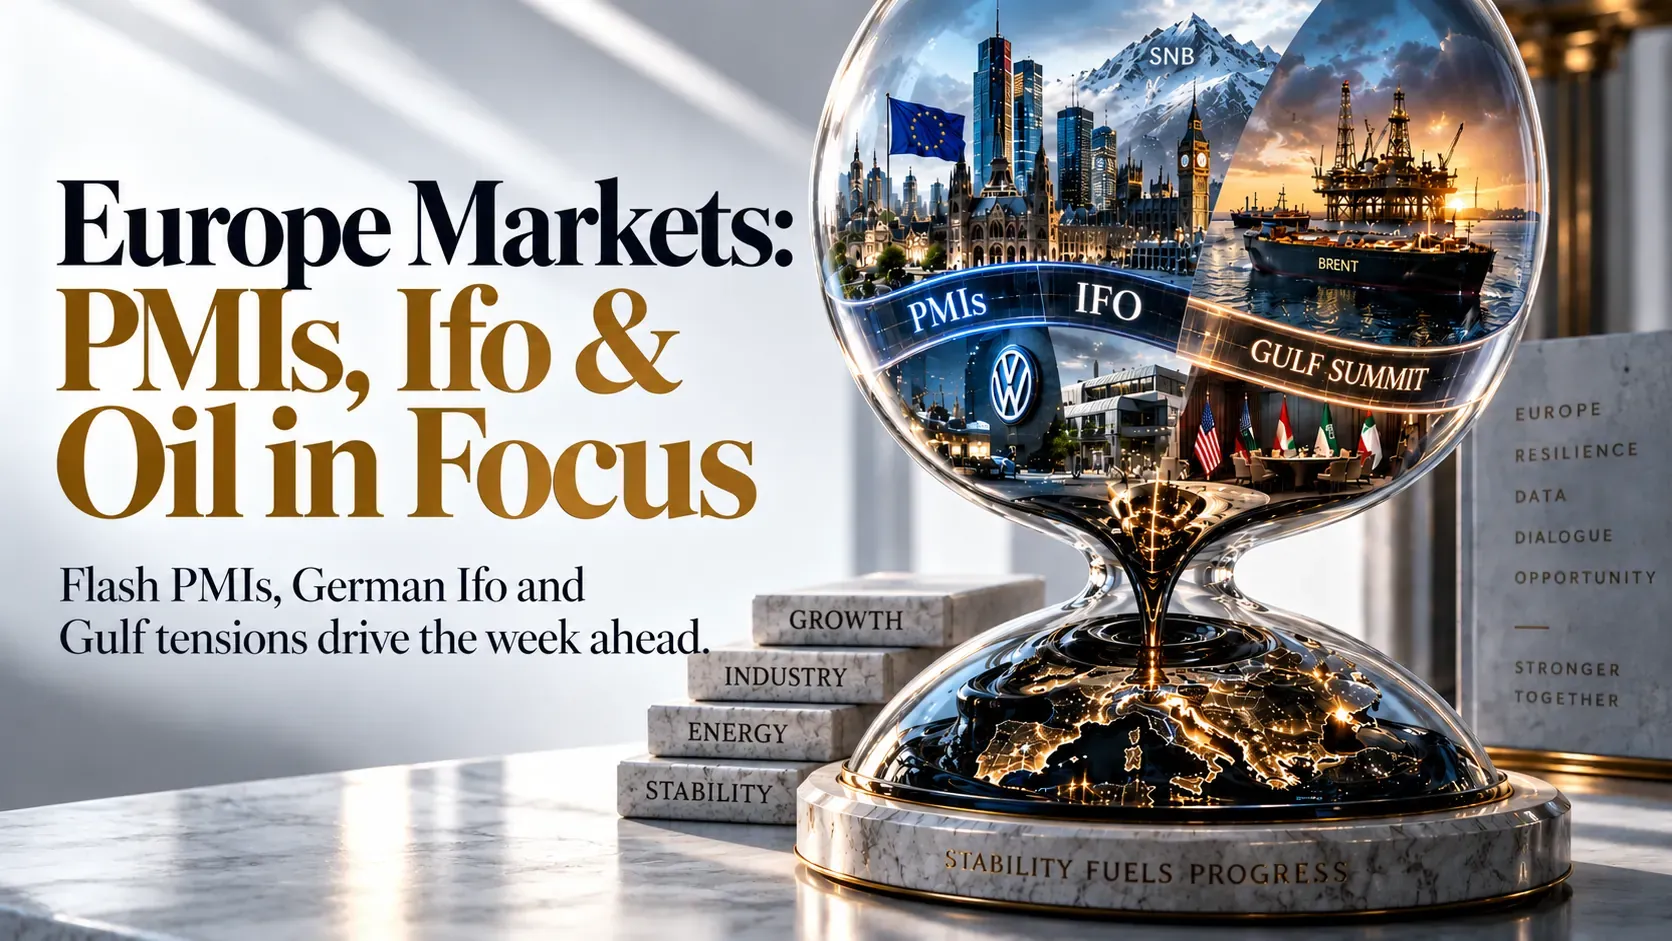
Trump–Gulf Leaders Meeting Tue 22 Sep · Flash PMIs (Germany/Euro Area/UK) Wed 23 Sep · SNB Rate Decision Thu 24 Sep · Ifo Business Climate Thu 24 Sep · UK GfK Consumer Confidence Fri 25 Sep
For ongoing European Market Insights and Market Analysis, visit the CSFX Research Desk. This week’s European market outlook breaks down into four key threads:
1. EUR/USD — a hawkish Fed and a cooling ECB hike narrative leave the dollar in control. EUR/USD at 1.1478 ended last week down roughly 1% and traded to its weakest level since late July, as the Dollar Index pushed to a fresh seven-week high near 100.50. The Fed’s unanimous hike and a median dot-plot projection of 4.1% for both year-end 2026 and 2027 did the damage, but the euro’s own story softened too: with ECB President Lagarde ruling out fears of second-round inflation effects last week, money markets have trimmed the odds of a second ECB hike this year to roughly 50%, down from the near-certainty priced immediately after the 10 September move. CSFX sees Wednesday’s flash PMIs as the next test of whether the euro can find a floor, since a soft euro-area reading would reinforce the case for a more patient ECB. For more EUR/USD technical analysis and daily Forex analysis, visit the CSFX research desk.
2. GBP/USD — with the BoE off the calendar until November, sterling is now a data-and-speaker story. GBP/USD at 1.3394 closed last week near a two-month low after Thursday’s 6–3 hold, with the three dissenters — Megan Greene, Catherine Mann and Huw Pill — again backing an immediate move to 4.00%. Governor Bailey said the energy shock has so far had a limited impact on UK prices and wages but warned that prolonged volatility could force the Bank’s hand. With no MPC meeting until 5 November, CSFX sees Wednesday’s flash UK composite PMI and any remarks from the three dissenting hawks as the more likely near-term catalysts than anything scheduled for release this week. See our latest GBP/USD analysis and broader UK market analysis for updates through the week.
3. DAX and STOXX 600 — a Volkswagen profit warning collides with Thursday’s Ifo test. DAX 40 at 25,308.88 fell 1.65% on Friday alone — its worst single session since late July — as Volkswagen dropped 5.6% on roughly €10 billion of flagged one-off items tied to its Porsche stake, job-cut provisions and weak Chinese demand, dragging the autos sector down 3.4% for the day. The broader STOXX 600 at 635.45 lost 1.1% on Friday and closed the week down 0.6%, even as August’s Ifo Business Climate reading had shown German sentiment at 88.8, its best level since 2023. CSFX sees Thursday’s September Ifo print as the week’s key test of whether that improving-sentiment narrative survives contact with a fresh corporate profit warning and still-elevated energy costs.
4. FTSE 100 and Brent Crude — oil retreats from its Hormuz-crisis peak, but Tuesday’s summit is the real test. FTSE 100 at 10,651.02 finished last week almost exactly flat, round-tripping through a Thursday rally and a Friday selloff, while Brent Crude at $103.21 has pulled back from a weekly high near $109.97 as Saudi Arabia reported progress repairing its East-West pipeline and rerouted cargo through Oman’s Sohar port. CSFX sees Tuesday’s meeting between President Trump and Gulf Cooperation Council leaders in New York — convened to discuss a postwar framework for the Strait of Hormuz — as the single most important scheduled event for oil this week, with the power to either cement the de-escalation or reignite the shock that drove Brent above $110 twice this month.
Three Forces That Will Drive the European Session — 21 to 25 September 2026
The scheduled and unscheduled European-session catalysts that will set the direction across FX, equities, and commodities for the week of 21–25 September 2026
European Session Weekly Levels & Bias
Six instrument-specific reference levels for the week of 21–25 September 2026. All levels for reference and informational purposes only; not financial advice. Visit capitalstreetfx.com for live signals and other markets.
What to Watch — A Hawkish Fed Meets a Softening ECB Hike Narrative
The euro slid to its weakest level since late July, closing the week near 1.1478 after rejecting from a Monday high of 1.1604 and printing a Wednesday low of 1.1458. The Dollar Index’s push to a fresh seven-week high near 100.50 is the dominant force, but the euro’s own case has weakened too, with the ECB’s Lagarde ruling out second-round inflation effects and markets trimming the odds of a further ECB hike this year to roughly 50%. CSFX sees Wednesday’s flash composite PMI for the euro area as the pair’s key swing factor: a reading that confirms the recent improvement in sentiment would support a bounce toward 1.1605, while a soft print risks a break of 1.1458 toward the 1.1360 area.

What to Watch — A Divided MPC Now Off the Calendar Until November
Sterling closed the week near its weakest level since late July, at 1.3394, after the Bank of England’s 6–3 hold left the same three hawks — Greene, Mann and Pill — dissenting in favour of a hike, the same split as July. With the next MPC decision not due until 5 November, CSFX sees this week’s flash UK composite PMI on Wednesday, plus any remarks from the dissenting trio, as the more likely near-term drivers than anything else on the calendar. A strong PMI print would support a recovery toward 1.3450, while a weak one risks a retest of the 1.3345 low and, ultimately, the 1.3250 area.

What to Watch — Volkswagen’s Warning Meets Thursday’s Ifo Test
The DAX closed its lowest since late July after Friday’s 1.65% slide, led by Volkswagen’s 5.6% drop on roughly €10 billion of flagged one-off charges and a 3.4% fall across the wider automobile sector. Price is now well below the index’s 26,569.99 record close set on 28 August, with the week’s low at 25,296 sitting just above the psychologically important 25,000 level. CSFX sees Thursday’s Ifo Business Climate reading — August’s 88.8 print was Germany’s best since 2023 — as the key test of whether Friday’s selloff was an idiosyncratic Volkswagen story or the start of a broader reassessment of German equities. A resilient Ifo print would support a recovery toward 25,943, while a disappointing one risks a slide toward 24,650.

What to Watch — Autos and Telecoms Lead a Broad-Based Friday Slide
The pan-European benchmark fell 1.1% on Friday to 635.45, giving up almost all of the gains made over Wednesday and Thursday, with automobile and parts shares down 3.4% and telecoms among the other laggards. Energy shares held up better in relative terms, supported by Brent’s elevated level even as oil eased from its weekly high. CSFX sees Wednesday’s flash composite PMIs for Germany, France and the euro area as a whole as the week’s clearest test of whether the pullback from record territory extends or stabilises around the 634.62 area.

What to Watch — A Genuinely Two-Sided Week Tied Directly to Oil
London’s benchmark finished last week almost exactly where it started, round-tripping from a Thursday high near 10,868 on the BoE’s hold to a Friday low near 10,594 as the broader European selloff caught up with it. With no UK data releases of real significance until Friday’s GfK consumer confidence print, CSFX sees the FTSE’s energy and mining weighting as the reason it will likely track Tuesday’s Trump–Gulf leaders meeting more closely than any other major European index this week — a durable de-escalation signal would be constructive for the broader index even as it weighs on the oil majors, while a breakdown in talks would do the opposite.

What to Watch — Tuesday’s Trump–Gulf Meeting Is the Single Biggest Catalyst
Brent has eased back from a weekly high of $109.97 to close near $103.21, as Saudi Arabia reported progress restoring flows through its damaged East-West pipeline and arranged additional ship-to-ship cargo transfers through Oman’s Sohar port. That is a genuine easing of the acute supply shock, but the underlying crisis remains unresolved: a planned Iran–Gulf states meeting on Hormuz shipping was postponed last week, and Houthi attacks on Saudi territory around the Bab el-Mandeb Strait have continued. CSFX sees Tuesday’s meeting between President Trump and Gulf Cooperation Council leaders in New York as the week’s dominant catalyst — a credible postwar framework would open the way toward $100.00 and below, while a stalled or hostile outcome risks a retest of $109.97 and beyond.

What Could Move European Markets Sharply This Week
The scheduled and unscheduled events that CSFX is watching most closely for the European session, 21–25 September 2026
European Session — Economic Calendar, 21–25 September 2026
All times approximate, Central European Time (CET/CEST) unless noted. Key releases for EUR/USD, GBP/USD, DAX 40, STOXX 600, FTSE 100, and Brent Crude.
| Day | Time (CET) | Release | Impact | Forecast | CSFX View |
|---|---|---|---|---|---|
| Monday, 21 September | |||||
| Mon | ~01:15 CET | People’s Bank of China Interest Rate Decision (1-Year LPR) | LOW | Hold at 3.00% | The PBoC is widely expected to hold, with any surprise statement more likely to move Asian markets and mining-heavy names on the FTSE and DAX than the broader European session directly. |
| Mon | All Day | Post-Fed/BoE Positioning · Volkswagen Follow-Through · Oil Headlines | LOW | N/A | A light scheduled calendar leaves the session trading on the aftermath of Friday’s DAX selloff, the direction of Bund and Treasury yields, and Gulf headline flow ahead of Tuesday’s summit. |
| Tuesday, 22 September | |||||
| Tue | All Day | Trump Meets Gulf Cooperation Council Leaders (UN General Assembly, New York) | HIGH | N/A | The week’s dominant unscheduled catalyst. Any signal on a postwar framework for the Strait of Hormuz, or the absence of one, carries directly into Brent, the FTSE 100, and European rates pricing. |
| Tue | ~05:10 CET | RBA Governor Michele Bullock Speech | LOW | N/A | Lands before the European open; relevant mainly to broad risk appetite and commodity currencies rather than European instruments directly. |
| Wednesday, 23 September | |||||
| Wed | ~07:30 CET | Germany Flash Manufacturing, Services & Composite PMI (September) | HIGH | N/A | The first read on whether the improvement in Ifo sentiment through the summer is showing up in actual business activity, ahead of Thursday’s Ifo release. |
| Wed | ~08:00 CET | Euro Area Flash Manufacturing, Services & Composite PMI (September) | HIGH | N/A | The most consequential scheduled European-session release of the week in the absence of a central bank decision. CSFX sees this as the key input into whether the ECB’s ~50%-priced second hike stays live. |
| Wed | ~09:30 CET | UK Flash Manufacturing, Services & Composite PMI (September) | HIGH | N/A | The main scheduled UK release of the week with the MPC off the calendar until November. Services carries the greater weight given its roughly 75% share of UK GDP. |
| Wed | ~13:45 CET | US Flash Manufacturing, Services & Composite PMI (September) | MED | N/A | Lands after the European close but sets the dollar tone into Thursday’s European session, particularly for EUR/USD and GBP/USD. |
| Thursday, 24 September | |||||
| Thu | ~07:30 CET | Swiss National Bank Interest Rate Decision & Statement | MED | Hold at 0.0% | A hold is priced with high confidence. CSFX watches the statement’s tone on franc strength and any hint of resumed easing, which can spill into broader European risk sentiment. |
| Thu | ~08:00 CET | SNB Press Conference (Chairman Martin Schlegel) | MED | N/A | Volatility in the franc typically surges during the press conference. A hawkish tone would be a modest broader-market signal that policymakers see limited regional risk-off pressure. |
| Thu | ~10:30 CET | Germany Ifo Business Climate Index (September) | HIGH | N/A | August’s 88.8 reading was Germany’s best since 2023. CSFX sees this as the week’s clearest test of whether Friday’s Volkswagen shock has dented broader German business sentiment. |
| Friday, 25 September | |||||
| Fri | All Day | UK GfK Consumer Confidence (September) | MED | N/A | August’s reading of -14 was the UK’s best in two years. CSFX watches whether that improvement held through a month of rising CPI and a divided Bank of England vote. |
| Fri | All Day | Week-End Positioning Ahead of Quarter-End | LOW | N/A | No other major European releases are scheduled. CSFX expects trading to be driven by the week’s accumulated PMI and Ifo data, alongside any residual headline flow from Tuesday’s Gulf summit. |
European Session — Trader Questions Answered
Key questions from CSFX clients ahead of Wednesday’s flash PMIs, Thursday’s Ifo release, and Tuesday’s Trump–Gulf leaders meeting
CSFX View: With the Central Banks Done for Now, Flash PMIs, Ifo and a Gulf Summit Set the Tone for the Week Ahead
The week of 21–25 September 2026 opens after a genuine central-bank super-week. The Federal Reserve raised rates 25 basis points to 3.75%–4.00% on 16 September in a unanimous vote, with a hawkish dot plot projecting a median 4.1% through 2027. The Bank of England held Bank Rate at 3.75% the following day in a divided 6–3 vote, the same three hawks dissenting for a second consecutive meeting as UK CPI rose to a five-month high of 3.1%. EUR/USD at 1.1478 and GBP/USD at 1.3394 both finished the week down roughly 1%, at their weakest levels since late July. European equities whipsawed through the aftermath: the DAX at 25,308.88 and STOXX 600 at 635.45 rallied on Thursday’s BoE relief before a Friday selloff led by a 5.6% slide in Volkswagen, while the FTSE 100 at 10,651.02 essentially round-tripped to finish the week almost exactly flat. Brent Crude at $103.21 has eased from a weekly high near $109.97 as Saudi Arabia reported progress restoring its damaged pipeline infrastructure.
With no Fed, BoE or ECB decision this week, Tuesday’s meeting between President Trump and Gulf Cooperation Council leaders in New York is the pivot point for the European session. Convened on the sidelines of the UN General Assembly to discuss a postwar framework for the Strait of Hormuz crisis, its outcome will likely determine whether Brent’s pullback from $110 holds or reverses — with direct consequences for the FTSE 100’s energy weighting and European inflation expectations. Wednesday brings flash PMI readings for Germany, the euro area and the UK in quick succession, the week’s most consequential scheduled data in the absence of a central bank meeting. Thursday carries both the Swiss National Bank’s rate decision, expected to be a straightforward hold at 0.0%, and Germany’s Ifo Business Climate index — a test of whether August’s best reading since 2023 survives Friday’s Volkswagen-led profit warning. Friday’s UK GfK consumer confidence print closes out a week with no scheduled UK data of note before then, leaving GBP/USD to trade primarily off broader dollar direction and Wednesday’s PMI ahead of the Bank of England’s next decision on 5 November.
CSFX’s key levels for the week: watch 1.1458 support and 1.1605 resistance on EUR/USD around Wednesday’s flash PMIs, and 1.3345 support and 1.3450 resistance on GBP/USD. The DAX is a watch between 25,296 support and 25,943 resistance into Thursday’s Ifo release, with the STOXX 600 tracking between 634.62 and 646.30 on the same driver. The FTSE 100 sits in a 10,594–10,868 range that CSFX expects Tuesday’s Gulf summit to resolve in one direction or the other, while Brent Crude trades between $101.98 support and $109.97 resistance as the Strait of Hormuz situation stays live. CSFX will issue intra-week alerts if the flash PMIs diverge materially from the recent Ifo trend, if Tuesday’s Trump–Gulf meeting produces a concrete framework or breaks down publicly, if the SNB statement signals a shift in policy stance, or if the Middle East situation escalates further. Follow all updates at capitalstreetfx.com.
For further reading, browse CSFX’s Weekly European market outlook archive, including previous European reports covering last week’s central-bank super-week.
New clients can also take advantage of a limited-time deposit bonus when they open an account this week, on top of the usual account benefits — tight spreads, high leverage, and access to 2000+ instruments across FX, commodities, indices, and crypto. Full terms and other promotions are available on the CSFX website.
Trade European Markets at CSFX →