Indices This Week | 26–30 October 2026
Hawkish Hold or Dovish Pause? The Fed, Microsoft, Alphabet and the ECB Set the Next Move for Global Indices
- Weekly bias
- Cautious, event-driven
- Dow resilient; Nasdaq 100, DAX and FTSE 100 test floors; Hang Seng weakest
- Expected volatility
- High
- UK Budget, Fed, Big Tech, GDP/PCE and ECB land within 25 hours
- Key event
- Fed decision
- Wednesday 28 Oct, 18:00 GMT
- Key pivot level
- 28,826
- Nasdaq 100 channel floor; a weekly close below it opens the 27,377 average
Market Overview
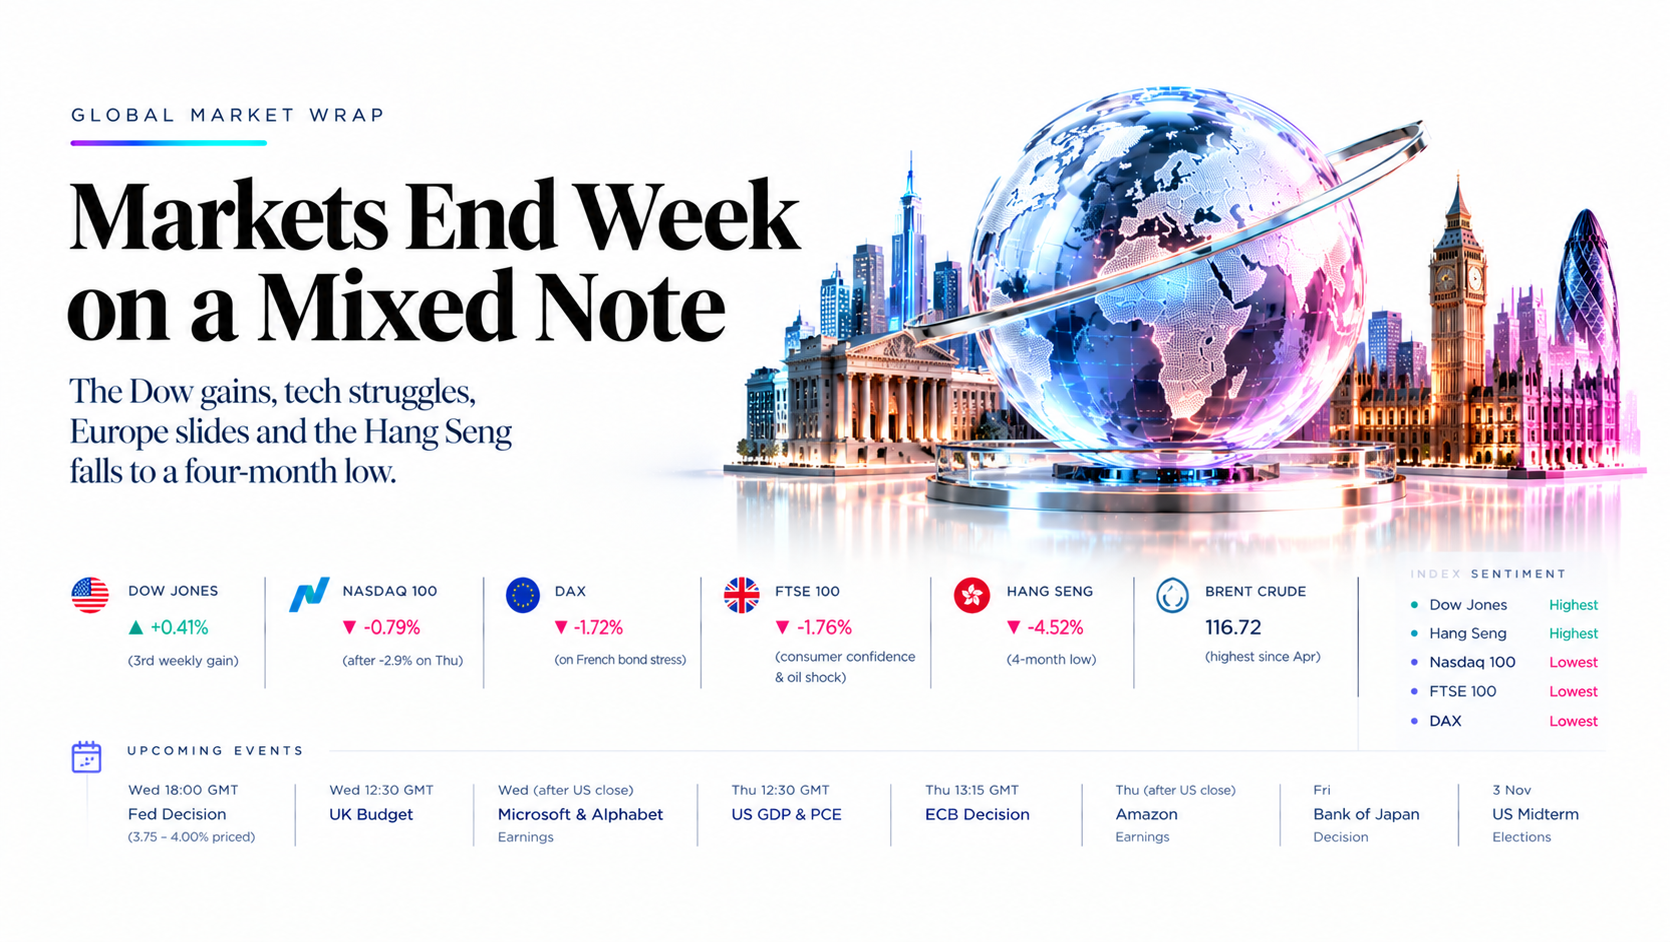
Global equities ended the week split between resilient blue chips and battered technology. The Dow gained 0.41% for a third straight weekly advance, even after falling 652.82 points on Friday as Brent crude settled at 116.72, its highest since late April. The Nasdaq 100 lost 0.79% after Thursday’s slide of about 2.9%, when Meta’s results and a 6.7% drop in the Philadelphia Semiconductor Index revived doubts about AI spending. In Europe the DAX fell 1.72% and the FTSE 100 1.76% on French bond stress, a collapse in UK consumer confidence and the oil shock, while the Hang Seng lost 4.52% to a four-month low on a tax-deadline sell-off and fading stimulus hopes.
The weekly charts show five different setups. The Dow and FTSE 100 are compressing inside triangles, the Nasdaq 100 and DAX sit on the floors of rising channels, and the Hang Seng is the only index below all three averages, with RSI at 35.92.
The Fed decides on Wednesday at 18:00 GMT, with a hold at 3.75–4.00% heavily priced and a December hike the real debate. The UK Budget lands about 12:30 GMT the same day, Microsoft and Alphabet report after the US close, and US GDP and PCE follow on Thursday at 12:30 GMT, then the ECB at 13:15 GMT and Amazon after the close. The Bank of Japan decides on Friday, and US midterm elections on 3 November sit behind headlines on possible renewed US–Israeli action against Iran. We rate the Dow and Hang Seng highest and the Nasdaq 100, FTSE 100 and DAX lowest because of event risk.
Key highlights
- Fed: A hold at 3.75–4.00% is about 93% priced on prediction markets, a December hike roughly 75–90%; the 10-year yield sits at 5.00%.
- Dow Jones: 52,215 holds beneath the 52,401 average and above 51,869; RSI is 55.52.
- Nasdaq 100: 28,958 sits on the channel floor at 28,826, capped by the 29,541 average; RSI is 50.41.
- FTSE 100 and DAX: The FTSE 100 holds the 10,672 average while the DAX holds above 24,737; Budget and ECB risk are both close.
- Hang Seng: 23,093 is below the 24,375, 24,591 and 25,425 averages with RSI at 35.92; the 22,518 June low is the key floor.
- Oil: Brent settled at 116.72 and WTI at 103.27; further gains would add to inflation fears and hike pricing.
Market Snapshot: Friday 23 October 2026 Close
Dow Jones Dow Jones Industrial Average (US30)
52,215.16
+212.75+0.41% week
Range 51,869.19–52,933.29
50,097.6952,933.29
Buy near 51,900Nasdaq 100 Nasdaq 100 Index (US100)
28,957.53
-230.02-0.79% week
Range 28,825.72–29,928.31
27,377.2029,928.31
Buy near 28,850FTSE 100 FTSE 100 Index (UK100)
10,690.37
-191.54-1.76% week
Range 10,630.00–10,889.90
10,382.4710,989.45
Buy near 10,640DAX 40 DAX 40 Index (GER40)
25,181.65
-440.96-1.72% week
Range 25,013.54–25,706.19
24,736.7725,706.19
Buy near 24,750Hang Seng Hang Seng Index (HK50)
23,093.37
-1,093.46-4.52% week
Range 22,803.77–24,139.11
22,518.0024,590.51
Sell near 23,800- Brent crude
- 116.72
- Settlement; highest since late April; WTI 103.27
- US 10-year yield
- about 5.00%
- Fell below 5% on Thursday for the first time in a month
- December Fed hike odds
- about 75–90%
- October hike odds near 7%
- VIX
- 19.45
- Dollar index 101.79
Prices are Friday closes from the TradingView weekly charts in this report, captured on 24 October 2026 at about 15:15 GMT. The Dow figure is the official close of 52,215.16; the chart feed shows 52,220.21. Weekly change is against the previous Friday close, and range shows the week’s high and low. The bar shows price between support 2 and resistance 2. Cash index prices can differ from CFD quotes.
Trade Setups for the Week
| Instrument | Direction | Entry | Stop | Target 1 | Target 2 | Reward:risk | Conviction |
|---|---|---|---|---|---|---|---|
| Dow Jones | Long | 51,900 | 51,200 | 52,930 | 54,000 | 1.5 / 3.0 | Medium |
| Nasdaq 100 | Long | 28,850 | 28,100 | 29,930 | 30,900 | 1.4 / 2.7 | Low |
| FTSE 100 | Long | 10,640 | 10,500 | 10,890 | 10,985 | 1.8 / 2.5 | Low |
| DAX 40 | Long | 24,750 | 24,050 | 25,700 | 26,500 | 1.4 / 2.5 | Low |
| Hang Seng | Short | 23,800 | 24,420 | 22,800 | 22,000 | 1.6 / 2.9 | Medium |
Reward:risk is the distance from entry to target 1 and target 2, divided by the distance from entry to the stop. Prices are index points. Levels are conditional technical references, not recommendations.
Key Market Drivers
A hold is priced, so December guidance decides
Fed funds stand at 3.75–4.00% after September’s hike. With only a small chance of an October move and a December hike widely expected, Chair Warsh’s statement and press conference matter more than the decision. Thursday’s PCE print lands after the Fed, so it works as confirmation of whatever bias the statement leaves.
Key events: Wednesday 28 October, decision at 18:00 GMT and press conference at 18:30 GMT; Thursday 29 October, GDP and PCE at 12:30 GMT.
Big Tech earnings test the AI trade
About one-third of the S&P 500 reports this week. Meta’s reaction showed that markets now penalise spending that outruns cash flow, and the semiconductor index is more than 26% below its June record close. Microsoft, Alphabet and Amazon capital spending guidance will set the direction for the Nasdaq 100 and the Dow.
Key events: Wednesday 28 October, Microsoft and Alphabet after the US close; Thursday 29 October, Amazon after the close.
Oil near $117 and Iran headlines set the risk tone
Brent has gained about 6% in a week on fears that US and Israeli strikes on Iran could resume after the 3 November midterms, plus Houthi attacks on Saudi Arabia. Higher oil feeds inflation, keeps hike odds up and lifts energy shares in London while hurting consumer-facing sectors.
Key events: Wednesday 28 October, EIA report at 14:30 GMT; Friday 30 October, Chevron and ExxonMobil results.
Regional stress points in Europe and China
France’s bond spread over Germany reached about 170 basis points, UK consumer confidence fell to -24 ahead of a Budget that may raise bank taxes, and Hong Kong faces a tax-deadline overhang with the CSI 300 in a bear market. The ECB, Bank of Japan and UK Budget each add local volatility.
Key events: Wednesday 28 October, UK Budget at about 12:30 GMT; Thursday 29 October, ECB at 13:15 GMT; Friday 30 October, Bank of Japan at about 03:00 GMT.
The Nasdaq 100 at 28,826 and the Hang Seng at 22,804 mark the two lines most exposed to the Fed and Big Tech. A weekly close beneath either would change the picture for the whole group.
Fed Scenario Analysis
Consensus is a hold at 3.75–4.00% following September’s 25 bp hike. The decision is due on Wednesday 28 October at 18:00 GMT, with the press conference at 18:30 GMT. Levels show technical reference points for each index.
Hawkish hold: dissent or a clear December signal
Higher yield expectations lift real rates and the dollar, pressuring equities with the 10-year yield already at 5.00%.
- Dow Jones51,869, then 50,098
- Nasdaq 10028,826, then 27,377
- FTSE 10010,630, then 10,382
- DAX 4025,014, then 24,737
- Hang Seng22,804, then 22,518
Dovish hold: pause with softer guidance
A lower yield path would support the technology-heavy indices and rate-sensitive Hong Kong shares.
- Dow Jones52,401, then 52,933
- Nasdaq 10029,541, then 29,928
- FTSE 10010,890, then 10,989
- DAX 4025,481, then 25,706
- Hang Seng24,375, then 24,591
DJIA | Dow Jones Industrial Average (US30)
Dow Jones Outlook: Triangle Holds as Defensives Offset an Oil Shock
52,215.16 +212.75 (+0.41%) week Range 51,869.19–52,933.29
Outlook: Bias is range-bound with a lean higher while 51,869 holds. The Dow closed at 52,215.16, 0.41% higher on the week and a third straight weekly gain, despite a 652.82-point fall on Friday as Brent settled at 116.72 and financials slid. Dips toward 51,900 are the zone to work from, and a weekly close above 52,933 would break the triangle upward.

Key levels
- Support 2
- 50,097.69
- Support 1
- 51,869.19
- Resistance 1
- 52,400.84
- Resistance 2
- 52,933.29
Weekly chart structure
- Pattern: a triangle between the falling line from the early-August record above 54,000 and the rising line from the March low near 45,000; price sits in the upper half and the apex is approaching.
- Averages: 52,400.84 caps from above, while 50,097.69 and 46,893.82 are layered support well below.
- Candle: bullish, opened 51,984.20, high 52,933.29, low 51,869.19, closed 52,215.16 (the chart feed shows 52,220.21), up 0.41%.
- Momentum: RSI 55.52 is below its 60.48 signal line but above 50, so momentum is positive but fading.
Key technical levels
51,869 is the weekly low and first pivot; a weekly close beneath it exposes the 50,098 average and the triangle floor. 52,401 is the short-term average and first resistance, then the 52,933 weekly high; a close above it would bring the 54,000 record zone back into play.
Fundamental drivers
Defensives, financials and oil
Friday’s slide was led by financials (American Express fell 3.7%, JPMorgan and Citigroup about 1.5% each) and defensive sectors, with nearly three in four S&P 500 stocks lower (AP). The Dow still beat the Nasdaq on the week as money rotated out of AI names.
Earnings and the Fed
Boeing and Coca-Cola report Tuesday, Microsoft Wednesday after the close, Caterpillar Thursday, Amazon Thursday after the close and Chevron Friday. The VIX closed at 19.45 and the 10-year yield sits at 5.00%, so a hawkish Fed would test the index.
Dow Jones trade setup
LongMedium conviction- Entry
- 51,900
- Stop loss
- 51,200
- Target 1
- 52,930
- Target 2
- 54,000
Risk 700 points. Reward:risk 1.5 to target 1, 3.0 to target 2.
Rationale: The triangle floor held through two heavy down days, the Dow has gained three weeks running and RSI is above 50. The stop sits beneath the 51,869 weekly low.
Invalidation: A daily close below 51,200. A hawkish Fed hold with weak Microsoft or Amazon guidance would likely send price to the 50,098 average.
NDX | Nasdaq 100 Index (US100)
Nasdaq 100 Outlook: Channel Floor Near 28,826 Meets Hyperscaler Earnings
28,957.53 -230.02 (-0.79%) week Range 28,825.72–29,928.31
Outlook: Bias is neutral to lower while 29,541 caps. The index closed at 28,957.53, 0.79% lower on the week, after Thursday’s slide of about 2.9% when Meta’s results and a 6.7% fall in the Philadelphia Semiconductor Index revived doubts about AI spending. Dips into 28,826 are a low-conviction buying zone ahead of Microsoft, Alphabet and Amazon.

Key levels
- Support 2
- 27,377.20
- Support 1
- 28,825.72
- Resistance 1
- 29,541.08
- Resistance 2
- 29,928.31
Weekly chart structure
- Pattern: a rising channel from the March low near 22,700; price sits on the lower line, which runs near 28,900 (read from the chart).
- Averages: 29,541.08 caps from above, while 27,377.20 and 24,690.10 sit below as deeper support.
- Candle: bearish, opened 29,539.31, high 29,928.31, low 28,825.72, closed 28,957.53, down 0.79%.
- Momentum: RSI 50.41 is under its 58.29 signal line and on the midpoint.
Key technical levels
28,826 is the weekly low and channel floor; a weekly close beneath it exposes the 27,377 average. 29,541 is first resistance and 29,928 the weekly high; a close above it would reopen the area near the recent highs around 31,000.
Fundamental drivers
Meta, chips and AI financing
Meta beat on revenue, up 26%, but posted its first cash outflow in over a decade and plans a 2-for-1 non-voting share issue; the stock fell about 7% (Reuters). The Philadelphia Semiconductor Index is more than 26% below its 22 June record close, and Lam Research lost about 10%.
Earnings and the Fed
Microsoft and Alphabet report Wednesday after the close, hours after the Fed, and Amazon follows Thursday. About one-third of the S&P 500 reports this week, and capital spending guidance is the focus (Reuters).
Nasdaq 100 trade setup
LongLow conviction- Entry
- 28,850
- Stop loss
- 28,100
- Target 1
- 29,930
- Target 2
- 30,900
Risk 750 points. Reward:risk 1.4 to target 1, 2.7 to target 2.
Rationale: The channel floor and the 28,826 weekly low align under price, and the stop sits beneath both. Earnings could re-rate the sector in either direction, which keeps conviction low.
Invalidation: A daily close below 28,100. A weekly close under 28,826 would also argue for stepping aside, with 27,377 next.
UKX | FTSE 100 Index (UK100)
FTSE 100 Outlook: Triangle Floor and the 10,672 Average Face Budget Day
10,690.37 -191.54 (-1.76%) week Range 10,630.00–10,889.90
Outlook: Bias is neutral while 10,630 holds. The FTSE 100 closed at 10,690.37, 1.76% lower on the week, as UK consumer confidence fell by the most since the pandemic and bank shares slid on tax fears, while energy majors cushioned the index. Dips toward 10,640 are the zone to work from, with Wednesday’s Budget the main risk.

Key levels
- Support 2
- 10,382.47
- Support 1
- 10,630.00
- Resistance 1
- 10,889.90
- Resistance 2
- 10,989.45
Weekly chart structure
- Pattern: a triangle between the falling line from the early-year high near 11,000 and the rising line from the March low near 9,750; price is close to the lower line.
- Averages: 10,671.91 sits right under price, while 10,382.47 and 9,592.27 are deeper support.
- Candle: bearish, opened 10,882.26, high 10,889.90, low 10,630.00, closed 10,690.37, down 1.76%.
- Momentum: RSI 53.43 is under its 57.47 signal line but still above 50.
Key technical levels
10,630 is the weekly low and triangle floor; a weekly close beneath it exposes the 10,382 average. 10,890 is the weekly high and triangle top, and a close above it would target the 10,989 52-week high.
Fundamental drivers
UK Budget and the Bank of England
Chancellor John Healey presents his first Budget on Wednesday at about 12:30 GMT, with reports of a bank surcharge rise from 3% to 8% and fiscal headroom put near £10–12 billion. The 10-year gilt yield is about 5.33%, UK inflation is 3.5% and the Bank of England is expected to raise rates on 5 November.
Consumers, oil and results
GfK confidence fell 11 points to -24 and September retail sales fell 0.4% against a 0.1% fall forecast. Rolls-Royce lost 7.5% on Friday, while Shell and BP gained about 4% as Brent rose. HSBC reports Tuesday, Lloyds Thursday and NatWest Friday; Shell and BP also report this week.
FTSE 100 trade setup
LongLow conviction- Entry
- 10,640
- Stop loss
- 10,500
- Target 1
- 10,890
- Target 2
- 10,985
Risk 140 points. Reward:risk 1.8 to target 1, 2.5 to target 2.
Rationale: The triangle floor, the weekly low and the 10,672 average cluster beneath price, giving a tight stop, while energy majors offset weakness in banks. Budget and Fed risk keep conviction low.
Invalidation: A daily close below 10,500. A harsher Budget with a bank-led sell-off could carry price to the 10,382 average.
DAX | DAX 40 Index (GER40)
DAX 40 Outlook: Rising Channel Holds Above 24,737 Ahead of the ECB
25,181.65 -440.96 (-1.72%) week Range 25,013.54–25,706.19
Outlook: Bias is neutral while 24,737 holds and 25,481 caps. The DAX closed at 25,181.65, 1.72% lower on the week, as French bond stress, oil near $117 and a global chip sell-off hit sentiment. Dips toward 24,750 are the zone to work from, with Germany’s Ifo survey on Monday and the ECB on Thursday as event risk.

Key levels
- Support 2
- 24,736.77
- Support 1
- 25,013.54
- Resistance 1
- 25,480.73
- Resistance 2
- 25,706.19
Weekly chart structure
- Pattern: a rising channel from the March low near 21,900; the lower line runs near 24,000 (read from the chart), with the top far above near 27,800.
- Averages: 25,480.73 caps from above, while 24,736.77 and 23,750.70 are layered support.
- Candle: bearish, opened 25,540.77, high 25,706.19, low 25,013.54, closed 25,181.65, down 1.72%.
- Momentum: RSI 49.68 is under its 55.88 signal line and at the midpoint.
Key technical levels
25,014 is the weekly low and first pivot; a weekly close beneath it exposes the 24,737 average and then the channel floor near 24,000. 25,481 is first resistance and 25,706 the weekly high; a close above it would reopen the late-August high near 26,600.
Fundamental drivers
France, inflation and the ECB
France’s OAT–Bund spread reached about 170 basis points, the widest since 2011, amid unrest over the budget. Euro-area inflation is 3.8% and the ECB is expected to hold its deposit rate at 2.50% on Thursday at 13:15 GMT, with most economists expecting a hike in December.
Chips and data
ASML, Infineon and STMicroelectronics fell 2% to 6% on Friday as the AI sell-off reached Europe. Ifo (prior 89.9, a three-year high) is due Monday at 09:30 GMT, German flash inflation Thursday at 13:00 GMT and euro-area GDP Friday at 10:00 GMT.
DAX 40 trade setup
LongLow conviction- Entry
- 24,750
- Stop loss
- 24,050
- Target 1
- 25,700
- Target 2
- 26,500
Risk 700 points. Reward:risk 1.4 to target 1, 2.5 to target 2.
Rationale: The 24,737 average and the channel floor sit beneath price, so a pullback there offers a defined stop under 24,050. Oil, French bond stress and the ECB keep conviction low.
Invalidation: A daily close below 24,050. A weekly close under 24,737 would argue for stepping aside, with 23,751 next.
HSI | Hang Seng Index (HK50)
Hang Seng Outlook: Four-Month Low Tests the 22,500 June Floor
23,093.37 -1,093.46 (-4.52%) week Range 22,803.77–24,139.11
Outlook: Bias is lower while 24,375 caps. The Hang Seng closed at 23,093.37, 4.52% lower on the week and below all three averages, after a 3.0% fall on Thursday on a tax-deadline sell-off and fading stimulus hopes. Rallies toward 23,800 are the zone to sell from, with 22,804 and the 22,518 June low as the first tests.

Key levels
- Support 2
- 22,518.00
- Support 1
- 22,803.77
- Resistance 1
- 24,375.30
- Resistance 2
- 24,590.51
Weekly chart structure
- Pattern: a falling channel from the January high near 28,056; the floor runs near 22,000 (read from the chart) and the June low at 22,518 sits just above it.
- Averages: price is below all three, with 24,375.30 and 24,590.51 overhead and 25,424.79 near the channel top.
- Candle: bearish, opened 23,990.05, high 24,139.11, low 22,803.77, closed 23,093.37, down 4.52%, the largest weekly fall of the five indices.
- Momentum: RSI 35.92 is under its 47.88 signal line and nearing oversold, so bounces can be sharp but short.
Key technical levels
22,804 is the weekly low and 22,518 the 52-week low from June; a weekly close beneath them points to the channel floor near 22,000. 24,375 is the nearest average and first resistance, then 24,591 and the 25,425 average near the channel top.
Fundamental drivers
Tax deadline, tech and stimulus
A 90-day transition for Beijing’s 20% income tax on offshore trusts ended, which Reuters said pushed large holders to sell liquid shares. The Hang Seng Tech Index fell 5.0% on Thursday to a two-year low, with Alibaba down 6.1% and Tencent 2.9%, then rebounded 2.05% on Friday. China’s 4.5% third-quarter growth and unchanged loan rates cut stimulus hopes, and the CSI 300 entered a bear market. One analyst sees a test of 22,500 before a recovery toward 24,000–24,500 by December (The Standard).
Fed, HSBC and the Bank of Japan
HSBC reports Tuesday, the Bank of Japan decides Friday at about 03:00 GMT and China’s official PMI follows on Saturday 31 October at about 01:30 GMT. Hong Kong rates track the Fed through the currency peg, so a hawkish hold adds pressure.
Hang Seng trade setup
ShortMedium conviction- Entry
- 23,800
- Stop loss
- 24,420
- Target 1
- 22,800
- Target 2
- 22,000
Risk 620 points. Reward:risk 1.6 to target 1, 2.9 to target 2.
Rationale: Price is below all three averages, RSI is under its signal line and 23,800 sits near the 20 October close of 23,868, so rallies there meet supply. The stop is above the 24,375 average.
Invalidation: A daily close above 24,420. Targeted Beijing stimulus or a dovish Fed hold could carry price toward 24,591.
Economic Calendar: 26–30 October 2026
| Date | Event | Market | Impact | Context |
|---|---|---|---|---|
| 09:30 GMT | Germany Ifo business climate (October) | DAX | Medium | Prior 89.9, a three-year high; a slip would add to ECB-week caution |
| 17:00 GMT | US 2-year note auction, $69 billion | Dow, Nasdaq 100 | Low | Front-end demand test with the 10-year yield at 5.00% |
| 01:30 GMT | China industrial profits (September); date approximate | Hang Seng | Medium | Growth read after the 4.5% third-quarter GDP print |
| Time TBC | HSBC third-quarter results | Hang Seng, FTSE 100 | Medium | Largest Hong Kong and UK bank; read on credit and offshore-wealth flows |
| Before US open | Boeing and Coca-Cola results | Dow | Medium | Two Dow members open the busiest earnings stretch of the season |
| 14:00 GMT | US consumer confidence (October) | Dow, Nasdaq 100 | Low | Sentiment read as oil nears $117 |
| About 12:30 GMT | UK Budget, Chancellor John Healey; time approximate | FTSE 100 | High | Reported bank surcharge rise to 8%; fiscal headroom near £10–12 billion; gilts in focus |
| 14:30 GMT | EIA weekly petroleum status report | All five | Medium | Oil swings are feeding inflation fears and hike odds |
| 18:00 GMT | Fed rate decision, hold at 3.75–4.00% expected; Chair Warsh press conference at 18:30 GMT | All five | High | December hike guidance decides risk assets; 10-year yield at 5.00% |
| After US close | Microsoft and Alphabet third-quarter results | Nasdaq 100, Dow | High | Capital spending guidance tests the AI trade after Meta’s reaction |
| Time TBC | Lloyds Banking Group third-quarter results; NatWest follows Friday | FTSE 100 | Medium | Banks report days after the Budget; surcharge risk in focus |
| 12:30 GMT | US advance Q3 GDP and September PCE inflation | All five | High | GDP seen near 3%; a hot core PCE would revive hike pricing |
| 13:00 GMT | German flash inflation (October) | DAX | Medium | Feeds the ECB December debate |
| 13:15 GMT | ECB rate decision, hold at 2.50% deposit rate expected; press conference at 13:45 GMT | DAX, FTSE 100 | High | Euro-area inflation at 3.8%; December hike signals matter |
| After US close | Amazon results; Caterpillar and Merck report before the open | Nasdaq 100, Dow | High | Cloud demand and spending plans; Amazon and Caterpillar are Dow members |
| About 03:00 GMT | Bank of Japan rate decision, hold at 1.25% expected; time approximate | Hang Seng, all | Medium | Core inflation back above target; yen and carry flows |
| 10:00 GMT | Euro-area Q3 GDP, flash estimate | DAX, FTSE 100 | Medium | Growth read under an energy shock |
| Before US open | Chevron and ExxonMobil results | Dow, FTSE 100 | Medium | Oil majors with Brent near $117 |
| 01:30 GMT | China official manufacturing PMI (October); approximate | Hang Seng | Medium | Sets the Monday 1 November Hong Kong open at 01:30 GMT |
All times are GMT. UK and euro-area clocks go back on Sunday 25 October, so London and Frankfurt now trade on GMT; the US stays on daylight saving until 1 November, so 08:30 ET releases fall at 12:30 GMT this week. Cash sessions run 08:00–16:30 GMT in London and Frankfurt, 13:30–20:00 GMT in New York and 01:30–08:00 GMT in Hong Kong, with a lunch break from 04:00 to 05:00 GMT. Earnings and several release times are approximate.
Conclusion
The Fed, Big Tech earnings and Thursday’s inflation data set the theme, with oil headlines driving the days between. A hawkish hold would test the Nasdaq 100 at 28,826, the Dow at 51,869 and the DAX at 25,014, while a dovish one could lift all four western indices toward their first resistance levels and give the Hang Seng room to bounce.
On conviction, the Dow and Hang Seng rank medium, with the Nasdaq 100, FTSE 100 and DAX at low because of Big Tech, Budget and ECB event risk. The Hang Seng is the only short, reflecting its position below all three averages.
We treat every level as conditional, let the event windows pass before adding exposure and size positions so that a stop-out is affordable. Spreads can widen sharply around the Fed announcement and the UK Budget, and Monday gaps can skip stops.
| Instrument | Bias | Key level | Targets | Invalidation | Principal risk |
|---|---|---|---|---|---|
| Dow Jones | Buy near 51,900 | 51,869 | 52,930 / 54,000 | Below 51,200 | Hawkish Fed, hyperscaler guidance |
| Nasdaq 100 | Buy near 28,850 | 28,826 | 29,930 / 30,900 | Below 28,100 | AI spending doubts, hawkish Fed |
| FTSE 100 | Buy near 10,640 | 10,630 | 10,890 / 10,985 | Below 10,500 | Budget bank tax, oil, BoE hike |
| DAX 40 | Buy near 24,750 | 24,737 | 25,700 / 26,500 | Below 24,050 | French bond stress, ECB tone |
| Hang Seng | Sell near 23,800 | 24,375 | 22,800 / 22,000 | Above 24,420 | Beijing stimulus, oversold bounce |
Trade Dow Jones, Nasdaq 100, FTSE 100, DAX 40 and Hang Seng CFDs with Capital Street FX.
Frequently Asked Questions
Which events matter most for stock indices this week?
The Fed decision on Wednesday at 18:00 GMT, the UK Budget at about 12:30 GMT the same day, Microsoft and Alphabet results after the US close, then US GDP and PCE at 12:30 GMT and the ECB at 13:15 GMT on Thursday. Amazon reports Thursday after the close and the Bank of Japan decides early Friday.
Will the Fed change rates on 28 October?
Markets expect no change: prediction markets put a hike near 7%, and 94 of 100 economists in a Reuters poll expect a hold at 3.75–4.00%. All 100 expect a hike in December, so Chair Kevin Warsh’s tone matters more than the decision.
Why did the Nasdaq 100 fall on Thursday?
Meta’s results showed a first cash outflow in more than a decade and plans for a non-voting share issue, reviving doubts over AI spending. The Philadelphia Semiconductor Index fell 6.7% and the Nasdaq Composite lost 2.6%, its worst day since June.
Why did the Hang Seng fall to a four-month low?
A tax-reporting deadline on offshore trusts, fading hopes of Beijing stimulus after 4.5% GDP growth and a global tech sell-off drove a 3.0% fall on Thursday. The index rebounded 0.69% on Friday but lost 4.52% on the week.
How could the UK Budget affect the FTSE 100?
Reports suggest a higher bank surcharge, which would weigh on Lloyds and NatWest, while gilt yields and the Bank of England’s expected 5 November hike shape the domestic outlook. Energy majors such as Shell and BP offer support while Brent stays near $117.
How can traders manage risk in a Fed week?
Reduce position size before the decision, avoid new entries in the minutes around it and allow for wider spreads. Index markets are closed over the weekend, so gaps at the Monday open, especially in Hong Kong at 01:30 GMT, can skip stops.