Kospi Falls on Alibaba & Samsung Selloff | Technical Analysis | Asian Session | 24 August 2026
Alibaba Placement and Samsung Payout Disappointment Spark Asia Tech Selloff as Kospi Drops 2.5% and the Yen Holds Firm Ahead of Nvidia Earnings and Jackson Hole
USD/JPY · EUR/JPY · Aluminium · Corn · Hang Seng · Litecoin · Solana — live Asian market outlook today, updated through the trading session
Asian Market News — Live Now, 24 August 2026
Top-moving headlines shaping the Asian market outlook today, updated through the morning
Hang Seng Slides 2.1% as Alibaba’s $10.2bn Placement Revives Dilution Fears
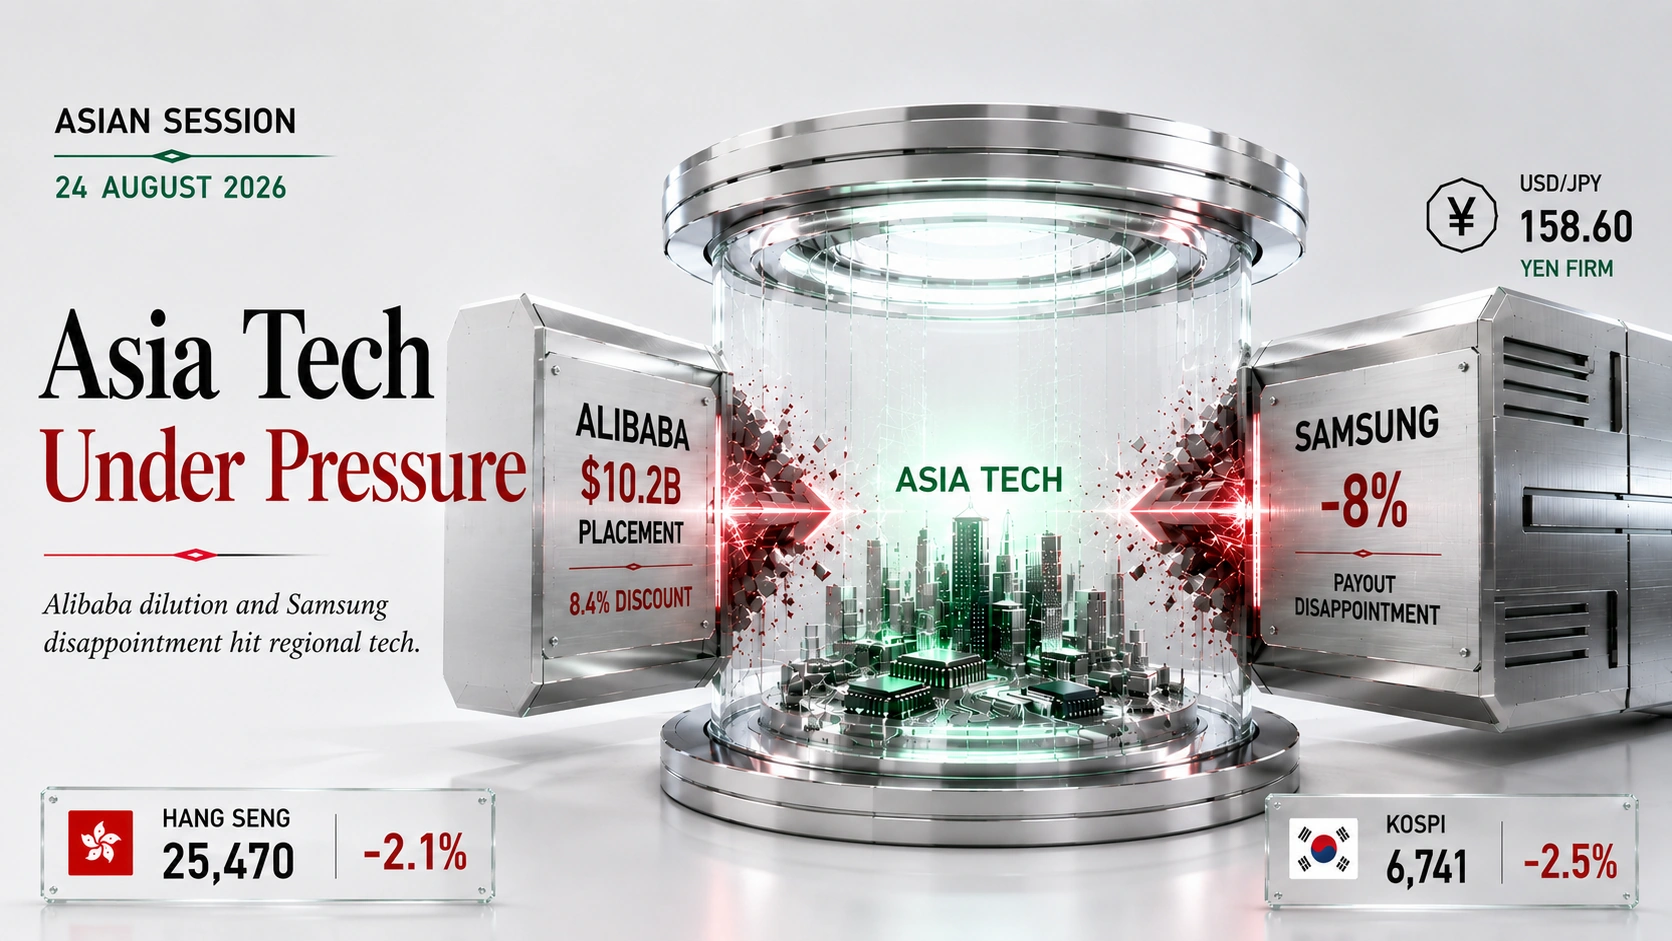
The Hang Seng Index has dropped roughly 2.1%, or over 500 points, to near 25,470 on Monday after Alibaba Group priced a 710-million-share Hong Kong placement at HK$112.70, an 8.4% discount to Friday’s close, to raise HK$80 billion ($10.2bn) for its AI and infrastructure build-out; the deal is expected to close 26 August, and investors are weighing near-term dilution against longer-run AI capex. Tencent and other large-cap tech names are also under pressure, while Shein has separately launched bookbuilding for its own Hong Kong IPO.
EquitiesKospi Drops 2.5% as Samsung Falls 8% Despite Record Payout Pledge
South Korea’s Kospi is down about 2.5% to near 6,741 after Samsung Electronics fell as much as 8% even after its board approved a record KRW90-110 trillion ($65-80bn) 2026 shareholder-return plan — roughly five times its prior record — including some KRW30 trillion of Q3 cash dividends and a KRW15 trillion buyback for employee compensation; analysts note the plan lacks the buyback-and-cancellation timetable that powered last week’s SK Hynix-led rally, leaving the payout looking underwhelming by comparison. SK Hynix itself was little-changed on the day.
EquitiesUSD/JPY Forecast Today: Yen Holds Near Multi-Week Lows as Pair Turns Oversold
USD/JPY is consolidating near 158.6 during the Asian session, having slipped from last week’s highs as the Japanese Yen firmed broadly; the daily RSI near 28 signals the pair is technically oversold after its pullback, with support building in the 156-157 zone. BOJ Governor Kazuo Ueda has continued to signal that further rate hikes remain on the table depending on inflation and financial-conditions data, keeping two-way risk alive for the Japanese Yen outlook this week into Friday’s Jackson Hole symposium.
FXCorn Holds Near 13-Week Highs on Crop Tour Drought Signals and Black Sea Risk
Corn futures are holding above 519¢/bushel, at a fresh multi-month high, after the Pro Farmer Crop Tour flagged drought damage in South Dakota and uneven crop maturity in Ohio, raising doubts over the USDA’s 180.7 bushels-per-acre yield estimate; USDA’s Crop Progress report showed the share of the US crop rated good-to-excellent slipping to 60% from 61%. Renewed attacks disrupting Black Sea grain shipments and a historically poor French harvest are adding a fresh geopolitical and weather premium to the broader grains complex.
CommoditiesAluminium Holds Above $3,200/t as Middle East Supply Disruption Lingers
Aluminium is trading near $3,248.95/tonne on the LME, holding most of last week’s gains after Norsk Hydro’s Brazilian Alunorte alumina refinery was forced to half capacity on a natural-gas shortfall and its Qatari Qatalum joint venture separately declared force majeure; scarce LNG supply tied to tanker disruption around the Middle East continues to squeeze refiners, even as Emirates Global Aluminium works to restore its Al Taweelah smelter. The broader base-metals complex, including Copper, remains similarly underpinned by the same energy and logistics squeeze.
CommoditiesSolana and Litecoin Soften as Tech-Led Risk Aversion Spreads to Crypto
Solana is easing toward the low-$90s, down close to 2% over the past 24 hours, while Litecoin drifts back toward the low-$50s, as the same risk-off tone weighing on Hong Kong and Korean tech stocks spills modestly into digital assets; Solana’s medium-term picture remains constructive, with continuing spot-ETF inflows from issuers including Bitwise and Fidelity providing an offsetting bid on dips.
CryptoLive · Updated through the Asian morning session, Monday 24 August 2026
Asian Economic Calendar This Week — 24 August 2026
Key releases and events shaping price action through the week
| Time | Event | Forecast / Detail | Impact | Market Read |
|---|---|---|---|---|
| 🇭🇰Today (Asian Morning) | Alibaba $10.2bn Hong Kong Share Placement | 710m shares priced at HK$112.70, an 8.4% discount; closing expected 26 August | 🔴 CRITICAL | The session’s single biggest driver of Hang Seng weakness on dilution concerns |
| 🇰🇷Today (Asian Morning) | Samsung Electronics 2026 Shareholder Return Plan | KRW90-110tn pledged, but no buyback-cancellation timetable disclosed | 🔴 CRITICAL | Shares fall despite a record payout as the market compares it unfavourably to SK Hynix |
| 🇳🇸Ongoing | Kospi and Kosdaq Under Pressure | Kospi down ~2.5% to near 6,741 on Samsung-led weakness | 🟢 MEDIUM | Stock-specific rather than macro-driven; SK Hynix largely unaffected |
| 🇳🇵Wednesday, 26 August | Japan Tokyo CPI & Regional Data Flow | Markets continue to price a gradual BOJ tightening path into autumn | 🟢 MEDIUM | Any upside inflation surprise would reinforce BOJ rate-hike expectations and support the Yen |
| 🇺🇸Wednesday, 26 August (After Close) | Nvidia Q2 FY2027 Earnings | Consensus revenue near $93-95bn; guidance was ~$91bn +/-2% | 🔴 CRITICAL | The week’s single biggest catalyst for global AI-infrastructure sentiment and risk appetite |
| 🇺🇸Wednesday, 26 August | US Q2 GDP Second Estimate & July PCE | Final data checkpoint before Warsh’s Jackson Hole keynote | 🔴 CRITICAL | Last major print shaping September rate-hike odds, currently near one-in-three |
| 🇺🇸Thu-Sat, 27-29 August | Jackson Hole Economic Policy Symposium | Theme: “Financial Innovation: Implications for Payments and Policy” | 🔴 CRITICAL | Roughly 120 central bankers from 70-plus countries gather; sets the tone into September FOMC |
| 🇺🇸Friday, 28 August | Fed Chair Kevin Warsh’s First Jackson Hole Keynote | 10:00am ET at Jackson Lake Lodge, Wyoming | 🔴 CRITICAL | Seen as the single biggest swing factor for the Dollar, the Yen and global risk appetite this week |
Asian Session Trade Ideas — USD/JPY Forecast Today and More
Technical setups and fundamental context across the session’s seven key instruments
USD/JPY

Fundamental Backdrop
USD/JPY is consolidating near 158.60 during the Asian session after a pullback from last week’s highs left the Japanese Yen firmer across the board. BOJ Governor Kazuo Ueda has continued signalling that further rate hikes remain plausible depending on inflation and financial-conditions data, while the wide US-Japan policy-rate differential still underpins the broader carry trade. Wednesday’s Nvidia earnings and Friday’s Jackson Hole keynote from Fed Chair Kevin Warsh are the clearest near-term swing factors for the pair.
Technical Outlook
The daily RSI near 28 points to oversold conditions after the recent slide, hinting at scope for a near-term relief bounce. Support sits in the 156-157 zone, with a confirmed break below opening 153-154; on the upside, a reclaim of the 160-162 resistance band would put the pair’s prior range highs back in focus, with the BOJ’s rate-hike trajectory and Friday’s Jackson Hole keynote the key sources of two-way risk for the Japanese Yen forecast this week.
EUR/JPY

Fundamental Backdrop
EUR/JPY is holding near 185.80, extending a multi-week bullish run as the cross benefits from the same broad Yen dynamics working through USD/JPY, alongside a steadier Euro backdrop. The pair has climbed from a mid-February low near 181.25, and remains supported above its 50- and 100-day moving averages, with little fresh Eurozone-specific data due to disturb the trend this week.
Technical Outlook
Momentum remains constructive with the pair trading above its short and medium-term moving averages, though stochastics are flagging overbought conditions that could produce a shallow pullback before the next leg higher. A confirmed break above 186.25 would open the door toward 187.50, while a slip back below 184.50 support risks a retreat toward 183.00, with Yen-wide catalysts, including Friday’s Jackson Hole keynote, the key swing factor.
Aluminium

Fundamental Backdrop
Aluminium is trading near $3,248.95/tonne on the LME, holding most of last week’s gains as Middle East-linked LNG disruption continues to squeeze smelters and refiners: Norsk Hydro’s Brazilian Alunorte alumina plant has been forced to half capacity on a natural-gas shortfall, while its Qatari Qatalum joint venture has separately declared force majeure. Emirates Global Aluminium is working to restore its Al Taweelah smelter, and China’s continued export push against its 45-million-tonne output cap is a partial offset, but the broader base-metals complex, including Copper, remains similarly underpinned by the same energy and logistics squeeze.
Technical Outlook
Prices remain well within this year’s elevated range, up sharply from the 2025 average near $2,605/tonne, though still short of the 2022 record above $4,000. A confirmed break above $3,380 would open the path toward the June highs near $3,750, while a slip back below $3,180 risks a retreat toward $3,090, with the pace of Gulf smelter restarts and Chinese export flows the clearest sources of two-way risk this week.
Corn

Fundamental Backdrop
Corn futures are holding above 519¢/bushel, at a fresh multi-month high, as traders weigh fresh crop assessments from the Pro Farmer Crop Tour alongside robust export demand. Early field observations pointed to drought damage in South Dakota and uneven crop maturity in Ohio, raising doubts the USDA’s 180.7 bushels-per-acre yield estimate can hold, while USDA’s Crop Progress report showed the share of the US crop rated good-to-excellent slipping to 60% from 61% a week earlier. Renewed Black Sea shipping attacks and a historically weak French harvest are adding a fresh geopolitical and weather premium.
Technical Outlook
The rally to fresh multi-month highs has flipped short-term momentum firmly bullish after a prolonged period of oversupply-driven weakness earlier in the year. A confirmed break above 530¢ would expose the 545-555¢ zone, while a slip back below 508¢ support risks a retreat toward 495¢, with the remainder of the Crop Tour findings and any Black Sea de-escalation the clearest sources of two-way risk this week.
Hang Seng

Fundamental Backdrop
The Hang Seng is down around 2.1% to near 25,470, led lower by technology stocks after Alibaba priced a 710-million-share Hong Kong placement at HK$112.70, an 8.4% discount to Friday’s close, to raise HK$80 billion ($10.2bn) for AI and infrastructure spending; the deal, expected to close 26 August, has revived investor concerns over near-term share dilution even as it funds longer-run AI capex. The pressure has broadened from Friday’s Korean payout disappointment into a Hong Kong dilution-and-capex debate, with Tencent also under pressure and Shein’s competing Hong Kong IPO bookbuild adding to the supply of new paper.
Technical Outlook
Today’s decline pulls the index back from a run of gains, with the Hang Seng Tech sub-index also lower after last week’s mixed performance. A confirmed break below 24,950 would expose the 24,700 area, while a reclaim of 25,780 would put the recent range highs near 26,200-26,600 back in focus, with Wednesday’s Nvidia earnings the clearest swing factor for AI-linked sentiment across the whole complex this week.
Litecoin

Fundamental Backdrop
Litecoin is trading near $51.40, drifting back toward the lower end of its recent range as the same risk-off impulse weighing on Hong Kong and Korean tech stocks spills modestly into digital assets. The token has shown resilience over the past week on a broader crypto bid, but momentum has cooled as trading volumes have pulled back from recent peaks, leaving it more exposed to swings in broader risk sentiment than assets with dedicated ETF-driven demand.
Technical Outlook
LTC remains inside a broad $47-55 consolidation range that has held for several weeks, with the asset still trading well below its prior highs. A confirmed break below $47.50 would expose the low-$40s, while a reclaim of $53.60 would put the mid-$50s resistance zone back in focus, with the broader tech-and-crypto risk tone into Nvidia’s earnings the clearest source of two-way risk this week.
Solana

Fundamental Backdrop
Solana is trading near $92.50, easing about 2% over the past 24 hours as the tech-led risk-off tone in Asian equities spills into crypto, but the medium-term picture remains constructive: spot Solana ETFs from issuers including Bitwise and Fidelity have continued to see inflows, Forward Industries’ Solana-focused corporate treasury now holds over 6.9 million SOL, and network activity metrics remain firm despite a brief validator disruption earlier this month that has since been resolved.
Technical Outlook
SOL has reclaimed its 20- and 50-day EMAs on the recent rebound, keeping the broader structure constructive after a sharp pullback from its highs earlier in the year. A confirmed break above $96.50 would expose the $99.50 area and the 100-day EMA near $99, while a slip back below $88.00 risks a retest of the mid-$80s, with Wednesday’s Nvidia earnings and the broader risk tone into Jackson Hole the clearest sources of two-way risk this week.
Asian Session FAQ
Answers to the questions traders are asking about today’s Asia stock market outlook
Why is the Hang Seng down over 2% today?
Why did Samsung Electronics fall despite announcing a record shareholder return?
What is the USD/JPY forecast today, and why does the pair look oversold?
Why is Corn trading near 13-week highs?
What should traders watch for the rest of the week?
Asian Session Summary — Monday, 24 August 2026 (Live Update)
Monday’s Asian session has turned selectively risk-off as company-specific setbacks in Hong Kong and Korean technology stocks overwhelm an otherwise quiet macro tape ahead of a heavy catalyst-laden week. The Hang Seng near 25,470 is down roughly 2.1% after Alibaba priced a US$10.2 billion Hong Kong share placement at an 8.4% discount, reviving dilution concerns just as Samsung Electronics fell as much as 8% despite unveiling a record KRW90-110 trillion 2026 shareholder-return plan, with South Korea’s Kospi down about 2.5% to near 6,741. The Nikkei near 66,037 and the Shanghai Composite are comparatively little-changed, underscoring that today’s pressure is concentrated rather than broad-based. The Japanese Yen is holding firm, with USD/JPY consolidating near 158.60 in technically oversold territory after last week’s slide, while EUR/JPY near 185.80 continues to grind higher within its recent bullish range. In commodities, Corn near 519.00¢/bushel is holding at fresh multi-month highs on Pro Farmer Crop Tour drought findings and a fresh Black Sea escalation, while Aluminium near $3,248.95/tonne holds elevated on lingering Middle East-linked supply disruption, with the broader base-metals complex, including Copper, similarly underpinned. Crypto markets are softer in sympathy, with Solana near $92.50 and Litecoin near $51.40 both easing modestly. Highest-conviction session idea: fade Hang Seng and Kospi-proxy rallies into the Alibaba-and-Samsung overhang, but size cautiously — Wednesday’s Nvidia earnings and Friday’s Jackson Hole keynote from Fed Chair Kevin Warsh are genuine sources of two-way risk that could overwhelm today’s stock-specific story.
For the individual instruments: USD/JPY buy dips toward 157.20, stop 155.70, target 160.80 — oversold daily momentum is a genuine tailwind for a relief bounce, though BOJ rate-hike rhetoric and Friday’s Jackson Hole keynote are a real source of two-way risk. EUR/JPY buy dips toward 184.50, stop 183.00, target 187.50 — the established bullish trend is a genuine tailwind, though overbought stochastics and broad Yen catalysts are a real source of two-way risk. Aluminium buy dips toward $3,180, stop $3,090, target $3,400 — lingering Middle East-linked smelter disruption is a genuine tailwind, though the pace of Gulf restarts is a real source of two-way risk. Corn buy dips toward 508.00¢, stop 495.00¢, target 545.00¢ — Crop Tour drought findings and Black Sea risk are a genuine tailwind, though any harvest upgrade is a real source of two-way risk. Hang Seng sell rallies toward 25,780, stop 26,150, target 24,700 — the Alibaba dilution overhang is a genuine headwind, though Wednesday’s Nvidia earnings are a real source of two-way risk. Litecoin sell rallies toward $53.60, stop $55.20, target $47.50 — tech-led risk aversion is a genuine headwind, though a broader crypto bid remains a real source of two-way risk. Solana buy dips toward $88.00, stop $84.00, target $99.50 — sustained ETF inflows are a genuine tailwind, though near-term risk-off spillover is a real source of two-way risk. The decisive variables for the remainder of the week are Wednesday’s Nvidia Q2 FY2027 earnings and US Q2 GDP/PCE data, followed by Fed Chair Kevin Warsh’s first Jackson Hole keynote on Friday, 28 August, alongside the ongoing BOJ rate-hike trajectory shaping the Japanese Yen forecast this week. Size positions accordingly, and note that today’s backdrop carries genuine event risk that could reshape sentiment sharply as the week progresses.
Ready to act on today’s setups? Open an Account with Capital Street FX and trade every instrument covered in this report on our Zero Account‘s 0.0 Pips Spreads and 1:10000 Leverage, across 2000+ Instruments, with a welcome deposit bonus and 24/7 Live Support on hand for every session.
Not sure which account fits your style? Compare our Account Types side by side with our Account Comparison tool, browse current Promotions / Bonus offers, and trade from our Trading Platform suite. Funding is simple via our Deposit & Withdrawal options. For ongoing coverage, explore our Forex Analysis Pages, Commodity Analysis Pages and Crypto Analysis Pages, plus our Daily Market Analysis and Weekly Market Analysis reports and the full Economic Calendar. New to trading? Visit our Trading Education / Blog, or reach our Contact Us / Live Support team any time.
Access Live Asian Markets →