Oil Near $97 and Bund Yields Creep Higher as AfD’s Historic Win Rattles Europe Ahead of Thursday’s ECB Hike | Technical Analysis – European Session | 07-September-2026
Oil Near $97 and Bund Yields Creep Higher as AfD’s Historic Win Rattles Europe Ahead of Thursday’s ECB Hike
EUR/USD · GBP/JPY · EUR/CHF · Silver · Crude Oil · DAX · EU 10Y · BNB · ETH/USD — live European market outlook today, updated through the trading session
European Session Live News — Monday, 7 September 2026
The headlines moving European FX, equities, rates, commodities and crypto right now
AfD Wins Historic Regional Election, German Bund Yields Edge Higher
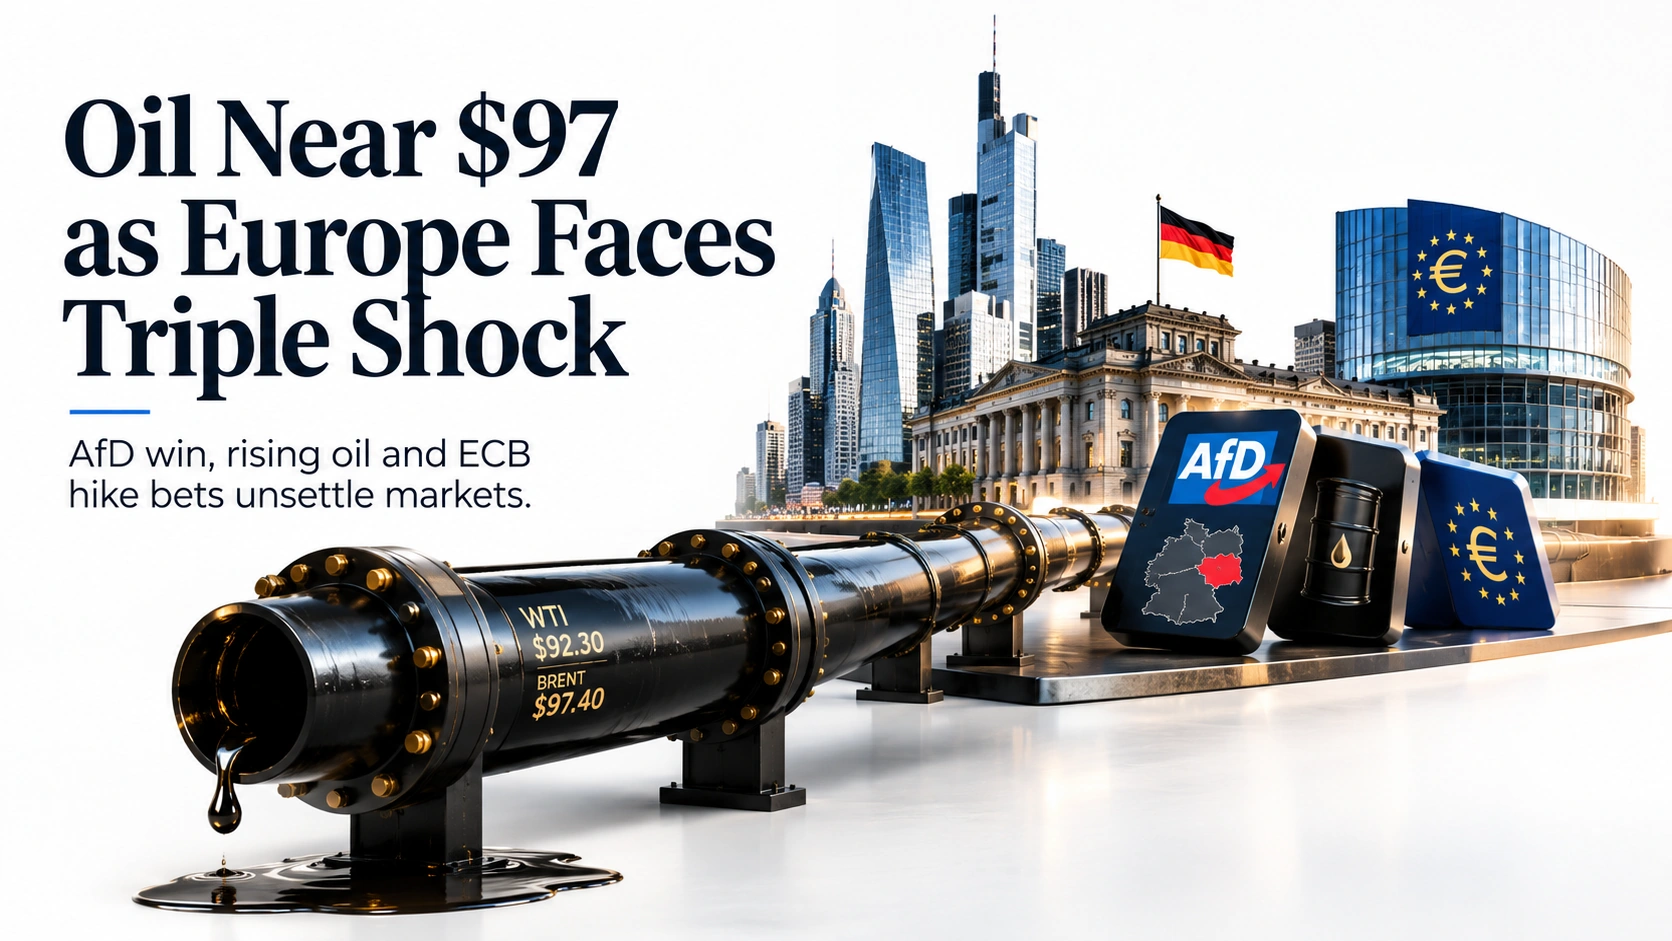
Germany’s far-right Alternative for Germany party topped Sunday’s Saxony-Anhalt state election with roughly 44% of the vote, the closest a far-right party has come to leading a German state government since the Second World War. The 10-year Bund yield is a basis point higher near 3.35%, its highest level in years, as investors price a modest political risk premium into German assets.
PoliticsOil Holds Near $97 as US-Iran Strikes Continue Into the European Open
Brent crude is trading near $97.40 a barrel and WTI near $92.30 after the US struck three Iranian oil tankers over the weekend and Tehran retaliated by hitting vessels linked to Washington, with Iran threatening a restricted maritime zone beyond the Strait of Hormuz. Both benchmarks are near their highest levels since July, extending last week’s near 8-10% surge.
GeopoliticsECB Widely Expected to Hike to 2.50% on Thursday
Markets are pricing close to a 95% probability of a 25-basis-point ECB hike on Thursday, taking the deposit rate to 2.50%, after eurozone inflation climbed back above 3% in August on higher energy costs. Economists broadly expect this to be the final hike of the cycle, but rates markets are pricing roughly two more moves within a year, leaving Thursday’s guidance as the session’s key swing factor.
Central BanksEuropean Stocks Slip as DAX Leads Losses, Nordex Soars 11%
The Stoxx 600 has dipped close to 0.1% in morning trade, with Germany’s DAX leading regional losses, down about 0.14% near 26,046, while the FTSE 100 and CAC 40 are also lower and Italy’s FTSE MIB outperforms with a 0.37% gain. German wind turbine maker Nordex has jumped more than 11% after a Bank of America upgrade to Buy.
EquitiesEuro Holds Above 1.1600 Despite Hawkish US Jobs Data and Weak German Output
EUR/USD is trading firmly above 1.1600 near 1.1620 even as Fed rate-hike odds for September 16 have climbed to near 58% following Friday’s blowout US payrolls report. German industrial production data released this morning showed factory output contracting 1.6% year-on-year, but the pair has largely shrugged it off with traders’ focus fixed on Thursday’s ECB decision.
FXSilver Eases Toward $66 as Fed Bets Lift Yields, BNB Pulls Back From Weekly Highs
Silver has eased to around $66.20 an ounce, giving back part of last week’s advance as firmer Treasury yields and a stronger Dollar reduce the near-term appeal of precious metals, though the metal remains up roughly 60% year-on-year. In crypto, BNB has pulled back about 1.8% to near $743 after last week’s near 9% rally, while ETH consolidates just under resistance near $2,560.
Commodities & CryptoLast refreshed during the European morning session, Monday 7 September 2026 · cross-checked against Reuters, Investing.com, Bloomberg and FXStreet
European Session Overview
“The European Central Bank is widely expected to hike interest rates on Thursday, erring on the side of caution as the U.S.-Iran war drags on, keeping oil prices high and raising inflation again.” — Reuters
European markets have opened the week digesting a historic domestic political shock alongside a fast-moving external one. Germany’s far-right AfD topped Sunday’s Saxony-Anhalt state election with roughly 44% of the vote, its strongest regional result yet and a significant setback for Chancellor Friedrich Merz’s coalition-building efforts nationally. The reaction in German assets has been contained rather than disorderly so far: the DAX is down a modest 0.14% near 26,046 and 10-year Bund yields are only a basis point higher near 3.35%, though strategists are flagging a gradual political risk premium building into German industrial and financial names as investors weigh the prospect of more fragmented state governments heading into further votes later this month. The broader Stoxx 600 is down close to 0.1%, with the FTSE 100 and CAC 40 both softer while Italy’s FTSE MIB bucks the trend, helped by a sharp rally in wind turbine maker Nordex after a broker upgrade.
Energy markets remain the dominant macro driver carried over from the Asian session, with Brent crude near $97.40 a barrel and WTI near $92.30 after the weekend’s exchange of strikes between the US and Iran, both close to their highest levels since July. That backdrop is central to Thursday’s ECB decision: a 25-basis-point hike to a 2.50% deposit rate is priced with close to 95% certainty after eurozone inflation pushed back above 3% in August on higher energy costs, though economists are split on whether it will be the last hike of the cycle or the start of a longer tightening run. EUR/USD is holding firmly above 1.1600 near 1.1620 despite Fed hike odds climbing to near 58% for September 16, while GBP/JPY and EUR/CHF are both trading with a cautious, safe-haven-influenced tone as the Middle East conflict keeps volatility elevated. Silver has eased back toward $66 an ounce on firmer yields, and crypto majors BNB and ETH are consolidating after last week’s strong gains.
European Session Economic Calendar — 7 September 2026
Key releases and events shaping price action through the rest of the day
| Time | Event | Forecast / Detail | Impact | Market Read |
|---|---|---|---|---|
| 🇩🇪Weekend (Released) | AfD Wins Saxony-Anhalt State Election | Far-right party takes roughly 44% of the vote, falling just short of an outright majority | 🔴 CRITICAL | German Bund yields fractionally higher near 3.35%; DAX leads a modest Stoxx 600 decline |
| 🇩🇪06:00 GMT (Released) | German Industrial Production (Jul) | Factory output contracts 1.6% year-on-year, worse than June’s -0.5% pace | 🟢 MEDIUM | Euro largely shrugs it off, holding above 1.1600 with focus on Thursday’s ECB decision |
| 🇪🇺09:00 GMT | Eurozone Final Q2 GDP | Expected to confirm 0.4% quarter-on-quarter growth | 🟢 MEDIUM | A confirmation would support the case for the ECB proceeding with Thursday’s hike |
| 🇺🇸All Day (Ongoing) | US-Iran Conflict Continues Into the European Session | Iran has signalled a “restricted” maritime zone beyond the Strait of Hormuz in the coming days | 🔴 CRITICAL | Keeps Brent near $97.40 and WTI near $92.30, both close to their highest since July |
| 🇪🇺Thursday, 10 September | ECB Interest Rate Decision and Lagarde Press Conference | 25bp hike to a 2.50% deposit rate priced with close to 95% certainty; guidance beyond September is the key swing factor | 🔴 CRITICAL | A hawkish tone would support the euro and Bund yields further; a cautious one could unwind recent gains |
| 🇬🇧Ongoing (Rates Market) | Bank of England Policy Backdrop | UK rates seen on hold near-term as markets focus on BOJ and Fed hike odds driving yen and dollar crosses | 🟢 MEDIUM | Keeps GBP/JPY volatile alongside the hawkish BOJ and Fed narratives carried from Asia |
| 🇳🇰Ongoing (Rates Market) | BOJ September 18 Hike Odds Near 75% | Board member Hajime Takata has flagged scope for outsized or back-to-back hikes | 🔴 CRITICAL | Continues to support yen strength against the pound and other majors into the European afternoon |
| 🇺🇸Friday, 11 September | US August CPI | Core CPI seen around +0.2-0.3% month-on-month | 🔴 CRITICAL | The decisive input for the Fed’s September 16 decision and the week’s final major catalyst |
European Session Trade Ideas — EUR/USD, DAX, ETH/USD and More
Technical setups and fundamental context across the session’s nine key instruments
EUR/USD
Why This Setup
The pair is holding comfortably above 1.1600 even as Fed hike odds climb toward 58% for September 16, supported by a near-95% priced ECB hike to 2.50% on Thursday and eurozone inflation running back above 3%. The key risk is Lagarde’s guidance: a cautious tone framing Thursday as the final hike could quickly unwind the euro’s resilience, while weak German industrial data is an additional source of two-way risk if it starts to weigh more heavily on sentiment.

GBP/JPY
Why This Setup
BOJ hike odds near 75% for September 18 continue to underpin the yen against most majors carried into the European session, while the Middle East escalation adds a periodic safe-haven bid for the yen on risk-off headlines. The main threat to the bearish case is a sudden reversal in risk sentiment, such as a de-escalation in the US-Iran conflict, or unexpectedly strong UK data that lifts sterling independently of the yen story.

EUR/CHF
Why This Setup
The franc’s traditional safe-haven bid from the ongoing US-Iran conflict and the fresh German political uncertainty around the AfD’s election result are the main drivers behind a fade in EUR/CHF rallies, even as a near-certain ECB hike on Thursday offers the euro some near-term support. A hawkish Lagarde press conference or a sharp de-escalation in the Middle East are the main sources of two-way risk to this setup.

Silver
Why This Setup
Silver is giving back part of last week’s advance as stronger-than-expected US jobs data lifts Treasury yields and the Dollar, reducing the near-term appeal of non-yielding metals, but the broader uptrend remains intact with the metal still up roughly 60% year-on-year on persistent industrial demand and safe-haven flows tied to the Middle East conflict. Friday’s US CPI print is the key near-term catalyst for the next directional move.

Crude Oil (WTI)
Why This Setup
The US struck three Iranian oil tankers over the weekend and Iran has retaliated while threatening a restricted maritime zone beyond the Strait of Hormuz, keeping both benchmarks near their highest levels since July. The US Energy Secretary has confirmed the US will maintain its naval presence to help ensure safe passage through Hormuz, which is a source of two-way risk alongside any signs of de-escalation between Washington and Tehran.

DAX
Why This Setup
The AfD’s historic Saxony-Anhalt win, rising Bund yields and elevated oil prices are combining to weigh on German equity sentiment heading into Thursday’s ECB decision, with the index leading a modest Stoxx 600 decline despite a sharp rally in Nordex on a broker upgrade. A dovish ECB surprise or a de-escalation in the US-Iran conflict would be the main sources of two-way risk to the downside case.

EU 10Y (German Bund Yield)
Why This Setup
The 10-year Bund yield is being pulled higher by a combination of a modest political risk premium following the AfD’s Saxony-Anhalt win and a near-certain ECB hike to 2.50% on Thursday against a backdrop of eurozone inflation running above 3%. A dovish surprise in Lagarde’s forward guidance or a sharp risk-off move tied to the Middle East conflict, which would likely trigger safe-haven Bund buying, are the main sources of two-way risk to higher yields.

BNB
Why This Setup
BNB is consolidating after a strong weekly advance of close to 9%, supported by continued ecosystem development including new AI-agent tooling on the BNB Chain. A broader risk-off move tied to the US-Iran escalation or a firmer Dollar on elevated Fed hike odds are the main sources of two-way risk to this setup heading into the European afternoon.

ETH/USD
Why This Setup
ETH has reclaimed the $2,381 support level and is now consolidating between $2,381 and key resistance near $2,560, with the 20-day moving average trending upward and providing dynamic support. Institutional flows currently favour Bitcoin over Ethereum, and a broader risk-off move tied to the Middle East conflict is the main source of two-way risk to this setup.

European Session FAQ — 7 September 2026
Quick answers to the questions traders are asking right now
Why did the AfD’s election win only cause a modest reaction in German assets?
What does the ECB need to do on Thursday to move EUR/USD meaningfully?
Why is oil still rising even though the US-Iran conflict began over the weekend?
Why is GBP/JPY falling even though it’s the euro and German assets in the headlines today?
What is the single biggest risk to today’s European session trades?
European Session Summary — Monday, 7 September 2026 (Live Update)
Monday’s European session is being shaped by three forces pulling in different directions: a historic AfD regional election win in Germany that has put a modest political risk premium into German assets, a near-certain ECB rate hike on Thursday against a backdrop of eurozone inflation running above 3%, and an unresolved US-Iran conflict that continues to push oil prices toward their highest levels since July. The 10-year Bund yield is holding near 3.35%, its highest level in years, while the DAX leads a modest Stoxx 600 decline near 26,046. Brent crude has held near $97.40 a barrel and WTI near $92.30 after the US struck three Iranian oil tankers over the weekend and Tehran threatened a restricted maritime zone beyond the Strait of Hormuz.
EUR/USD is holding firmly above 1.1600 near 1.1620 even as Fed hike odds climb toward 58% for September 16, with traders’ attention fixed on Thursday’s ECB guidance rather than today’s weak German industrial production data. GBP/JPY continues to be pressured by hawkish Bank of Japan hike odds near 75% for September 18, while EUR/CHF is seeing the franc’s traditional safe-haven bid compete with ECB hike expectations. Silver has eased toward $66 an ounce on firmer yields but remains up roughly 60% year-on-year, and crypto majors BNB and ETH are both consolidating after strong weekly gains, with ETH testing key resistance near $2,560.
Highest-conviction session idea: stay long the Middle East risk premium via crude oil while it’s clear the US-Iran conflict has not de-escalated, fade DAX rallies into Thursday’s ECB decision given the combination of political risk and rising Bund yields, and treat EUR/USD’s resilience above 1.1600 as conditional on a hawkish Lagarde press conference rather than a settled trend.
For the individual instruments: EUR/USD buy dips toward 1.1580, stop 1.1520, target 1.1700 — a near-certain ECB hike is a genuine tailwind, though a cautious Lagarde tone is a real source of two-way risk. GBP/JPY sell rallies toward 212.50, stop 214.00, target 208.00 — hawkish BOJ odds are a genuine tailwind for the downside case, though a Middle East de-escalation is a real source of two-way risk. EUR/CHF sell rallies toward 0.9450, stop 0.9520, target 0.9300 — safe-haven franc demand is a genuine tailwind for the downside case, though a hawkish ECB is a real source of two-way risk. Silver buy dips toward $64.50, stop $62.00, target $70.00 — the broader uptrend is a genuine tailwind, though firmer yields are a real source of two-way risk. Crude oil buy dips toward $90.50, stop $87.00, target $96.00 — the unresolved Iran conflict is a genuine tailwind, though any de-escalation is a real source of two-way risk. DAX sell rallies toward 26,300, stop 26,600, target 25,600 — political risk and rising yields are a genuine tailwind for the downside case, though a dovish ECB surprise is a real source of two-way risk. EU 10Y buy yield dips toward 3.30%, stop 3.20%, target 3.55% — a near-certain ECB hike is a genuine tailwind, though safe-haven Bund buying on a risk-off shock is a real source of two-way risk. BNB buy dips toward $700, stop $660, target $820 — strong ecosystem momentum is a genuine tailwind, though crypto’s sensitivity to risk-off shocks is a real source of two-way risk. ETH/USD buy dips toward $2,420, stop $2,350, target $2,750 — a reclaimed support zone is a genuine tailwind, though resistance near $2,560 and softer institutional flows are a real source of two-way risk. The decisive variable for the rest of the week is Thursday’s ECB decision, and every position here should be sized with the knowledge that fast-moving Middle East headlines can exaggerate moves in either direction before then.
Ready to act on today’s setups? Open an Account with Capital Street FX and trade every instrument covered in this report on our Zero Account’s 0.0 Pips Spreads and 1:10000 Leverage, across 2000+ Instruments, with a welcome deposit bonus and 24/7 Live Support on hand for every session.
Not sure which account fits your style? Compare our Account Types side by side with our Account Comparison tool, browse current Promotions / Bonus offers, and trade from our Trading Platform suite. Funding is simple via our Deposit & Withdrawal options. For ongoing coverage, explore our Forex Analysis Pages, Commodity Analysis Pages and Crypto Analysis Pages, plus our Daily Market Analysis and Weekly Market Analysis reports and the full Economic Calendar. New to trading? Visit our Trading Education / Blog, or reach our Contact Us / Live Support team any time.
Access Live European Markets →