US 10-Year Yield Tops 4.80% and Brent Clears $92 as Wall Street Opens September in the Red | Technical Analysis – US Session | 1 September 2026
US 10-Year Yield Tops 4.80% and Brent Clears $92 as Wall Street Opens September in the Red
USD/CHF · USD/CAD · Gold · Brent Crude Oil · S&P 500 · US 10Y Yield · BTC/USD · XRP — live US market outlook today, updated through the trading session
US Market News — Live Now, 1 September 2026
Top-moving headlines shaping the US market outlook today, updated through the session
Global Bond Rout Sends the US 10-Year to 4.80%, Its Highest Since January 2025
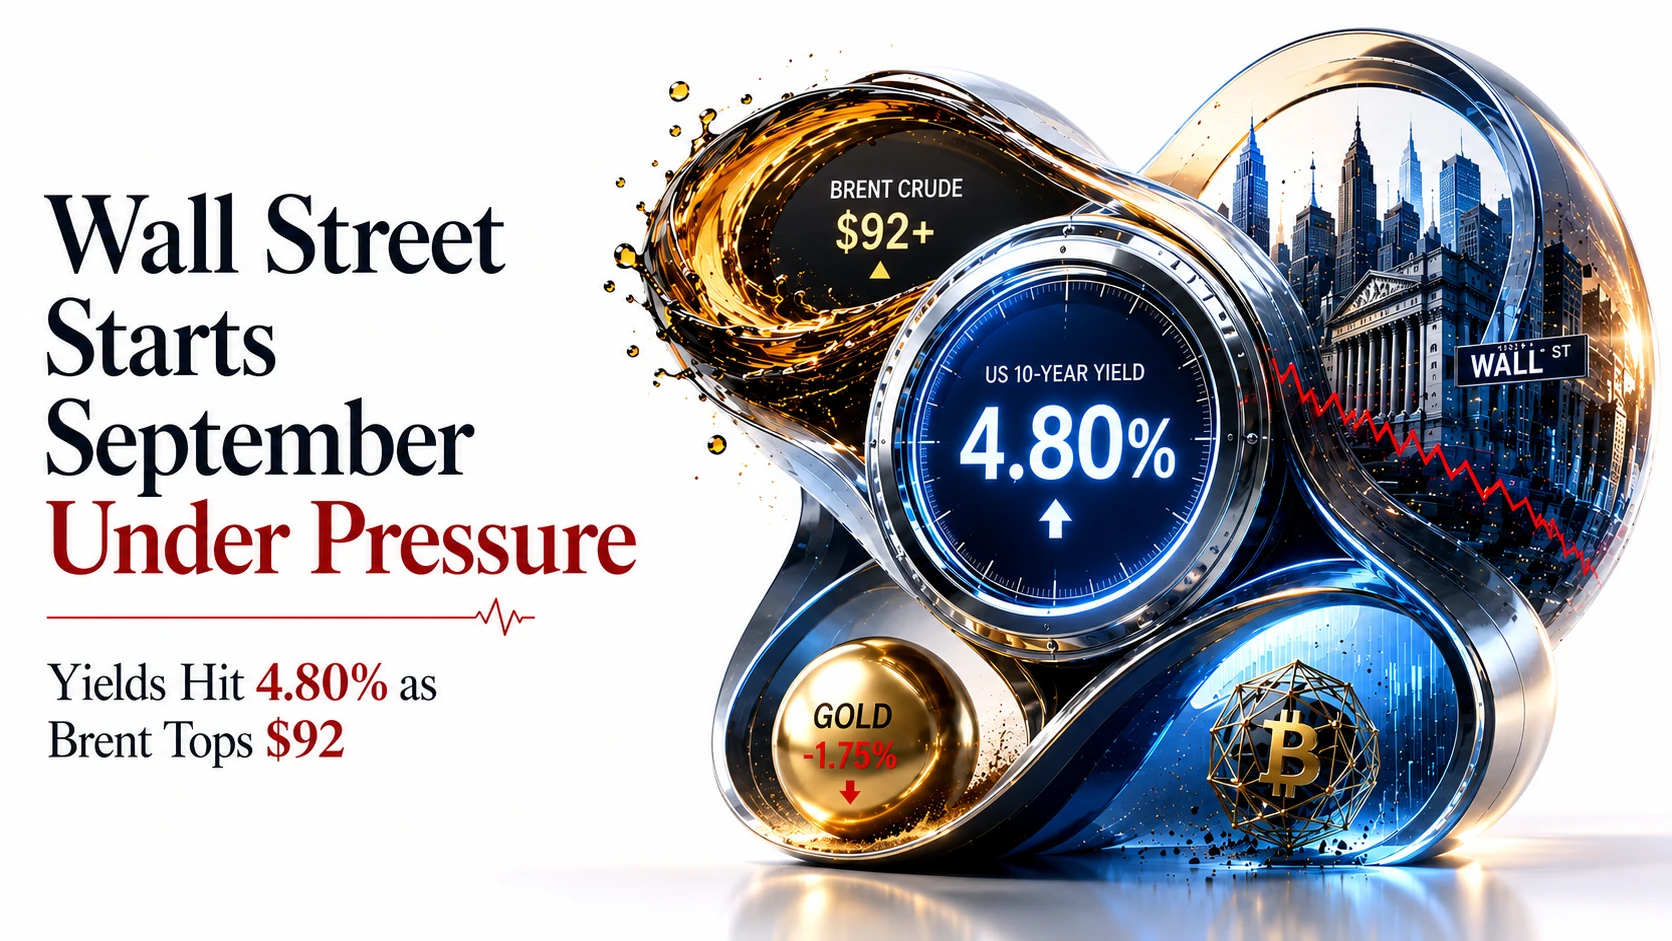
The yield on the US 10-year Treasury note rose for a fifth consecutive session to about 4.77% on Tuesday, touching 4.798% intraday, its highest level since January 2025, while the 30-year climbed to 5.28% and the two-year reached 4.35%. The selloff is global: Japan’s 10-year touched 3% for the first time in a generation, Germany’s hit 3.35% and France’s 4.21%, as energy-driven inflation, heavy corporate issuance and rate-hike repricing overwhelmed demand for duration.
RatesBrent Tops $92 After Two Saudi Supertankers Are Struck Exiting the Strait of Hormuz
Two supertankers loaded with Saudi crude were hit by unknown projectiles within minutes of each other while transiting outbound through the Strait of Hormuz late Monday, pushing Brent above $92 a barrel and WTI to $88.21, up 2.21%, after Monday’s $90.49 settlement. A separate vessel caught fire after striking naval mines in the southern strait, and President Trump vowed to hit Iran “hard” following Sunday’s US strike on Larak Island and Tehran’s retaliation against US bases in Jordan.
GeopoliticsFed Hike Odds Jump Toward Two-Thirds for the 15–16 September Meeting
The CME FedWatch Tool now shows roughly 65–68% odds of a 25-basis-point hike at the 15–16 September FOMC meeting, up from about 40% a week ago and around 36% before Chair Kevin Warsh’s Jackson Hole keynote, in which he said the Fed would have more work to do without clearer evidence that inflation is returning to the 2% target. The repricing is the single dominant driver across the Dollar, gold and the front end of the curve.
Monetary PolicyISM Manufacturing Slips to 54.6 and JOLTS Undershoots as Hiring Cools
The August ISM Manufacturing PMI fell to 54.6 from July’s near four-year high of 55.6, below the 55.2 consensus, with the employment index dropping to 51.2 and new orders sliding to 53.7 from 56.7, while prices paid held elevated at 71.1. July JOLTS job openings rose to 7.271 million from 7.182 million but missed the 7.3 million forecast, and hiring fell by 278,000 to take the hiring rate to 3.2%, its lowest since February. July construction spending fell 0.5% against expectations of no change.
Macro DataWall Street Opens the Weakest Month of the Year in the Red as Chips Lead Lower
The S&P 500 is down about 0.36% near 7,658, the Nasdaq Composite off roughly 0.87% near 26,140 and the Dow lower near 53,123, with the VIX up nearly 6% toward 15.8 and technology, especially semiconductors, taking the brunt of the selling. The pullback follows a solid August in which the S&P gained 2.62%, the Nasdaq 3.93% and the Dow 1.34%, and comes as the index heads into a month that has averaged a 0.8% decline over the past three decades.
EquitiesGold Sinks Below $4,350 and Crypto Softens as the Rate Channel Dominates
Gold has fallen 1.75% to about $4,344.26 an ounce, a fresh two-week low, dropping through its 200-day moving average to test the 100-day near $4,368 despite the Middle East escalation, because the market is currently trading bullion through the interest-rate channel rather than the inflation channel. Bitcoin is down near $78,007 after spot ETFs posted $201.9 million of outflows on 28 August, ending a nine-session, $3.04 billion inflow streak, while XRP holds near $1.3804 with total crypto market capitalisation down 2.95% at about $2.62 trillion.
Commodities & CryptoLive · Updated through the US morning session, Tuesday 1 September 2026
US Economic Calendar This Week — 1 September 2026
Key releases and events shaping price action through the rest of the week
| Time | Event | Forecast / Detail | Impact | Market Read |
|---|---|---|---|---|
| 🇺🇸Friday, 28 August (Recap) | Fed Chair Kevin Warsh’s Jackson Hole Keynote | Hawkish; September hike odds jumped from ~36% to ~65% | 🔴 CRITICAL | Still the dominant driver of Dollar strength, higher yields and weaker gold |
| 🇺🇸10:00 ET Today (Released) | ISM Manufacturing PMI (August) | 54.6 actual vs 55.2 expected, 55.6 prior; prices paid 71.1 | 🔴 CRITICAL | Softer headline but sticky prices paid keeps the hike case intact |
| 🇺🇸10:00 ET Today (Released) | JOLTS Job Openings (July) | 7.271M actual vs 7.300M expected, 7.182M prior; hiring rate 3.2% | 🔴 CRITICAL | Cooling hiring is the first real counterweight to September hike pricing |
| 🇺🇸10:00 ET Today (Released) | Construction Spending (July) | -0.5% m/m actual vs 0.0% expected | 🟢 MEDIUM | A soft print, but overshadowed by the rates and energy story |
| 🇮🇷Ongoing | Two Saudi Supertankers Struck Exiting the Strait of Hormuz | Brent above $92; strait closed since February; Trump vows a response | 🔴 CRITICAL | The dominant swing factor for oil, yields and risk sentiment into the close |
| 🇨🇦09:45 ET Wednesday, 2 September | Bank of Canada Rate Decision | All 35 economists in the Reuters poll expect a hold at 2.25% | 🔴 CRITICAL | The near-term catalyst for USD/CAD; Macklem’s tone matters more than the level |
| 🇺🇸Wednesday, 2 September | ADP Employment, Factory Orders and the Fed Beige Book | First read on private payrolls ahead of Friday’s official report | 🟢 MEDIUM | A hot ADP print would push September hike odds above 70% |
| 🇺🇸08:30 ET Friday, 4 September | August Non-Farm Payrolls | The decisive input for the 15–16 September FOMC decision | 🔴 CRITICAL | The week’s binary event for the Dollar, gold, equities and the curve |
US Session Trade Ideas — USD/CHF, USD/CAD, Gold and More
Technical setups and fundamental context across the session’s eight key instruments
USD/CHF
Why This Setup
The pair is holding above its 50-day SMA near 0.8091 with the 100-day at 0.7987 underpinning the structure, and the combination of a 10-year Treasury yield at 4.77% plus roughly 65% odds of a September Fed hike is a genuine tailwind against a Swiss National Bank that subdued domestic inflation leaves firmly on hold, though any sharp escalation in the Strait of Hormuz would revive the Franc’s safe-haven bid and is a real source of two-way risk.

USD/CAD
Why This Setup
Positioning ahead of Wednesday’s Bank of Canada decision is capping Canadian Dollar demand even with Brent above $92, and with all 35 economists in the latest Reuters poll expecting a hold at 2.25% against a Fed the market prices at roughly two-thirds odds of hiking this month, the rate gap is a genuine tailwind; a hawkish Macklem press conference or a further leg higher in crude are a real source of two-way risk, and a break below 1.3820 would hand momentum back to the Loonie.

Gold
Why This Setup
Bullion is being traded through the interest-rate channel rather than the inflation channel right now, and with the 10-year at its highest since January 2025 and the 30-year at 5.28%, the rising real-yield backdrop is a genuine headwind that has already dragged the metal below its 200-day SMA to test the 100-day near $4,365; the same Iran-driven energy shock lifting headline inflation, plus gold’s roughly 10% August gain, is a real source of two-way risk if Friday’s payrolls print undercuts the hike case.

Brent Crude Oil
Why This Setup
Two supertankers loaded with Saudi crude were hit by projectiles within minutes of each other as they exited the Strait of Hormuz, a separate vessel caught fire after striking naval mines, and Trump’s vow to hit Iran “hard” leaves the war-risk premium firmly embedded with the waterway shut since February, which is a genuine tailwind; the EIA still models Brent averaging about $87 across 2026 and any credible de-escalation or corridor headline out of Muscat or Tehran is a real source of two-way risk.

S&P 500
Why This Setup
September is historically the weakest month of the year for the index, averaging a 0.8% loss over three decades, and the combination of a 4.77% 10-year, $92 Brent and a softer-than-expected ISM print at 54.6 is a genuine headwind with the 7,780–7,800 resistance shelf unbroken; the support cluster at 7,550–7,620 where the 50-day moving average sits, plus an earnings backdrop still strong enough to keep hyperscaler capex intact, is a real source of two-way risk for anyone pressing shorts.

US 10Y Treasury Yield
Why This Setup
The move is now a global one, with Japan’s 10-year at 3% for the first time in a generation, Germany’s at 3.35% and France’s at 4.21%, and the mix of energy-driven inflation, a heavy corporate issuance calendar and rate-hike repricing toward roughly 65–68% for 15–16 September is a genuine tailwind for higher yields; Friday’s August payrolls report and any renewed Treasury buyback support out of the Bessent Treasury are a real source of two-way risk.

BTC/USD
Why This Setup
Spot Bitcoin ETFs posted $201.9 million of outflows on 28 August, snapping a nine-session, $3.04 billion inflow run on the very day Warsh’s Jackson Hole remarks landed, and with total crypto market capitalisation down 2.95% to about $2.62 trillion, the rate-driven risk-off tone is a genuine headwind into the $77,000 shelf; August’s net inflows still exceeded $3 billion and a reclaim of the $80,000–81,000 band would flip the structure, which is a real source of two-way risk.

XRP/USD
Why This Setup
XRP is still trading above its daily EMA20 at $1.31, EMA50 at $1.21 and EMA200 at $1.33 with RSI around 60.7, and spot XRP ETFs have just posted their strongest week of 2026 at $110.49 million of net inflows, taking cumulative inflows to roughly $1.66 billion, which is a genuine tailwind; today’s scheduled one-billion-token escrow release, rising Bitcoin dominance at 59.6% and a daily close below $1.33 that would break the structure are a real source of two-way risk.

US Session FAQ — 1 September 2026
Quick answers to the questions traders are asking this session
Why are US Treasury yields rising so sharply on 1 September 2026?
What did today’s ISM and JOLTS data actually show?
Why is gold falling when the Middle East conflict is escalating?
Why did Brent crude push above $92 a barrel today?
What is driving USD/CHF and USD/CAD in this session?
What is expected from the Bank of Canada on 2 September?
Why is the S&P 500 lower after such a strong August?
What should traders watch for the rest of the US session and week?
US Session Summary — Tuesday, 1 September 2026 (Live Update)
Tuesday’s US session is being defined by a single transmission chain: a fresh Strait of Hormuz escalation is lifting oil, oil is lifting the inflation outlook, the inflation outlook is lifting rate-hike expectations, and rate-hike expectations are lifting yields and pressuring everything with duration in it. The 10-year Treasury note yields about 4.77%, having touched 4.798% intraday, a fifth straight session higher and the highest since January 2025, with the 30-year at 5.28% and the two-year at 4.35%. The repricing is global, with Japan’s 10-year at 3% for the first time in a generation, Germany’s at 3.35% and France’s at 4.21%, and it follows Chair Kevin Warsh’s Jackson Hole warning that has driven September FOMC hike odds from roughly 36% to around 65–68%.
Brent is above $92 after two supertankers carrying Saudi crude were struck exiting the Strait of Hormuz late Monday and a third vessel caught fire on naval mines, with President Trump vowing a hard response following Sunday’s strike on Larak Island and Iran’s retaliation against US bases in Jordan. The morning’s data cut both ways: ISM Manufacturing slipped to 54.6 from 55.6 with employment at 51.2 and new orders at 53.7, but prices paid held at 71.1, while July JOLTS openings missed at 7.271 million and the hiring rate fell to 3.2%, its lowest since February. Construction spending declined 0.5%.
Equities are opening the year’s historically weakest month on the back foot, with the S&P 500 near 7,658, the Nasdaq near 26,140 and the Dow near 53,123 as semiconductors lead lower and the VIX pushes toward 15.8. Gold has slid 1.75% to about $4,344.26, below its 200-day moving average and testing the 100-day near $4,368, because bullion is being traded through the rate channel rather than the safe-haven channel. The Dollar is firm at 0.8116 against the Franc and 1.3899 against the Loonie into Wednesday’s Bank of Canada hold, while Bitcoin sits near $78,007 after ETF outflows snapped a nine-session streak, and XRP holds $1.3804 above its daily EMA cluster on record weekly ETF inflows.
Highest-conviction session idea: stay with the rates trade — long US 10Y yield and long Brent on dips, short gold and the S&P 500 into rallies — while treating Friday’s August payrolls report as the binary event that either confirms or unwinds the entire September-hike structure.
For the individual instruments: USD/CHF buy dips toward 0.8060, stop 0.7980, target 0.8250 — the widening Fed-SNB rate gap and the pair’s hold above the 50-day SMA are a genuine tailwind, though a sharp Hormuz escalation reviving the Franc’s safe-haven bid is a real source of two-way risk. USD/CAD buy dips toward 1.3820, stop 1.3755, target 1.3990 — hawkish Fed pricing into a Bank of Canada hold is a genuine tailwind, though $92 Brent and a hawkish Macklem press conference are a real source of two-way risk. Gold sell rallies toward $4,470, stop $4,560, target $4,180 — the surge in real yields is a genuine headwind, though the same energy-driven inflation shock and a soft payrolls print are a real source of two-way risk. Brent Crude buy dips toward $88.50, stop $85.50, target $99.00 — struck tankers and a closed strait are a genuine tailwind, though any credible corridor or de-escalation headline is a real source of two-way risk. S&P 500 sell rallies toward 7,760, stop 7,835, target 7,480 — a 4.77% 10-year and September seasonality are a genuine headwind, though the 7,550–7,620 support cluster and intact AI capex are a real source of two-way risk. US 10Y Yield buy dips toward 4.70%, stop 4.60%, target 5.00% — the global bond rout and hike repricing are a genuine tailwind, though Friday’s payrolls and Treasury buyback support are a real source of two-way risk. BTC/USD sell rallies toward $80,800, stop $82,200, target $72,500 — ETF outflows and the rate-driven risk-off tone are a genuine headwind, though August’s $3 billion-plus of net inflows and a reclaim of $80,000–81,000 are a real source of two-way risk. XRP/USD buy dips toward $1.3300, stop $1.2600, target $1.5200 — record weekly ETF inflows and price above the full daily EMA cluster are a genuine tailwind, though today’s billion-token escrow release and rising Bitcoin dominance are a real source of two-way risk. The decisive variable for the rest of the day is whether the 10-year holds above 4.75% into the close and whether the Hormuz headlines quieten or intensify. Size positions accordingly, and note that fast-moving Middle East headlines carry genuine event risk that could exaggerate moves in either direction.
Ready to act on today’s setups? Open an Account with Capital Street FX and trade every instrument covered in this report on our Zero Account‘s 0.0 Pips Spreads and 1:10000 Leverage, across 2000+ Instruments, with a welcome deposit bonus and 24/7 Live Support on hand for every session.
Not sure which account fits your style? Compare our Account Types side by side with our Account Comparison tool, browse current Promotions / Bonus offers, and trade from our Trading Platform suite. Funding is simple via our Deposit & Withdrawal options. For ongoing coverage, explore our Forex Analysis Pages, Commodity Analysis Pages and Crypto Analysis Pages, plus our Daily Market Analysis and Weekly Market Analysis reports and the full Economic Calendar. New to trading? Visit our Trading Education / Blog, or reach our Contact Us / Live Support team any time.
Access Live US Markets →