Market Outlook on US 10Y Today: Technical Summary, Fundamental News and a Trade Setup With Entry, Stop Loss and Take Profit | 21-09-2026
Market Outlook on US 10Y Today: Technical Summary, Fundamental News and a Trade Setup With Entry, Stop Loss and Take Profit
The US10Y yield trades at 4.963%, down modestly, cooling from a 19-year high after the Federal Reserve’s first rate hike since 2023 and hawkish inflation comments from Chair Kevin Warsh.
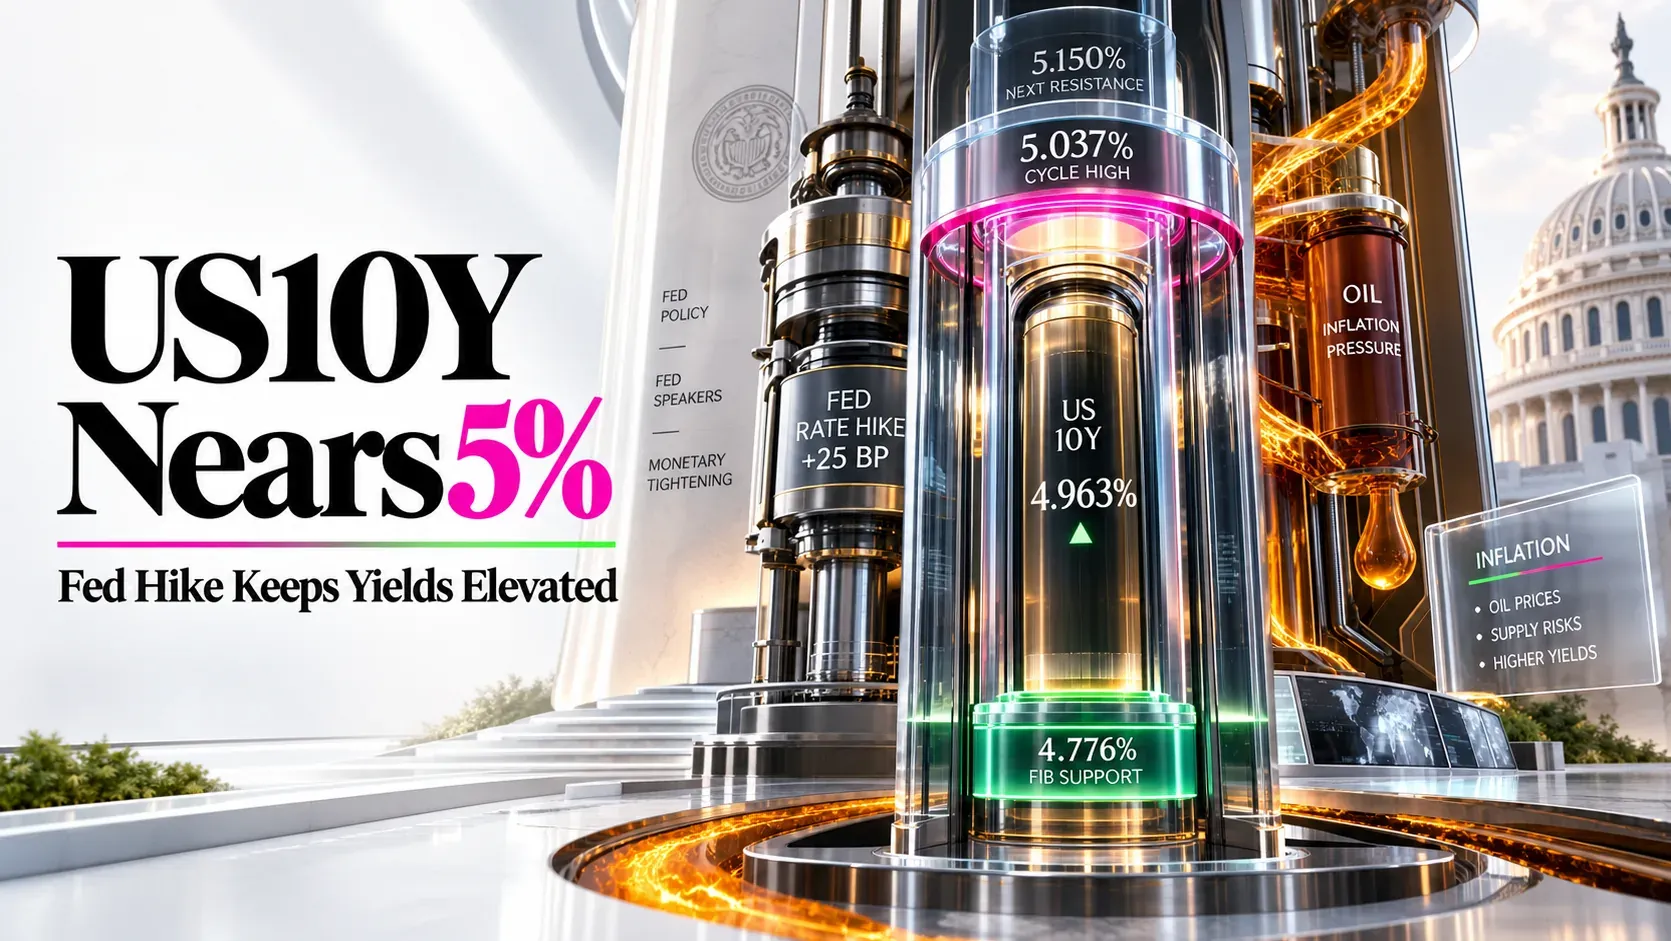
This US10Y market outlook starts from a benchmark yield that is pausing near a multi-decade high rather than reversing a trend. The 10-year yield is at 4.963% after a tight 4.963% to 4.976% session, and the RSI at 66.62 sits above its 63.11 signal line, still elevated and consistent with a market that remains firmly in an uptrend even as today’s candle prints a mild pullback. The Fibonacci grid measured from the 3.931% base up to the 5.037% recent swing high, this cycle’s peak and the highest level the 10-year yield has reached since 2007, puts the 23.6% retracement at 4.776%, a level the yield has held above through today’s session, with the 38.2% retracement at 4.614% and the 50% retracement at 4.484% the deeper support zones that would only come into play on a more meaningful reversal.
The catalyst behind the yield’s recent surge is unambiguous. The Federal Reserve raised its target range by 25 basis points to 3.75%-4.00% on 16 September, its first hike since 2023, and Chair Kevin Warsh told reporters that inflation is “too high and has been for too long,” a hawkish message that pushed the 10-year yield above the psychologically important 5% mark even as the hike itself had been fully priced in. Ahead of the decision the yield briefly topped 5.04%, its highest level since 2007, before easing modestly as oil prices softened and traders began digesting how many additional hikes the Fed is likely to deliver this year. The next 24 hours bring no scheduled repeat of the FOMC decision itself, but a dense slate of Fed speakers through Tuesday means the yield remains highly sensitive to any fresh commentary on the path of policy.
Fundamental News Set to Impact the US10Y Yield Next
The monetary policy, inflation and macro stories shaping the US10Y outlook for the next 24 hours
US10Y Technical Summary and Chart Analysis for Today
Daily structure, Fibonacci retracements and RSI as of 21 September 2026

US Government Bonds 10 YR Yield (TVC:US10Y) · Daily (1D) chart with Fibonacci retracement and RSI · Source: TradingView, CSFX Research
The technical summary for US10Y today shows a yield consolidating just beneath a cluster of cycle-high resistance after a sharp, Fed-driven advance. The 10-year yield is at 4.963% after opening at 4.972% and trading a narrow 4.963% to 4.976% range on the day. The Fibonacci structure is measured from the 3.931% base up to the 5.037% recent swing high, and the 23.6% retracement at 4.776% has held on every test since the rally began, with the 0% level at 5.037%, this cycle’s peak and the highest reading since 2007, the first meaningful hurdle on any continuation higher. The deeper retracements at 4.614% and 4.484% sit well below current levels, underlining how far the yield has already climbed from its earlier-year lows.
The broader structure still matters. The 10-year yield spiked from below 4% toward the 5% area through the summer before pausing on this week’s rate decision, a pattern of a fast advance followed by a shallow pullback that is typical of a market digesting a policy shock rather than reversing its trend. The current position, above the 23.6% retracement but below the cycle high, keeps the yield inside a consolidation range rather than confirming either a fresh leg higher or a completed top. The RSI at 66.62 against a 63.11 signal line remains elevated without yet reaching a classically overbought reading above 70, which is what a controlled pause looks like rather than an exhausted trend. Practically, this means US10Y is a level-based trade today rather than a directional bet: a confirmed daily close above 5.037% opens a run toward 5.15% and beyond, while a close below 4.750% would call the near-term strength into question and open the 38.2% retracement near 4.614%.
US10Y Technical Levels at a Glance · Next 24 Hours
- Resistance 1: 4.976% — today’s session high
- Resistance 2: 5.037% — the 0% Fibonacci level, this cycle’s peak and the highest yield since 2007, the key breakout level for sellers of Treasurys
- Resistance 3: 5.150% and 5.300% — extension zones if the cycle high is cleared with volume
- Support 1: 4.963% — today’s session low and close
- Support 2: 4.776% — the 23.6% retracement, held on every test since the rally began
- Support 3: 4.614% and 4.484% — the 38.2% and 50% retracements, the deeper zones that would open on a more meaningful reversal
- Pivot: 5.037% — the cycle high that decides whether this is a pause before further upside or the start of a deeper correction
- Momentum: RSI 66.62 versus signal 63.11 — elevated and consistent with an intact uptrend, short of a classically overbought reading above 70
Calendar — Events That Can Move the US 10-Year Yield in the Next 24 Hours
Key Federal Reserve, inflation and macro events shaping the US10Y outlook for the coming 24 hours
| Date / Time (ET) | Event | Detail | Impact |
|---|---|---|---|
| Monday 6:30 AM | Chicago Fed President Austan Goolsbee Speaks | The first of this week’s ten-plus Fed appearances. Any early signal on how policymakers are weighing today’s inflation data against growth concerns sets the tone for the rest of the week’s commentary. | MEDIUM |
| Monday Ongoing | Oil Price Volatility and Middle East Developments | Continued uncertainty around Saudi Arabian supply and elevated geopolitical tensions in the Middle East remain a live wildcard for energy prices, and by extension for near-term inflation expectations and the long end of the Treasury curve. | MEDIUM |
| Tuesday 10:05 AM | New York Fed President John Williams Speaks | Williams is a permanent voting member and among the most closely watched Fed voices on policy direction. Comments that reinforce or push back against the “at least one more hike” guidance from the September statement carry outsized weight for the yield. | HIGH |
| Tuesday 10:20 AM | Fed Vice Chair Philip Jefferson Speaks | As Vice Chair, Jefferson’s remarks are read as close to the Committee’s institutional view. Any specificity on the timing or size of the next hike is the single clearest catalyst on this week’s calendar. | HIGH |
| Tuesday 1:00 PM | Richmond Fed President Thomas Barkin Speaks | Barkin has historically focused on labour market and pricing-power dynamics. His comments round out a day of three separate Fed appearances that together carry more near-term influence on yields than any single scheduled data release this week. | MEDIUM |
| Tuesday Morning | Chicago Fed National Activity Index | A broad monthly gauge of national economic activity. A reading that surprises meaningfully in either direction can shift how traders weigh growth against inflation risk heading into the rest of the week. | LOW |
| Background Ongoing | Digestion of the 16 September FOMC Decision and Dot Plot | Markets are still fully pricing the implications of the Fed’s first hike since 2023 and its signal of at least one more increase this year. With no confirmed second rate decision inside the next 24 hours, speaker commentary rather than a single scheduled event is the more immediate catalyst to watch. | HIGH |
The shape of this calendar reflects a market digesting a hawkish rate decision through a dense run of Fed commentary rather than counting down to a single scheduled release. There is no confirmed FOMC decision inside the next 24 hours, which means the tone of Tuesday’s three Fed speakers, rather than a data print, is the near-term catalyst most likely to move the 10-year yield.
US10Y Trade Setup for the Next 24 Hours: Entry, Stop Loss and Take Profit
US10Y (TVC) · 4.963% • COOLING TODAY WITHIN AN INTACT UPTREND — Buy a Dip Into 4.900%–4.930% or a Confirmed Break of 5.037%, Target the 5.150% Zone
US10Y · US Government Bonds 10 YR Yield
Technical Summary (Next 24 Hours)
US10Y is at 4.963%, holding above the 23.6% Fibonacci retracement at 4.776%, which has not been broken since this cycle’s rally began. A confirmed daily close above 5.037%, this cycle’s peak and the highest reading since 2007, would open 5.150% and eventually the 5.300% area. A close below 4.750% would call the near-term strength into question and open the 38.2% retracement near 4.614%.
Fundamental Driver
The Federal Reserve’s first rate hike since 2023 and Chair Warsh’s hawkish inflation commentary are the dominant drivers, compounded by elevated oil prices and rising University of Michigan inflation expectations. Commentary from Goldman Sachs framing the Fed’s path as measured rather than aggressive is a modest offsetting factor, but no confirmed second rate decision sits inside the next 24 hours, only a dense slate of Fed speakers.
Risk Management
Risk on the dip entry near 4.900% to 4.930% is roughly 15 to 25 basis points against the 4.750% stop, for a comparable distance of reward to TP1 alone and considerably more to TP2 and TP3; the breakout entry at 5.037% carries a tighter distance to TP1 but only triggers once the yield has already proven it can clear this cycle’s high. The 10-year yield remains exposed to a heavy run of Fed commentary and volatile oil prices, so size for the possibility of a fast, headline-driven move in either direction, scale out rather than holding for TP3 outright, and treat the 4.750% stop as the level that separates a controlled pause from a deeper correction.
There are two clean ways to express this US10Y idea. The confirmation version waits for a daily close above 5.037%, this cycle’s peak and the highest level since 2007, which signals that buyers of yield have absorbed the initial reaction to the September hike, accepting a worse entry level in exchange for knowing the immediate resistance has been cleared before pressing toward 5.150%. The dip version waits for a rotation into 4.900% to 4.930%, right above the 23.6% retracement, which offers a tighter stop and a materially better risk-to-reward profile at the cost of possibly never being filled if the breakout comes first.
Small Details That Decide Whether the 10-Year Yield’s Pause Is Brief or Lasting
Context that matters for sizing a US10Y position today
The small things worth knowing before sizing a US10Y position today. First, 5.037% is not just a Fibonacci level, it is the highest reading the 10-year yield has posted since 2007, and a confirmed close above a level with that much psychological weight tends to attract genuine momentum buying in yield, which is precisely what makes a clean breakout worth trading and a brief wick above it worth treating cautiously rather than as automatic confirmation. Second, the Fed’s own dot plot points to two hikes total for the year with the October meeting likely skipped given its proximity to the midterm elections, according to Goldman Sachs, which means December is the next scheduled catalyst of real size, and today’s move is being driven by speaker commentary rather than a fresh policy decision. Third, University of Michigan inflation expectations jumping to 4.6%, the highest since June, is worth tracking closely, since a structural rise in expected inflation is one of the more reliable ways a term premium becomes embedded in long-dated yields rather than fading quickly. Fourth, oil price volatility tied to Saudi Arabian supply concerns and Middle East tensions is a genuine wildcard independent of the Fed’s calendar, and a sharp move in energy prices in either direction can reprice the long end of the curve within a single session. And finally, keep the broader curve in view: the spread between 30-year and 10-year yields has widened to its largest level since late 2021, a sign of active curve steepening that is worth weighing alongside the outright level of the 10-year yield when judging whether today’s move reflects Fed policy alone or a broader repricing of term premium across the curve.
FAQ: Today’s US 10-Year Yield, Technicals and Trade Setup
Common questions traders ask about US10Y on 21 September 2026
Conclusion: The 10-Year Yield Pauses Near a 2007 High While the Fed’s Message Stays Hawkish
The US10Y yield enters the next 24 hours at 4.963%, down a modest 0.74% on the day, holding just above the 23.6% Fibonacci retracement at 4.776% after a sharp advance last week toward 5.04%, its highest level since 2007. That pause looks like consolidation rather than reversal: the RSI at 66.62 remains elevated above its 63.11 signal line, even as the underlying cause of the advance, the Federal Reserve’s first rate hike since 2023 and Chair Warsh’s warning that inflation is too high, remains firmly in place. No confirmed second rate decision sits inside the next 24 hours, which means Tuesday’s run of Fed speakers, rather than a single scheduled event, is the more immediate catalyst to watch.
The trade setup is therefore built on levels, not conviction. A rotation into 4.900% to 4.930% is the better-priced entry against the 4.750% stop; a confirmed close above 5.037% opens 5.150% and eventually the 5.300% area, at the cost of a worse entry level; and a close below 4.750% removes the constructive case entirely and reopens the path toward 4.614%. Yields built around a fresh, hawkish policy shift can consolidate for days before their next real move, so the discipline that matters today is respecting the defined levels rather than assuming today’s modest pullback settles the question either way.
None of this is investment advice. The US10Y yield remains exposed to a heavy week of Federal Reserve commentary, volatile oil prices and shifting inflation expectations, and today’s levels can move on a single speaker’s remarks or a fresh energy headline. Always size positions to your own risk tolerance and confirm every level against a live feed before acting.