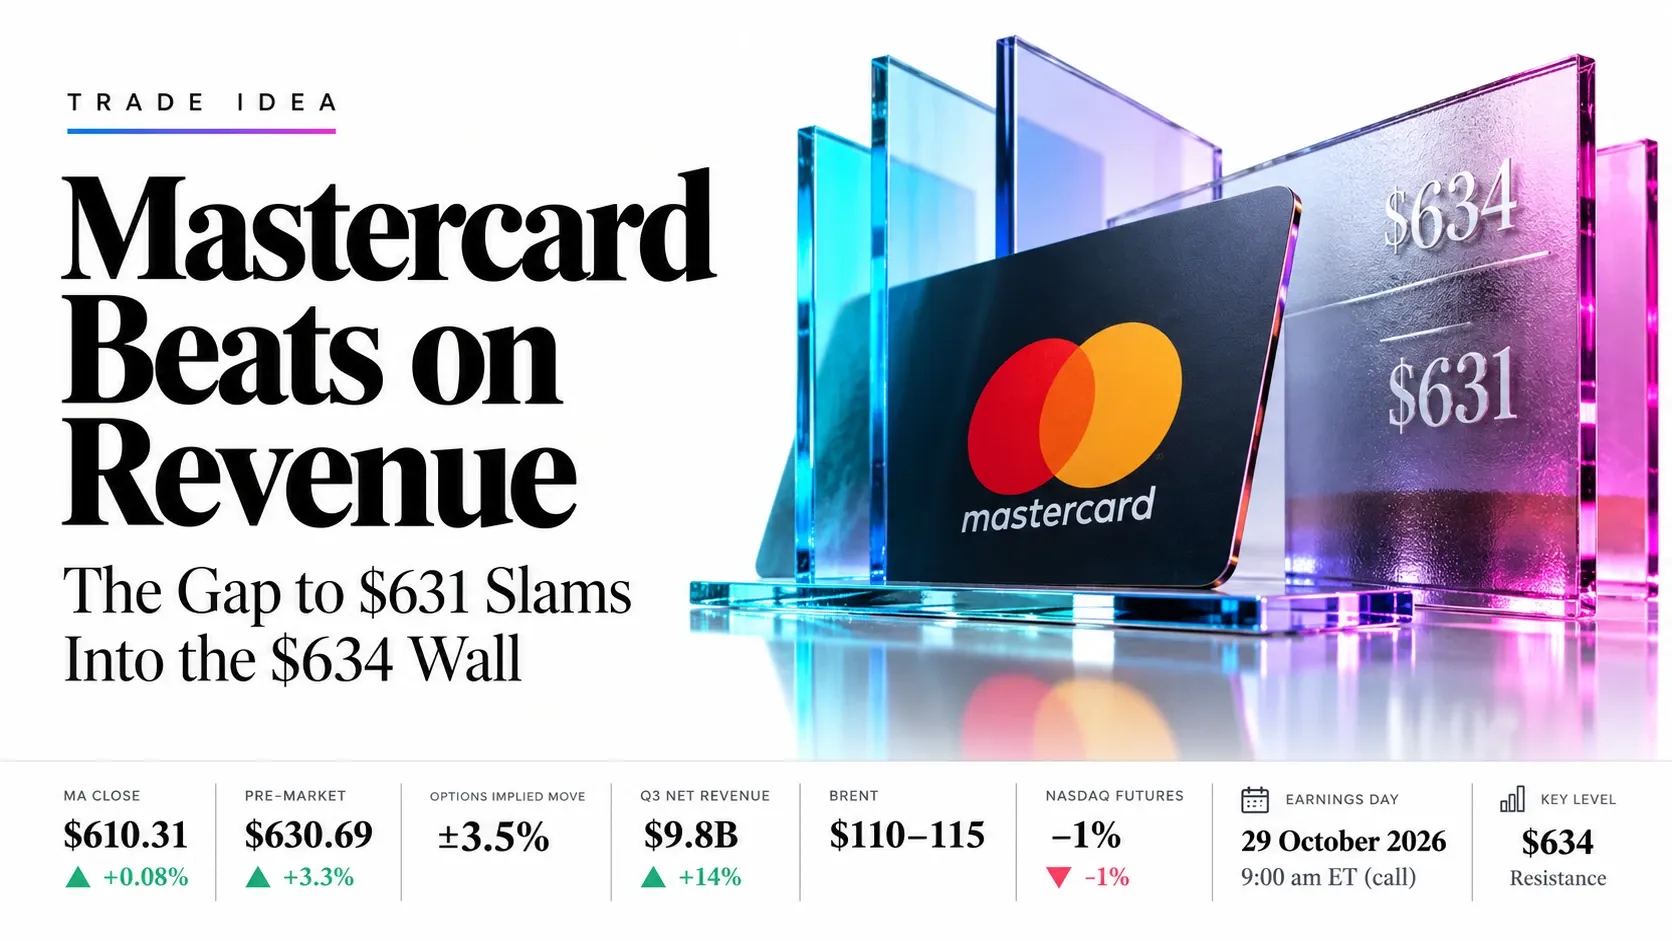
Mastercard Beats on Revenue: The Gap to $631 Slams Into the $634 Wall
Mastercard Beats on Revenue: The Gap to $631 Slams Into the $634 Wall
Live, 29 October: Mastercard has just reported Q3 net revenue of $9.8 billion, up 14% and ahead of the roughly $9.66 billion Wall Street expected, and the stock is indicated about 3.3% higher at $630.69 pre-market. That lifts it straight into the ceiling of its rising channel at $634–640, with the 9:00 am ET call still to come and a ±3.5% move priced in. The next hour decides whether $634 breaks or the gap fills. Here is the plan for both outcomes, with exact entries, stops and targets.
Market snapshot
Sources: BreakingTheNews/BizToc (revenue headline, 29 Oct), TipRanks, Alphastreet, Benzinga, Trefis, Yahoo Finance, Investing.com (27–29 Oct), CSFX chart. Only the revenue headline was confirmed when this was updated; reported EPS, services growth and guidance were not yet verified, and the call has not started.
The thesis in four lines
- The business keeps beating. Q2 net revenue rose 14% to $9.3B and adjusted EPS was $5.04 against $4.77 expected; value-added services grew 20%.
- The setup was friendly. Visa beat on Tuesday with cross-border volume up 14% (ex intra-Europe) yet slipped about 1.4% after hours; JPMorgan called Mastercard’s setup mildly favourable.
- The stock reacts hard to the call. Past earnings moves: +3.3% (Jan), −5.7% (Apr), +1.7% (Jul). The valuation is about 27x forward earnings, so guidance and incentive costs matter as much as the beat.
- The backdrop is shaky. The Fed held with two hawkish dissents, Nasdaq futures are down about 1% after Alphabet’s miss, and Brent near $110–115 on Iran risk keeps rate-hike talk alive.
Key levels
| Level | Role |
|---|---|
| ~$640 | Upper channel boundary at today’s date (approx. from chart) |
| ~$634 | Recent swing high (late October); breakout trigger |
| $630.69 | Pre-market quote on the chart |
| $610.31 | Wednesday close; a close back below it means the gap has failed |
| $597.71 | Short-term moving average, first support |
| $584.21 | Medium-term moving average |
| $558.36 | Long-term moving average, near the lower channel |
Daily chart: price is leaning on the channel ceiling

Price has climbed in a rising channel since the June low near $467 and tagged the top near $634 last week, then pulled back for three sessions. The RSI cooled from above 70 to 59, which is healthy rather than weak, and every moving average still slopes up. A pre-market gap of this size lands the stock back at the ceiling, where a clean break could extend the trend and a rejection would likely fill the gap. That is why both plans wait for the first hour to confirm.
The trade plan
With a ±$21 implied range and a gap already in the quote, chasing the open is the weakest option. Let the first hour pick the side.
- Trigger
- Trades above $634 and holds above it for the first hour
- Entry zone
- $635–638
- Stop
- $624
- Targets
- $652, then $665 (extension levels)
- Reward : risk
- About 1.2R to T1, 2.3R to T2 (from $636.50)
Bullish inputs: revenue and EPS above consensus, services growth near 20%, guidance held at the high end of low double digits, and no jump in rebates and incentives.
- Trigger
- Gap fades and price closes below $610.31
- Entry zone
- $606–610 on a failed bounce
- Stop
- $618
- Targets
- $597.71, then $584.21
- Reward : risk
- About 1.0R to T1, 2.4R to T2 (from $608)
Bearish inputs: soft cross-border or volume growth, higher incentives squeezing network revenue, cautious Q4 tone, or a risk-off tape after the Alphabet miss.
No-trade zone: a choppy session between $611 and $633 tells you little. Skip it and wait for a close beyond either side.
What to watch today
| Item | Street expects | Why it matters |
|---|---|---|
| Net revenue | ~$9.66B (+12%); reported $9.8B (+14%) | A beat that matches Q2’s 14% pace |
| Adjusted EPS | ~$5.17 (vs $4.38) | Four straight beats set a high bar |
| Value-added services | Q2: +20% (+18% currency-neutral) | The growth engine and the margin story |
| Rebates and incentives | Rising share of network fees | The main bear point on revenue quality |
| Guidance | High end of low double digits (currency-neutral) | First report with new CFO Ling Hai |
| Call timing | 9:00 am ET | Tone on Q4 and 2027 often moves the stock more than the numbers |
Risk management
- Size so a stop-out costs no more than 0.5–1% of the account; opening gaps can skip stops.
- The pre-market price can move sharply once the call starts at 9:00 am ET, so re-check levels against your own platform.
- Brent near $110–115 and a Fed split on rates can overwhelm a good print for a richly valued stock.
- Regulatory scrutiny and rival payment networks remain slow-burn risks to the multiple.