Week Ahead – US, 31 August – 4 September: August Payrolls Is the Last Word Before the Fed’s 16 September Decision
Week Ahead, 31 August–4 September: August Payrolls Is the Last Word Before the Fed’s 16 September Decision
ISM Manufacturing Tue 1 Sep · ADP & Fed Beige Book Wed 2 Sep · ISM Services Thu 3 Sep · August Nonfarm Payrolls Fri 4 Sep · FOMC communications blackout begins Sat 5 Sep
1. USD/CAD and USD/CHF — a hawkish Fed chair meets two very different central banks. USD/CAD closed Friday at 1.3904, up 0.35% on the day and roughly 1% on the week, as the loonie stayed pinned by the breakdown in Canada–U.S. trade talks and by President Trump’s threat to raise tariffs on Canadian cars, trucks and parts to 50% from 1 January 2027. The Bank of Canada announces on Wednesday and is widely expected to hold at 2.25% for a seventh consecutive decision, which leaves the pair trading almost entirely off the U.S. side of the equation. USD/CHF at 0.8093 rose 0.63% on Friday as the dollar index added 0.55% to 99.64; with the SNB policy rate at 0% and no meeting until later in September, this is the cleanest expression in G10 of the dollar’s rate story. CSFX sees both pairs as dollar trades this week rather than local ones.
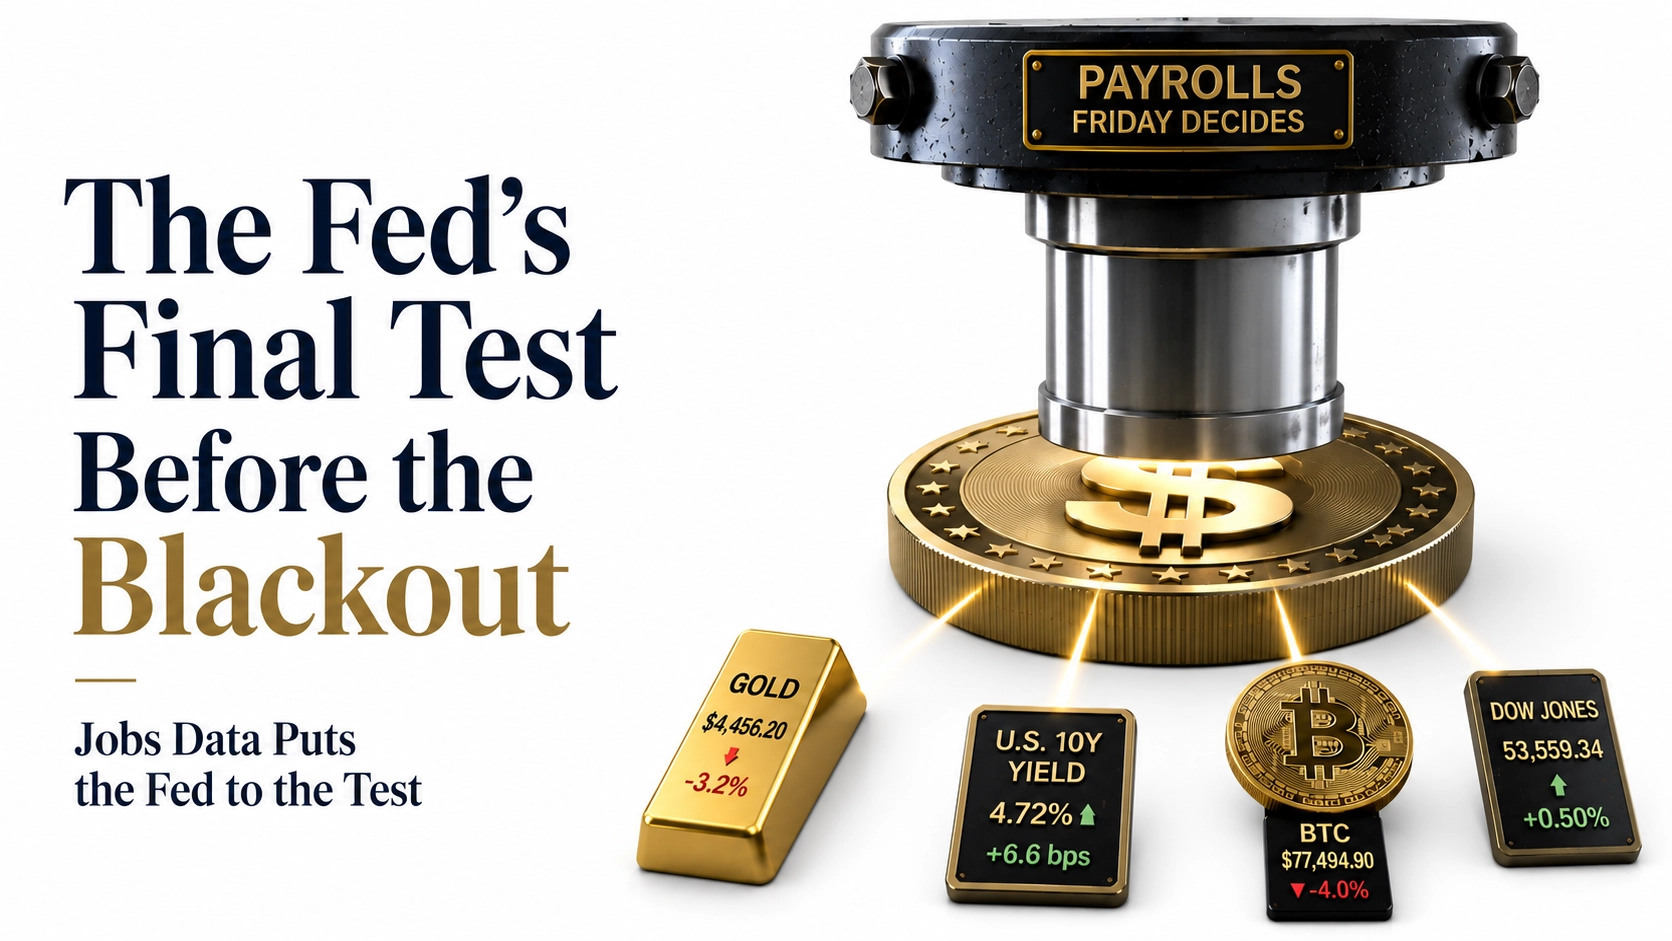
2. Gold and Crude Oil — one is repricing the Fed, the other the Strait of Hormuz. Gold fell 3.2% on Friday to $4,456.20 spot, with December futures down 3.4% to $4,506.66, a swing of roughly $173 from the overnight high near $4,688 and a 3.2% loss on the week after the previous week’s debasement-trade surge. WTI Crude Oil at $83.44 was essentially flat on Friday but down about 4.3% on the week, with Brent at $88.28, as Gulf export flows recovered and Iran and Oman agreed a revenue-sharing framework for the strait — even as Washington signalled it will not revive the collapsed June memorandum and the Treasury announced fresh sanctions. CSFX sees Wednesday’s EIA inventory report and the two ISM prices-paid readings as the week’s cross-check on both.
3. Dow Jones and the US 10Y — a record within reach and a yield curve that keeps flattening from the front. Dow Jones Industrial Average closed Friday at 53,559.34, down just 9.45 points on the day but up 0.53% on the week and roughly 480 points below its early-August peak near 54,037, with the index carried by Nvidia’s blowout guidance on Thursday before Friday’s rate-hike repricing capped it. The US 10-year Treasury yield ended at about 4.72%, up around four basis points, while the two-year jumped 6.6 basis points to 4.29% and the 30-year eased toward 5.16% — a classic bear-flattening reaction to a hawkish chair. CSFX sees Friday’s payrolls as the single largest risk to both.
4. BTC/USD and Dogecoin — the debasement trade takes a breather. BTC/USD fell 3.4% on Friday to $77,494.90, retreating from a session high of $81,330 and holding only a slight gain on a week that followed a 22% surge, with U.S. spot ETFs having absorbed roughly $2.8 billion across eight consecutive sessions to make August the strongest inflow month of 2026. Dogecoin at about $0.0851 is down roughly 4.5% over 24 hours and about 8% on the week, some 15% below August’s peak near $0.100. CSFX sees crypto as the highest-beta expression of the same September rate question that drives every other instrument on this list.
Three Forces That Will Drive the U.S. Session — 31 August to 4 September 2026
The scheduled U.S. catalysts that will set direction across FX, commodities, equities, rates and crypto for the week of 31 August – 4 September 2026
U.S. Session Weekly Levels & Bias
Eight instrument-specific reference levels for the week of 31 August – 4 September 2026. All levels for reference and informational purposes only; not financial advice. Visit capitalstreetfx.com for live signals and other markets.
What to Watch — A Fed-Driven Dollar Against a Bank of Canada on Hold
USD/CAD closed Friday at 1.3904 after the loonie failed to hold the 1.3764 level it reached on 21 August, its best against the dollar in three months. Two domestic forces are pulling in opposite directions: Canada’s economy grew at its fastest pace in nearly two years on an auto-production rebound, but Canada imposed retaliatory tariffs of 15% to 50% on about $20 billion of annual U.S. imports and Washington has threatened 50% duties on Canadian vehicles from January 2027.
The Bank of Canada announces at 09:45 ET Wednesday and bond markets price a high probability of no change from 2.25%, with only about a 6% chance of a hike. CSFX therefore treats this as a dollar pair rather than a loonie pair: a firm ISM on Tuesday and a payrolls beat on Friday open 1.4000, while a soft jobs print that unwinds September hike pricing brings 1.3760 back into play. Canada’s own August employment report lands the same morning, which makes Friday the only genuinely two-sided session of the week.

What to Watch — The Purest Dollar-Rate Expression in G10
USD/CHF rose 0.63% on Friday to 0.8093 as the dollar index added 0.55% to 99.64, reversing a franc that had reached its strongest level in two months earlier in the week. The Swiss side of this pair is close to inert: the SNB policy rate is 0%, the bank has reiterated its preference for FX intervention over rate moves to limit franc strength, and most economists do not expect a first hike before early 2028, though markets price the possibility as early as March 2027.
That leaves the pair trading almost purely on U.S. rate expectations, which is why it is a cleaner read on the payrolls reaction than the crosses that carry their own domestic news. CSFX sees 0.8195, the high from 28 July and the strongest dollar level in twelve months, as the target if Friday’s report keeps a September hike live; a downside payrolls surprise puts 0.8014 back on the table, with the franc’s safe-haven bid amplifying any risk-off follow-through.

What to Watch — Whether the Debasement Trade Survives a Hawkish Chair
Spot gold fell 3.2% on Friday to $4,456.20 and December futures dropped 3.4% to $4,506.66, a $173 reversal from the overnight high near $4,688 and one of the sharpest single sessions of the year. The trigger was mechanical: a hawkish chair lifted the dollar nearly 1% on the week and pushed short-end yields to a one-month high, and gold pays no coupon. The metal still enters September up roughly 4% on the year after its strongest month since January, driven by the debasement trade that followed the Treasury sell-off.
CSFX sees the $4,400 shelf as the first real test and $4,530, Friday’s intraday low, as the line that decides whether this is a correction or a trend change. A soft payrolls print on Friday that removes the September hike would put $4,700 back within a session’s reach; a strong one risks a second leg lower. The two ISM prices-paid readings on Tuesday and Thursday matter here too, because they speak directly to the inflation case that underpins the whole position.

What to Watch — A Draining Risk Premium Against Stalled Diplomacy
WTI ended Friday at $83.44, effectively unchanged on the day but down roughly 4.3% on the week, snapping a two-week winning streak, while Brent settled around $88.28 for a 5.3% weekly loss. The move came despite the U.S. Treasury announcing what it called its toughest sanctions yet to force Iran to reopen the Strait of Hormuz, and despite a Wall Street Journal report that the administration has told mediators it has no interest in reviving the June memorandum. Traders were more impressed by the flows: analysts point to an Iran–Oman shipping corridor, U.S. mine-clearance claims and Gulf exports recovering to roughly two-thirds of pre-conflict volumes.
Washington is also close to a long-term arrangement for access to Venezuelan oil fields, with reports that Caracas may leave OPEC. CSFX sees $80.00 as the level that would confirm the risk premium has genuinely deflated, and $88.00 as the ceiling unless a Hormuz headline reverses the flow story. Wednesday’s EIA inventory report at 10:30 ET is the week’s only scheduled U.S. supply catalyst.

What to Watch — A Fourth Weekly Gain in Five Into a Coin-Flip Meeting
The Dow closed Friday at 53,559.34, down 9.45 points, while the S&P 500 lost 0.25% to 7,711.76 and the Nasdaq Composite fell 0.52% to 26,402.42. All three still posted weekly gains — the Dow 0.53%, the S&P 0.49%, the Nasdaq 0.85% — in what was Wall Street’s fourth advance in five weeks, driven almost entirely by Nvidia’s near-9% Thursday surge after it reported quarterly revenue of $92.22 billion, up 106% year-on-year, and guided to about $108 billion for the current quarter. Nvidia gave back 4.6% on Friday and Marvell fell 10.3%.
The Dow’s defensive tilt has been an advantage in this repricing: it is the least rate-sensitive of the three indexes and sits about 480 points below its early-August peak near 54,037. CSFX sees that peak as the level to beat if Friday’s payrolls come in soft enough to take a September hike off the table, and 53,000 as the first support if the labour data is strong and the long end backs up with it.

What to Watch — A Bear-Flattener That Payrolls Can Reverse in a Minute
The 10-year yield finished Friday around 4.72%, roughly four basis points higher, after trading near 4.67% into Warsh’s speech. The shape of the move mattered more than the level: the two-year jumped 6.6 basis points to 4.29%, its highest in a month and the largest short-end move in more than two months, while the 30-year drifted toward 5.16% — the market pricing tighter policy now and, implicitly, less inflation later. Support for yields also came from a hotter-than-expected inflation reading earlier in the week, with July headline PCE at 3.7% year-on-year and CPI at 3.4%.
The probability of a hike by December remains above 70% even as September stays a coin flip. CSFX sees 4.80% as the level that would signal the market has moved to fully pricing September, and 4.60% as the floor a weak payrolls print would test. Friday’s 08:30 ET release is the only event this week capable of driving a double-digit basis point move in a single session.

What to Watch — ETF Demand Against a Rate Path That Turned Hawkish
Bitcoin fell 3.4% on Friday to $77,494.90, reversing from a session high of $81,330 and finishing the week with only a slight gain after the previous week’s 22% surge. The rally that got it there was structural rather than speculative: U.S. spot ETFs absorbed about $2.8 billion across eight consecutive sessions, the longest inflow streak since April, making August the strongest inflow month of 2026, while open interest stayed stable near $56.5 billion and short liquidations outpaced longs. Bitcoin also posted its strongest August in nearly a decade, with its correlation to gold back above 50%.
That correlation is the risk. Friday showed bitcoin trading as a debasement asset, selling off alongside gold and silver on a hawkish chair rather than rallying on risk appetite. CSFX sees $81,330 as the level to reclaim and the $74,000 area as the first meaningful support if Friday’s payrolls confirm a September hike. The $80,000 line, and the 50-week average near $81,081, are the technical markers traders are watching most closely.

What to Watch — The Highest-Beta Read on the Same September Question
Dogecoin trades near $0.0851 into the weekend, down roughly 4.5% over 24 hours and about 8% on the week, having fallen some 15% from August’s peak near $0.100. It is still up more than 20% over the past month, which is the pattern to keep in mind: DOGE amplifies whatever bitcoin does, in both directions, and it has no independent catalyst on this week’s calendar. A March 2026 joint SEC and CFTC framework classified it as a digital commodity, which removed a long-standing regulatory overhang without adding a demand source.
CSFX sees $0.0900 as the level that would confirm a recovery attempt — analysts flag an hourly close above it as the trigger for a move toward $0.115 — and $0.0810 as the support that has to hold if Friday’s payrolls push the dollar higher again. Position sizing matters more than direction here: DOGE’s weekly range is routinely double bitcoin’s.

What Could Move U.S. Markets Sharply This Week
The scheduled and unscheduled events that CSFX is watching most closely for the U.S. session, 31 August – 4 September 2026
U.S. Session — Economic Calendar, 31 August – 4 September 2026
All times Eastern Time (ET) and approximate. Key releases for USD/CAD, USD/CHF, Gold, Crude Oil WTI, the Dow Jones, the US 10-year yield, BTC/USD and Dogecoin.
| Day | Time (ET) | Release | Impact | Forecast | CSFX View |
|---|---|---|---|---|---|
| Monday, 31 August | |||||
| Mon | All Day | Month-end rebalancing flows; U.S. markets open normally | LOW | N/A | The last session before the September data run, and the final month-end fix before the Fed’s blackout begins. Thin conviction rather than thin liquidity. |
| Mon | 10:30 ET | Dallas Fed Manufacturing Index (August) | MED | N/A | The first regional read on August factory activity after the national ISM hit a four-year high of 55.6 in July. A useful early cross-check ahead of Tuesday. |
| Mon | Throughout | Fed speakers — final week before the 5 September blackout | MED | N/A | Any pushback on the roughly 57% odds of a September hike has to come this week. CSFX treats unscheduled Fed commentary as a live risk for USD/CHF and the front end. |
| Tuesday, 1 September | |||||
| Tue | 09:45 ET | S&P Global US Manufacturing PMI (final, August) | LOW | N/A | A final revision that rarely moves markets on its own, but sets the tone fifteen minutes before ISM. |
| Tue | 10:00 ET | ISM Manufacturing PMI (August) | HIGH | Prior 55.6 | The headline is expected to cool from July’s four-year high, but the prices-paid and employment sub-indices carry the signal. A hot prices print supports the hawkish case and pressures Gold. |
| Tue | 10:00 ET | JOLTS Job Openings (July) | HIGH | Prior 7.359M | The first of the week’s three labour readings. Openings have been grinding lower; a sharp drop would start unwinding hike pricing two days before ADP. |
| Tue | 10:00 ET | Construction Spending (July) | LOW | N/A | Second-tier, but relevant to the residential picture at a time when mortgage rates are tracking a 10-year yield near 4.72%. |
| Tue | 16:30 ET | API Weekly Crude Oil Stocks | MED | N/A | The first inventory signal of the week for WTI, a day before the official EIA figures. |
| Wednesday, 2 September | |||||
| Wed | 07:00 ET | MBA Mortgage Applications | LOW | N/A | A weekly read on rate sensitivity in housing; more useful as context for the long end than as a market mover. |
| Wed | 08:15 ET | ADP Employment Change (August) | HIGH | N/A | The private-payrolls preview. ADP has been a poor predictor of the BLS number this year, but a large miss in either direction reprices Friday’s expectations immediately. |
| Wed | 09:45 ET | Bank of Canada Interest Rate Decision | HIGH | Hold at 2.25% expected | A seventh consecutive hold is priced with roughly a 6% chance of a hike. The statement’s treatment of U.S. tariff threats is the USD/CAD risk, not the rate itself. |
| Wed | 10:00 ET | Factory Orders (July) | LOW | N/A | A backward-looking confirmation of the durable-goods picture; low market impact in a payrolls week. |
| Wed | 10:30 ET | EIA Weekly Crude Oil Inventories | MED | N/A | The week’s only scheduled U.S. supply catalyst for WTI, with the market already focused on recovering Gulf export flows. |
| Wed | 14:00 ET | Fed Beige Book | HIGH | N/A | The last district-level survey before the 15–16 September FOMC. CSFX is watching the hiring and pricing anecdotes, which have historically led the ISM employment sub-indices. |
| Thursday, 3 September | |||||
| Thu | 07:30 ET | Challenger Job Cuts (August) | MED | N/A | A layoffs read that matters more than usual given July’s payroll decline was concentrated in government and retail. |
| Thu | 08:30 ET | Initial & Continuing Jobless Claims | MED | N/A | Claims have stayed low even as hiring stalled — the no-hire, no-fire pattern. A break higher would be the clearest single sign that the labour market is cracking. |
| Thu | 08:30 ET | Nonfarm Productivity & Unit Labor Costs (Q2, revised) | MED | N/A | Unit labor costs feed directly into the inflation debate. A hot revision strengthens the case the hawks are making this week. |
| Thu | 09:45 ET | S&P Global US Services PMI (final, August) | LOW | N/A | A final revision ahead of ISM Services, useful mainly for confirming the direction of the services cooldown. |
| Thu | 10:00 ET | ISM Services PMI (August) | HIGH | Prior 54.1 | Services are roughly 70% of the economy. July showed prices paid at 70.3 against employment at 47.4; another combination like that makes September genuinely difficult for the Fed. |
| Friday, 4 September | |||||
| Fri | 08:30 ET | US Nonfarm Payrolls, Unemployment Rate & Average Hourly Earnings (August) | HIGH | N/A | The week’s decisive release. July fell 23,000 with 103,000 of downward revisions and participation at 61.4%. CSFX expects the largest dollar, gold, rates and crypto moves of the week in the first fifteen minutes. |
| Fri | 08:30 ET | Canada Labour Force Survey (August) | HIGH | N/A | Released simultaneously with the U.S. report, which makes USD/CAD the most volatile of the week’s FX pairs at the open of that session. |
| Fri | 13:00 ET | Baker Hughes US Rig Count | LOW | N/A | A weekly gauge of the U.S. supply response to prices that have fallen roughly 4% on the week. |
| Fri | After close | FOMC communications blackout begins Saturday 5 September | MED | N/A | No further Fed commentary until the 16 September decision, so Friday’s price action has to carry the market through a data-free week and the Labor Day holiday on Monday 7 September. |
U.S. Session — Trader Questions Answered
Key questions from CSFX clients ahead of the last U.S. data week before the Fed’s 16 September decision
CSFX View: Three Labour Prints, a Closing Policy Window, and a Coin-Flip September Set the Tone for the Week Ahead
The week of 31 August – 4 September 2026 opens the U.S. session with USD/CAD at 1.3904 and USD/CHF at 0.8093, both higher after Fed Chair Kevin Warsh’s hawkish Jackson Hole keynote lifted the dollar index 0.55% to 99.64 on Friday. Gold fell 3.2% to $4,456.20 spot and WTI Crude ended at $83.44, down roughly 4.3% on the week as Gulf export flows recovered through the Strait of Hormuz. The Dow closed at 53,559.34, effectively flat on the day but 0.53% higher on the week and about 480 points below its early-August peak, while the 10-year Treasury yield rose to around 4.72% and the two-year jumped to a one-month high of 4.29%. In crypto, BTC/USD fell 3.4% to $77,494.90 after a session high of $81,330, and Dogecoin slipped to about $0.0851.
Tuesday, Wednesday and Friday carry the week: JOLTS and ISM Manufacturing on Tuesday, ADP and the Fed’s Beige Book on Wednesday, ISM Services on Thursday, and the August employment report on Friday — the last major labour reading before the FOMC’s communications blackout begins on Saturday 5 September. Traders currently put the odds of a 25 basis point hike on 16 September at roughly 57%, up from about 35% before Warsh spoke, which makes this a genuinely two-sided week rather than a directional one. July’s report showed payrolls falling 23,000 with 103,000 of downward revisions and participation at a five-year low of 61.4%, so a second weak print would unwind hawkish pricing quickly. For commodities, the ISM prices-paid components are the cleanest read on whether the energy shock is still passing through as crude falls back.
CSFX’s key levels for the week: watch 1.3760 support and 1.4000 resistance on USD/CAD around Wednesday’s Bank of Canada decision, and 0.8014 support with 0.8195 resistance on USD/CHF into Friday’s payrolls. Gold is vulnerable between $4,400 support and $4,700 resistance while WTI trades between $80.00 and $88.00 as the Hormuz risk premium unwinds. The Dow is constructive between 53,000 support and 54,037 resistance, with the 10-year yield working between a 4.60% floor and a 4.80% ceiling, and BTC/USD tracking $74,000 to $81,330 with Dogecoin between $0.0810 and $0.0900 on the same rate question. CSFX will issue intra-week alerts if Tuesday’s ISM prices-paid reading runs materially hotter than July’s, if ADP diverges sharply from payrolls expectations, if the Beige Book shifts the September debate, if the Bank of Canada surprises on tariff language, or if the Iran–Oman framework around the Strait of Hormuz breaks down. Follow all updates at capitalstreetfx.com.
New clients can also take advantage of a limited-time deposit bonus when they open an account this week, on top of the usual account benefits — tight spreads, high leverage, and access to 2000+ instruments across FX, commodities, indices, and crypto. Full terms and other promotions are available on the CSFX website.
Trade U.S. Markets at CSFX →