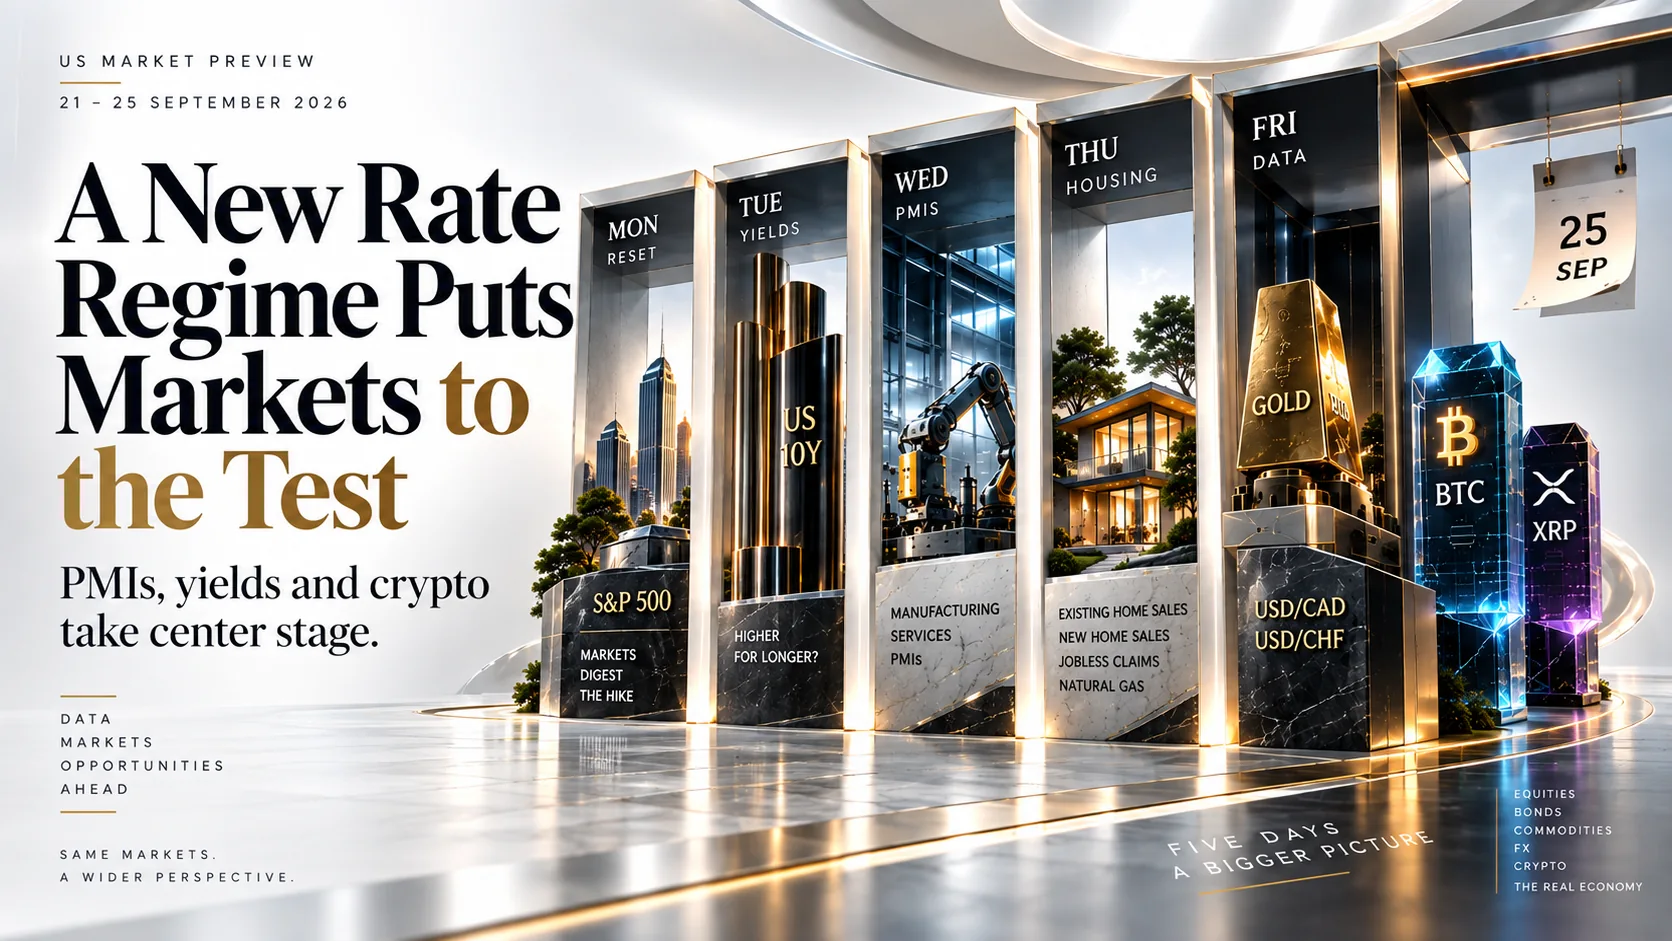
Week Ahead US, 21–25 September: Markets Digest the Fed’s First Hike in Years as Flash PMIs and a Post-CLARITY Act Crypto Reset Take Center Stage | 19 September 2026
Week Ahead, 21–25 September: Markets Digest the Fed’s First Hike in Years as Flash PMIs and a Post-CLARITY Act Crypto Reset Take Center Stage
Entering the week: S&P 500 7,650.50 · US 10Y Yield 4.96% · Gold $4,368.60 · USD/CAD 1.3790 · USD/CHF 0.8090 · Natural Gas $2.91 · BTC/USD $80,150 · XRP $1.3320. US session market news, upcoming events, and what’s driving the week ahead
With no FOMC meeting and no single top-tier release dominating the calendar, this week is about triangulation rather than a binary outcome. Wednesday’s flash PMIs are the closest thing to a headline event — a strong composite reading paired with sticky selling-price inflation would reinforce the case for further tightening and could pressure equities and gold while supporting the dollar and yields, whereas a cooling in both activity and prices would support the “one-and-done” reading of last week’s hike. Housing data on Wednesday and Thursday will show whether near-5% long-end yields are starting to bite, and Friday’s final UMich survey is arguably the week’s most important single data point for Fed-watchers, since a confirmed jump in inflation expectations would validate the hawkish pivot while a downward revision would ease it. Meanwhile, crypto markets enter the week testing whether last week’s post-CLARITY-Act sell-off in XRP and BTC was a durable repricing or a one-time shock now largely absorbed.
The overriding story in US markets this week is less about a single scheduled event and more about how the economy and Fed officials respond to what just happened. The Federal Reserve delivered its first rate hike in more than three years on Wednesday, moving the target range to 3.75%-4.00% and citing persistent, energy-driven inflation pressure tied to the ongoing disruption in Gulf oil supply. Chair Kevin Warsh’s press conference and the updated dot plot leaned hawkish, initially dragging the S&P 500 and Nasdaq to their lowest levels since July before a two-day rebound Thursday and Friday, as crude oil eased on signs that Saudi Arabia is restoring flows through its East-West pipeline and Treasury yields pulled back from their highest levels since 2007.
That leaves this week’s US market outlook centered on confirmation rather than decision: with the Fed now out of its pre-meeting blackout period, a crowded slate of Fed speakers will be parsed closely for any signal on whether October or December could bring a follow-up hike, a pause, or a pivot back toward easing if the energy-price shock fades. Wednesday’s flash Manufacturing and Services PMIs are the week’s closest equivalent to a headline release, offering the first real-time read on whether business activity and selling-price inflation are cooling in the aftermath of the hike or continuing to run hot. Housing data — Existing Home Sales on Wednesday and New Home Sales on Thursday — will show how directly near-5% long-end yields are weighing on a rate-sensitive corner of the economy that has already shown signs of strain this year.
Away from the Fed, two other threads carry over from last week. First, Friday’s final University of Michigan Consumer Sentiment survey will confirm or revise the preliminary report’s sharp jump in both 1-year and 5-10 year inflation expectations, a detail the Fed itself flagged as a contributor to its hawkish shift — a further increase would reinforce the case for a restrictive stance, while a downward revision would offer some reassurance that expectations remain anchored. Second, crypto markets are still absorbing Tuesday’s failed Senate cloture vote on the CLARITY Act, which fell 11 votes short of the 60 needed to advance; XRP was hit hardest, sinking roughly 10% on the week, while Bitcoin proved comparatively resilient, recovering above $80,000 by Friday’s close. With no similarly scheduled crypto catalyst this week, the question is whether that stabilization holds or whether fresh headlines on the bill’s prospects reopen the selloff.
Four Forces That Will Drive the US Session — 21 to 25 September 2026
The scheduled catalysts and carry-over themes that will set the direction across equities, rates, commodities, and digital assets for the week of 21–25 September 2026
Key Support, Resistance & Technical Bias — 21 to 25 September 2026
Reference support/resistance zones and CSFX’s technical bias for the week’s eight core instruments, heading into a data-heavy but event-light week. All levels are for reference only and do not constitute financial advice.
Bias — Two-Sided Until PMIs and Fed-Speak Clarify the Path
The index rebounded into the weekend as oil and yields eased, but remains caught between resilient growth data and a Fed that has signaled willingness to hike again. A hot flash PMI paired with hawkish Fed commentary would likely revisit last week’s lows near 7,550, while a soft PMI print or dovish-leaning Fed speakers could extend the recovery toward 7,740-7,800. CSFX sees the path as choppy and headline-driven absent a single dominant catalyst.

Bias — Whether the Post-Fed Pullback Holds Is the Week’s Key Question
Yields retreated from 2007-era highs as oil eased, but a hawkish batch of Fed speakers or a hot flash PMI reading could reignite the move back toward 5.00%-5.10%. A confirmed jump in Friday’s UMich inflation-expectations data would add further upward pressure; continued softening in oil and a dovish Fed tone would be the clearest path back toward 4.75%.

Bias — Real Yields, Not the Fed Funds Rate, Are Now Driving Gold
Gold’s rebound despite a hawkish hike underscores that falling real yields — not the policy rate itself — are the metal’s key swing factor right now. CSFX would treat dips toward $4,300 as buying opportunities so long as oil and nominal yields stay contained; a renewed spike in either would risk a retest of the $4,235 low.

Bias — Thursday’s Canadian Retail Sales Is a Distinct, Fed-Independent Catalyst
The pair has pulled back as the immediate post-hike dollar bid faded, but a hawkish week of Fed-speak could revive the uptrend. Thursday’s Canadian Retail Sales print for July is a genuine two-way risk: Statistics Canada’s advance estimate already points to a 0.8% monthly decline, and a weak confirmed reading could pressure the loonie independent of anything the Fed does this week.

Bias — A Pure Read on Dollar Direction This Week
With no major Swiss-specific data on the calendar, USD/CHF is effectively a clean proxy for broader dollar sentiment this week. A hawkish tilt from Fed speakers or a hot flash PMI would likely push the pair back toward its 2026 high near 0.8207; a dovish tone or soft data would open the door toward the 0.7960 area.

Bias — Still Decoupled From the Broader Energy Complex
Natural gas has continued to trade its own supply-driven range even as crude oil swings on Gulf headlines, with domestic production and storage levels keeping rallies capped. CSFX would fade moves toward $3.00-$3.05 ahead of Thursday’s EIA storage report, with an unexpectedly large draw or an early-season cold snap the clearest upside risks to this bias.

Bias — Testing Whether the Post-CLARITY Act Recovery Holds
BTC proved the most resilient major token after last week’s failed cloture vote, recovering all of its post-vote losses by Friday. With no scheduled crypto catalyst this week, CSFX sees dips toward $77,000 as buyable for a retest of $82,000, so long as broader risk sentiment (equities, yields) doesn’t deteriorate sharply on hawkish Fed commentary.

Bias — Most Exposed to Any Fresh CLARITY Act Headline
As the token most directly tied to the US regulatory outcome, XRP bore the brunt of last week’s failed Senate vote and remains the most sensitive of the major tokens to any follow-up headline on the bill’s prospects. CSFX sees dips toward $1.25 as buyable within the current range, but a renewed bout of negative regulatory news is a real risk that could extend the slide toward $1.18.

US Economic Calendar — Week of 21–25 September 2026
The scheduled events that CSFX is watching most closely for the US session, 21–25 September 2026. All times Eastern; impact ratings reflect CSFX’s assessment of each release’s likely effect on US-session price action this week.
| Day | Time (ET) | Event | Impact | Period | Why It Matters |
|---|---|---|---|---|---|
| MONDAY, 21 SEPTEMBER | |||||
| Mon | — | No major US economic data | LOW | — | A quiet start to the week; markets continue digesting last week’s rate hike, with early appearances from Fed officials now free to speak after the pre-meeting blackout period ended. |
| TUESDAY, 22 SEPTEMBER | |||||
| Tue | — | No major US economic data | LOW | — | Another quiet session on the data front; attention stays on the broader run of Fed commentary and positioning ahead of Wednesday’s flash PMIs. |
| WEDNESDAY, 23 SEPTEMBER | |||||
| Wed | 7:00 AM | MBA Mortgage Applications | LOW | Weekly | A weekly gauge of mortgage demand, increasingly relevant with long-end yields still near multi-year highs despite last week’s pullback. |
| Wed | 9:45 AM | S&P Global US Manufacturing & Services PMI (Flash) | HIGH | September Prelim | The week’s closest equivalent to a headline event. August’s flash survey showed the fastest composite expansion since April 2022 alongside still-elevated input costs — a repeat of that pattern would reinforce the Fed’s hawkish tilt, while broad-based cooling would support a “one-off hike” reading. |
| Wed | 10:00 AM | Existing Home Sales | MED | August | The first housing read since the hike, offering an early sense of how near-5% long-end yields are affecting the resale market. |
| THURSDAY, 24 SEPTEMBER | |||||
| Thu | 8:30 AM | Initial & Continuing Jobless Claims | MED | Weekly | Claims have held near multi-decade lows; any deviation will be read closely for early signs of post-hike labor-market softening. |
| Thu | 8:30 AM | Canadian Retail Sales | MED | July | A distinct, Fed-independent catalyst for USD/CAD. Statistics Canada’s advance estimate points to a 0.8% monthly decline; a weaker-than-expected confirmed print would pressure the loonie regardless of what the Fed signals this week. |
| Thu | 10:00 AM | New Home Sales | MED | August | A more forward-looking housing gauge than existing sales, capturing contract signings and offering a cleaner read on demand at current mortgage-adjacent rates. |
| Thu | 10:30 AM | EIA Natural Gas Storage Report | MED | Weekly | Natural gas has traded a tight range on ample supply; another large storage build would reinforce the oversupply narrative even as broader energy markets stay sensitive to Gulf headlines. |
| FRIDAY, 25 SEPTEMBER | |||||
| Fri | 8:30 AM | Durable Goods Orders | MED | August Prelim | July’s headline orders rose 1.1%, with a 0.4% gain even excluding transportation. Continued strength would support the case that business investment is holding up under restrictive policy; a broad-based decline would add to evidence of slowing momentum. |
| Fri | 10:00 AM | University of Michigan Consumer Sentiment (Final) | HIGH | September Final | Arguably the week’s most important single data point for Fed-watchers. The preliminary report showed 1-year inflation expectations jumping to 4.6% from 4.0% and 5-10 year expectations edging up to 3.4% — confirmation of those increases would reinforce the case for a restrictive Fed stance, while a downward revision would offer reassurance that expectations remain anchored. |
CSFX View: A Data-Digestion Week Tests Whether the Fed’s Hawkish Pivot Is Durable
The week of 21–25 September 2026 hands the US session a quieter but no less consequential calendar than last week’s FOMC decision. With the Federal Reserve’s benchmark rate now at 3.75%-4.00% after its first hike in years, the S&P 500 at 7,650.50 sits roughly where it started last week after a volatile round trip, the 10-year Treasury yield at 4.96% has pulled back from an 18-year intraweek high near 5.02%, and gold at $4,368.60 has recovered from a six-week low as falling oil and easing yields pulled real rates back down. USD/CAD at 1.3790 and USD/CHF at 0.8090 both reflect a dollar that has given back some of its immediate post-hike gains, while Bitcoin near $80,150 has fully recovered from last week’s post-CLARITY Act dip even as XRP at $1.3320 remains the most visibly scarred by the failed Senate vote.
CSFX’s framework for the week centers on confirmation rather than a single binary catalyst. Wednesday’s flash PMIs are the closest thing to a headline event: a repeat of August’s pattern — fast growth alongside sticky selling-price inflation — would reinforce expectations that Wednesday’s hike is the start of a more sustained tightening path, while a broad-based cooling in activity and prices would support the view that the Fed delivered a targeted, one-time response to an energy-driven inflation shock. With the pre-meeting blackout period over, a crowded schedule of Fed speakers adds another layer: markets will parse every appearance for hints on October and December, and any deviation from the hawkish tone struck at Wednesday’s press conference could move yields and the dollar meaningfully.
Housing and consumer data round out the picture. Wednesday’s Existing Home Sales and Thursday’s New Home Sales will show how directly near-5% long-end yields are weighing on a rate-sensitive part of the economy, while Friday’s final University of Michigan Consumer Sentiment survey carries outsized importance given the Fed explicitly cited rising inflation expectations as part of its reasoning for hiking. On the crypto side, this week is a stabilization test rather than a fresh catalyst: with no scheduled legislative event on the CLARITY Act, BTC and XRP price action will largely reflect whether last week’s post-vote shock has been fully absorbed or whether fresh regulatory headlines reopen the selloff, particularly in XRP. CSFX will issue intra-week updates if Wednesday’s PMIs, Friday’s UMich survey, or any Fed commentary surprise materially in either direction.
New clients can also take advantage of a limited-time deposit bonus when they open an account this week, on top of the usual account benefits — tight spreads, high leverage, and access to 2000+ instruments across FX, commodities, indices, and crypto.
Trade US Markets at CSFX →