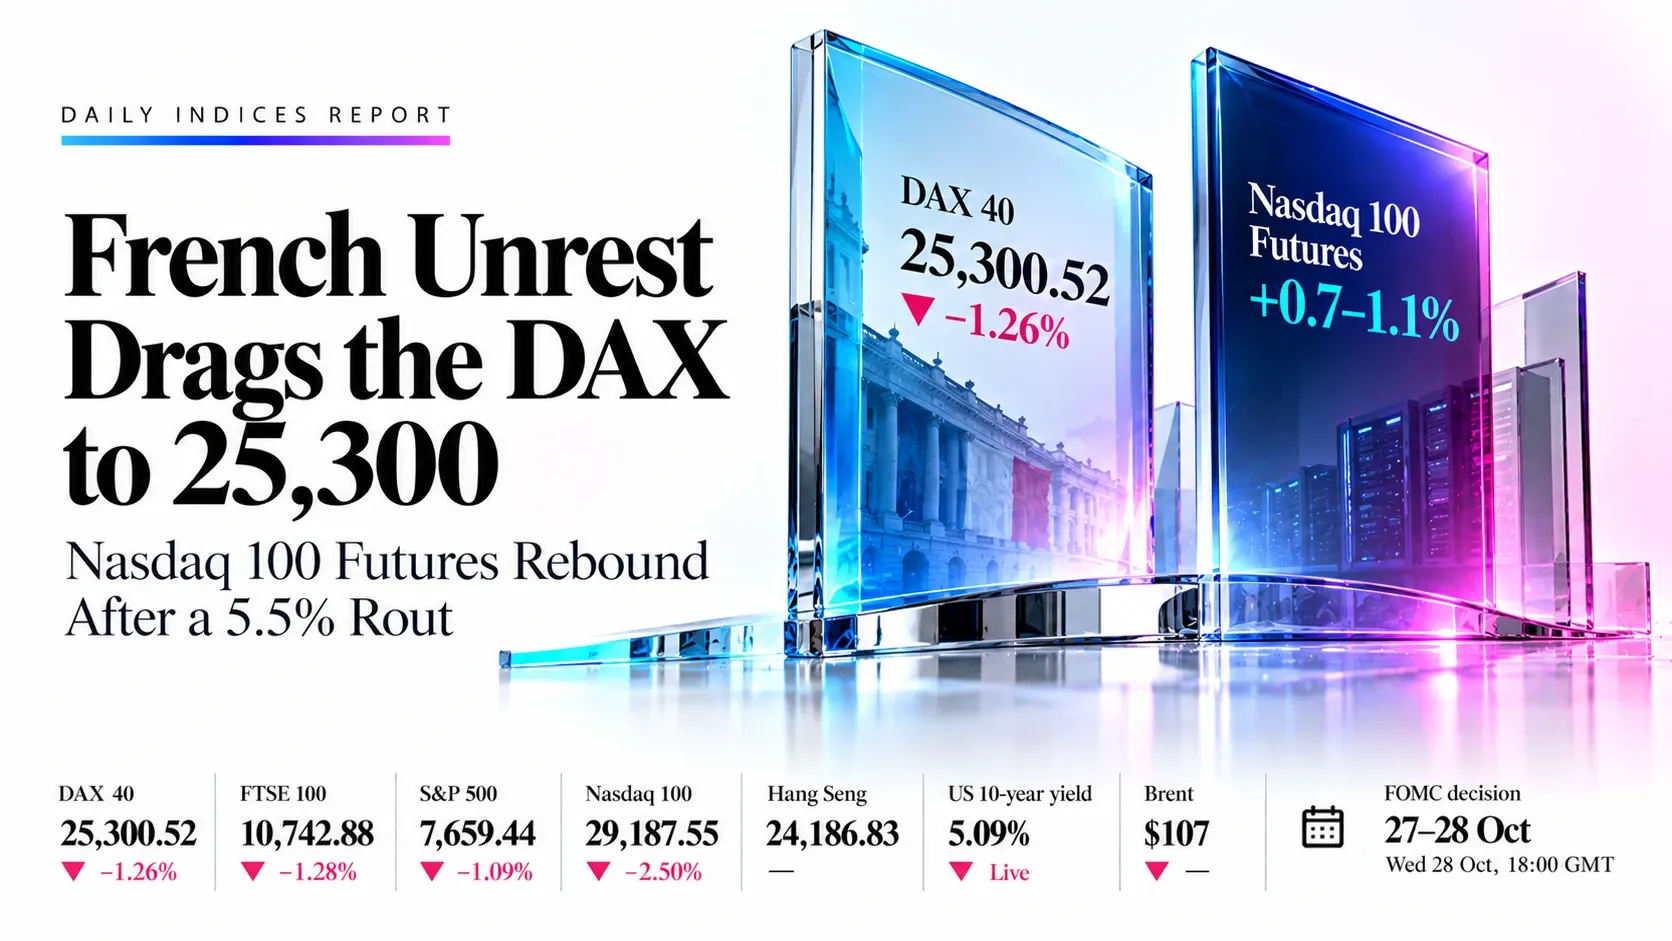
Nasdaq 100 Futures Rebound After a 5.5% Rout as French Unrest Drags the DAX to 25,300 | Technical Analysis – Index Report | 19 Oct 2026
Indices Today | Monday 19 October 2026
Nasdaq 100 Futures Rebound After a 5.5% Rout as French Unrest Drags the DAX to 25,300
Market Overview
European equities fell at midday as violent weekend protests in France hit banks, with the DAX at 25,300.52 (−1.26%) and the FTSE 100 at 10,742.88 (−1.28%) at 12:47 GMT; Barclays also dropped after a report that the Bank of England is examining its private-credit trading (Reuters). Wall Street is set for a bounce, with Nasdaq 100 futures up about 0.7–1.1% and S&P 500 futures up 0.4–0.8% after the worst week since June, when AI-funding worries cut the Nasdaq 100 by 5.5% (Bloomberg). The US 10-year yield eased to about 5.09% and Brent slipped to about $107 after Washington waived some Russia sanctions. The Hang Seng is closed for a Hong Kong holiday and last ended at 24,186.83. The next catalysts are SpaceX and Netflix results on Tuesday, Meta and Tesla on Wednesday, UK inflation at 06:00 GMT on Wednesday and the Fed on 28 October. We read the session as a dip-buying attempt inside a weaker tech trend.
Key highlights
- Wall Street: The S&P 500 closed Friday at 7,659.44 (−1.09%), down 1.95% on the week; the Nasdaq 100 fell 2.50% to 29,187.55 and closed below its rising channel.
- Europe: The DAX gave back Friday’s 1.0% gain, and the Stoxx 600 trades 0.4–0.8% lower, with the French CAC 40 down more than 1% on the unrest.
- UK: The FTSE 100 ended a three-day run after its best week in six months (+3.1%, to 10,881.90), led lower by banks, miners and defence stocks.
- Hong Kong: The market is shut today and reopens Tuesday at 01:30 GMT; China’s third-quarter GDP grew 4.5% year on year against 4.4% expected.
- Fed and yields: September US CPI rose 3.7% and producer prices 6.3% year on year; officials are in a blackout until 29 October, and December hike bets outweigh October.
- Earnings: Meta, Tesla, SpaceX, Netflix, IBM, GE Aerospace and General Motors report this week, testing the AI-spending story.
What’s Moving Indices Today
French unrest weighs on banks and the euro
Nationwide protests over living costs turned violent at the weekend, and the CAC 40 slid over 1% while the Stoxx 600 fell. Moody’s is due to review France’s Aa3 rating, which carries a negative outlook, on Friday.
AI stocks bounce after the worst week since June
Nasdaq 100 futures rose about 1% in early trade after the index lost 5.5% last week on fears that higher rates and debt will limit AI data-centre spending. CoreWeave and Broadcom were higher in premarket trading, while Meta’s Wednesday report is the next test.
Barclays probe and oil above $107 drag London
The Financial Times reported the Bank of England is checking whether Barclays traders understated the risk of illiquid private-credit loans; Barclays fell about 2.7% and the financial sector 1.8%. Miners and defence stocks lost about 2% each.
Hot inflation keeps a Fed hike in play
Fed Chair Kevin Warsh gave no signal on October, and estimates put the odds of a hike on 27–28 October between roughly 16% and 30%, with December more likely. Easing Treasury yields help equities today, but a hot PMI or inflation print could reverse that.
Key Drivers Today
Five readings and events that set direction for indices. All times are GMT.
- US 10-year yield
- ~5.09%
- Eased on AI funding fears
- UK CPI
- Sep, y/y
- Consensus 3.4%, prior 3.1%
- Meta and Tesla earnings
- Q3
- SpaceX, Netflix Tue 20 Oct
- Flash PMIs
- Oct
- Eurozone, UK and US
- FOMC decision
- 27–28 Oct
- Fed blackout until 29 Oct
Swipe the strip to see every driver.
Trade Setups for Today
Ranked by conviction and valid for today’s session. A 1-hour close beyond the stop cancels the idea.
| Instrument | Direction | Entry | Stop | Target 1 | Target 2 | Reward:risk | Conviction |
|---|---|---|---|---|---|---|---|
| Hang Seng | Short | 24,420 | 24,720 | 23,800 | 23,450 | 2.1 / 3.2 | Medium |
| FTSE 100 | Long | 10,715 | 10,625 | 10,885 | 11,000 | 1.9 / 3.2 | Medium |
| DAX 40 | Short | 25,430 | 25,720 | 25,000 | 24,820 | 1.5 / 2.1 | Medium |
| Nasdaq 100 | Short | 29,550 | 29,900 | 29,000 | 28,500 | 1.6 / 3.0 | Medium |
| S&P 500 | Short | 7,700 | 7,760 | 7,600 | 7,520 | 1.7 / 3.0 | Low |
Reward:risk is the distance from entry to each target divided by the distance from entry to the stop. Prices are index levels: the DAX 40 and FTSE 100 are live at 12:47 GMT, the Nasdaq 100 and S&P 500 are Friday’s cash closes (futures trade higher today) and the Hang Seng is Friday’s close because Hong Kong is shut. Levels are conditional technical references, not recommendations.
AI Earnings Scenario Analysis
The AI spending story is the swing factor for US indices and, through yields, for Europe and Hong Kong. Meta’s Wednesday report after the US close is the main test.
Funding stress: AI spending doubts deepen
Cautious spending guidance or more credit strain at data-centre operators would revive last week’s rout, while hot PMIs keep yields high and a December Fed hike in play.
- Nasdaq 10029,000, then 28,500
- S&P 5007,600, then 7,520
- Fed December hike pricingRises
Earnings relief: results calm the AI trade
Strong Meta and Tesla results, with firm spending plans funded by cash flow, would stabilise tech and let eased yields support a recovery toward the broken channel lines.
- Nasdaq 10029,620, then 29,870
- S&P 5007,706, then 7,760
- Fed December hike pricingFades
Hang Seng | Hong Kong HSI, index points
Hang Seng Analysis: Holiday Close Leaves Price Under Every Average in a Falling Channel
24,186.83 +124.11 (+0.52%) last close, 16 Oct Range 24,087.23–24,392.30
Outlook: Bias is lower while 24,420 caps rallies. Hong Kong is shut today for a public holiday and reopens Tuesday at 01:30 GMT, so the index trades on Friday’s close; a firm China growth print supports, but tech weakness and a falling channel since August keep rebounds shallow.
Key levels
- Support 2
- 23,400
- Support 1
- 23,800
- Resistance 1
- 24,420
- Resistance 2
- 24,800
- All three averages (24,418.35, 24,798.75 and 24,985.57) slope down above price; the first is the nearest hurdle and the channel top sits near 25,100.
- RSI 43.12 is above its signal line at 39.70 but under 50, a recovery from near-oversold rather than a trend change. The October low near 23,800 is the first floor.
Setup: Short at 24,420, stop 24,720, targets 23,800 and 23,450. Reward:risk 2.1 / 3.2, medium conviction.
FTSE 100 | UK 100 index, index points
FTSE 100 Analysis: Barclays Probe Pulls Price Back to the Broken Channel Line
10,742.88 −139.03 (−1.28%) at 12:47 GMT Day range 10,737.23–10,889.90
Outlook: Bias is mildly higher while 10,714 holds, but today’s retest is a test. A Financial Times report that the Bank of England is examining Barclays trading, plus oil above $107, ended three straight gains after the index’s best week in six months.
Key levels
- Support 2
- 10,630
- Support 1
- 10,714
- Resistance 1
- 10,885
- Resistance 2
- 11,000
- Price sits just above the 10,713.59 average, with 10,638.55 and 10,629.75 stacked beneath; the rising line from March near 10,420 is the larger floor.
- RSI 54.36 is above its signal line at 45.94 after turning down from a higher reading, a neutral-to-firm reading that favours buying dips only above the averages.
Setup: Long at 10,715, stop 10,625, targets 10,885 and 11,000. Reward:risk 1.9 / 3.2, medium conviction.
DAX 40 | German DAX, index points
DAX 40 Analysis: French Unrest Keeps Price Inside the Falling Channel
25,300.52 −322.09 (−1.26%) at 12:47 GMT Day range 25,262.82–25,540.88
Outlook: Bias is lower while 25,430 caps rallies. Violent weekend protests in France and a Moody’s review of the country’s rating on Friday weigh on European banks, while the Stoxx 600 trades 0.4–0.8% lower.
Key levels
- Support 2
- 24,400
- Support 1
- 24,820
- Resistance 1
- 25,430
- Resistance 2
- 25,700
- Price is level with the 25,282.60 average and beneath the 25,428.20 and 25,700.05 averages; the channel top near 25,650 aligns with the highest average.
- RSI 48.02 is above its signal line at 44.74 but under 50, a balanced reading. The October low near 24,820 is the first floor.
Setup: Short at 25,430, stop 25,720, targets 25,000 and 24,820. Reward:risk 1.5 / 2.1, medium conviction.
Nasdaq 100 | US Tech 100 index, index points
Nasdaq 100 Analysis: Close Below the Channel Floor Meets a Futures Bounce
29,187.55 −748.05 (−2.50%) Friday close Day range 29,073.29–29,822.91
Outlook: Bias is lower while 29,620 caps rallies. The index closed below its rising channel after a 5.5% weekly drop, its largest since April 2025; futures are up about 0.7–1.1% on Monday, and Meta and Tesla results on Wednesday decide whether the bounce lasts.
Key levels
- Support 2
- 28,500
- Support 1
- 29,000
- Resistance 1
- 29,620
- Resistance 2
- 29,870
- All three averages (29,621.16, 29,868.00 and 30,524.22) sit above price, and the channel floor near 29,600 is now resistance; the 29,073 Friday low and the September lows near 29,000 are the next support.
- RSI 35.23 is far below its signal line at 57.69, a weak reading near oversold that argues for selling bounces rather than chasing the fall.
Setup: Short at 29,550, stop 29,900, targets 29,000 and 28,500. Reward:risk 1.6 / 3.0, medium conviction.
S&P 500 | US 500 index, index points
S&P 500 Analysis: Range Support Near 7,600 Tested as Earnings Loom
7,659.44 −84.62 (−1.09%) Friday close Day range 7,631.77–7,756.84
Outlook: Bias is neutral to lower while 7,706 caps rallies. The index fell 1.95% last week on AI-funding fears and hot inflation, futures are up about 0.4–0.8% today, and the broad range since August keeps both sides open.
Key levels
- Support 2
- 7,520
- Support 1
- 7,600
- Resistance 1
- 7,706
- Resistance 2
- 7,760
- Price sits between the 7,706.42 and 7,597.95 averages, with a further average at 7,739.24 overhead; the channel floor near 7,520 is the larger support.
- RSI 44.12 is below its signal line at 54.59, a soft reading that fits a range rather than a trend break.
Setup: Short at 7,700, stop 7,760, targets 7,600 and 7,520. Reward:risk 1.7 / 3.0, low conviction.
Conclusion
Wall Street futures are rebounding, but the Nasdaq 100’s close below its channel and the unrest in France keep the bias lower for the Nasdaq 100, S&P 500, DAX and Hang Seng. We prefer selling rallies into resistance in those four, and buying the FTSE 100 only while it holds above 10,714 on the retest of its breakout. The nearest risks are SpaceX and Netflix on Tuesday after the US close, UK CPI at 06:00 GMT on Wednesday, Meta and Tesla on Wednesday after the US close, flash PMIs on Friday and the Fed on 28 October at 18:00 GMT. A daily close above 29,870 on the Nasdaq 100 would challenge the bearish view.
Trade the Hang Seng, FTSE 100, DAX 40, Nasdaq 100 and S&P 500 with Capital Street FX.
Frequently Asked Questions
Why is the Hang Seng not trading today?
Hong Kong’s market is closed for a public holiday on Monday 19 October, so the quote shown is Friday’s close. Trading resumes on Tuesday at 01:30 GMT, and the index can gap on the day’s global moves.
Why do higher bond yields hurt tech stocks like the Nasdaq 100?
Tech valuations rest on profits far in the future, which are worth less when yields rise. Higher rates also raise borrowing costs for firms funding data centres with debt, which is the worry behind last week’s selloff.
How do French protests affect the DAX?
French political risk lifts eurozone borrowing-cost fears and hits banks and luxury groups that trade across Europe. Germany’s DAX tends to fall in sympathy, though less than the French CAC 40.
Why does the FTSE 100 have less AI exposure than US indices?
The FTSE 100 is weighted toward banks, miners, energy, defence and consumer goods rather than technology. That helped it last week, when tech fell, but it leaves it exposed to bank and commodity news such as today’s Barclays report.