NFP Effect on Markets: Half-Baked, Fully Priced | Daily Blog
NFP Effect on Markets: Half-Baked, Fully Priced
How 73,000 replies, a gap-filling model, some heroic seasonal maths and three rewrites became the number the world’s traders set a 4 a.m. alarm for
An affectionately irreverent history of Non-Farm Payrolls: the monthly jobs report that sends gold, the dollar, bonds and stocks into a sixty-second frenzy, gets quietly corrected for the next twelve months, and is still greeted every first Friday as though it were the final word on the US economy. With charts, a hall of fame, the volume data, a trading plan and a look at what happens when nobody has a payroll job and the market never closes.

Non-Farm Payrolls is an educated estimate that the market trades as if it were a headcount. It is built from a partial sample, topped up with a model, bent into shape by seasonal adjustment and then revised, revised again and benchmarked a year later. The statisticians say all of this, clearly and in writing. Nobody on a trading floor has ever let that get in the way of a good spike.
This article follows the gap between how seriously the number is taken and how much it actually knows: where it came from, how it is made, how often it changes its mind, what it does to prices, and how traders can make that gap work for them rather than against them.
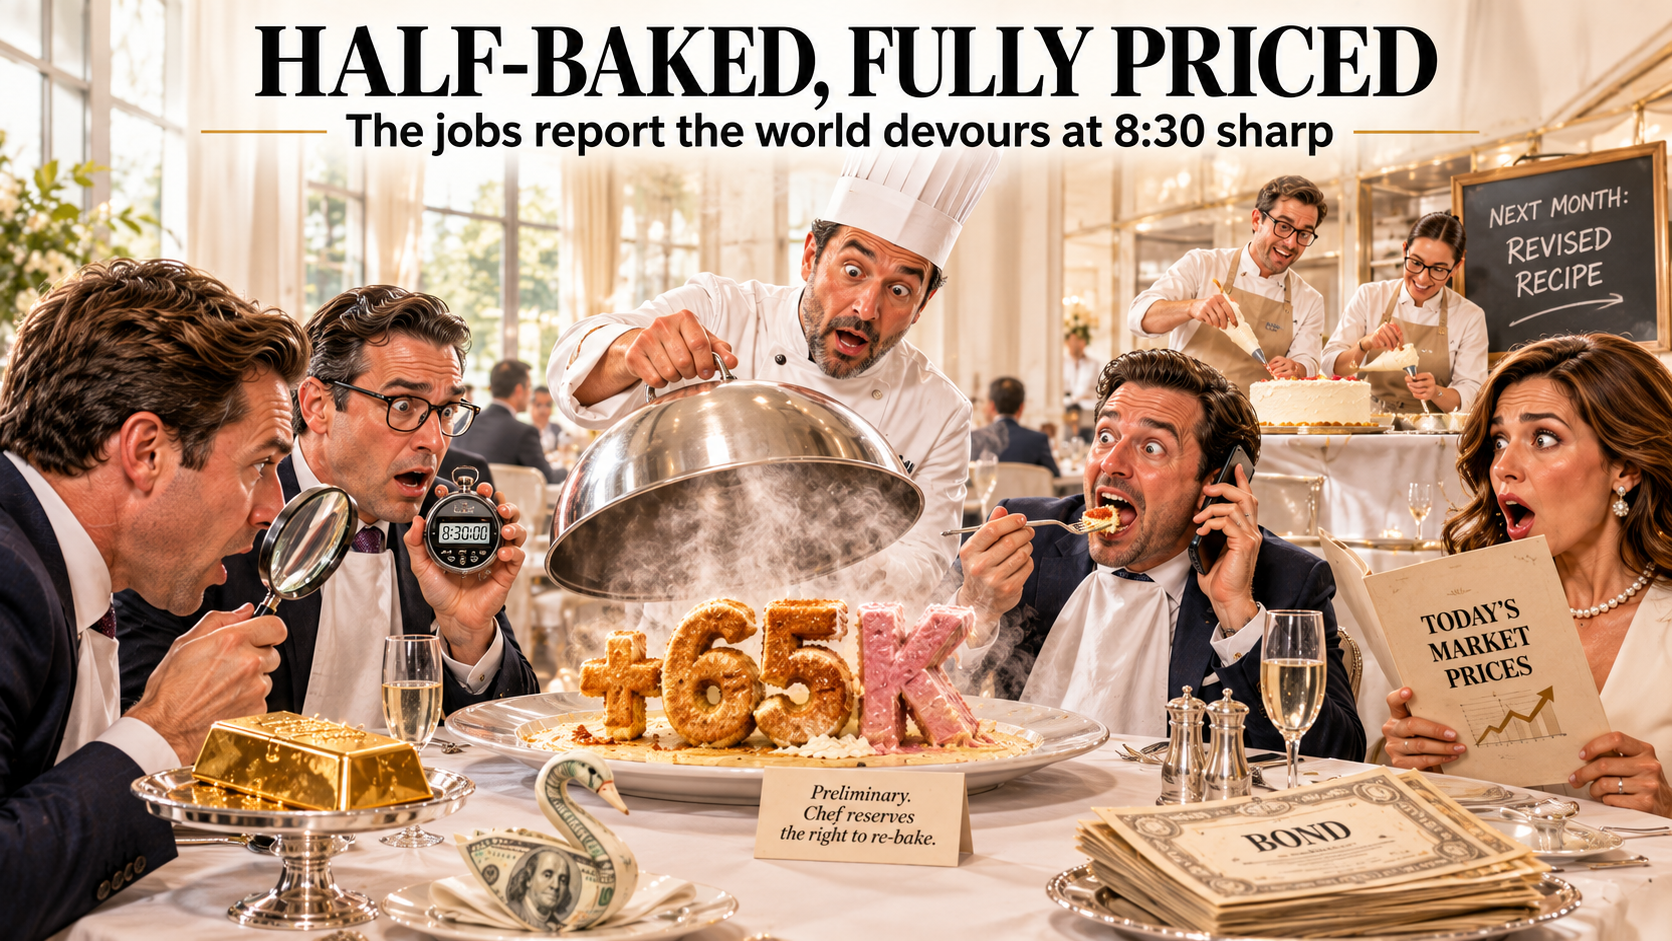
At 8:30 a.m. in New York, on the first Friday of the month, a large part of the financial world stops blinking. Traders have been up since the small hours in Tokyo, London, Dubai and a converted garage in Ohio with three monitors and a cat. Around 80 economists have filed forecasts to the nearest thousand for a number that is measured to the nearest 136,000. A consensus has been calculated, a “whisper number” has done the rounds like office gossip, and a fund in Connecticut has paid roughly the cost of a hospital wing to see the figure eleven milliseconds before you. A man in Lisbon holds a leveraged long in gold and a cold espresso. Then the number lands.
Within a minute, interest-rate futures trade at nearly ten times their usual pace, FX futures at nearly twelve and equity futures at more than five (source: CME Group). The dollar lurches, gold twitches, yields jump, and somewhere a retail stop is filled at a price that existed for roughly the length of a hiccup. By 8:32, someone on social media has explained exactly why it happened. By 8:33, someone else has explained, with equal confidence, why it happened for the opposite reason.
The first-Friday routine
A typical release day, as experienced by roughly everyone with a trading account.
The tiles at the top tell the rest. The survey covers about a third of America’s payroll jobs, and when the headline is first published only about six in ten of the sampled employers have replied (sources: BLS, CRS). The other jobs in the economy are represented, in effect, by the confidence of the ones that answered. The result carries a margin of error of about ±136,000, larger than the headline itself in five of the nine months so far this year (derived from BLS data). A print of +50,000 is, statistically speaking, compatible with a hiring spree, a hiring freeze and everything in between. Markets will nonetheless move as if it were a hiring spree, or a hiring freeze, depending on the mood.
None of this is a scandal. The Bureau of Labor Statistics does careful work on a modest budget and publishes every caveat in full. The comedy belongs entirely to the rest of us, who hear “+150,000, give or take a medium-sized city” and trade as though we heard “+150,000, carved in granite.” The index above follows that relationship, from Gilded Age freight cars to markets that never close.
How the Gilded Age guessed at the economy
No jobs data, plenty of opinions, and one very expensive library.
Picture a trader in 1887: a telegraph, a cigar, and no idea how many Americans have jobs. Nobody does. The country has not yet noticed that it has a labour market, as distinct from labour. The Bureau of Labor was only created in 1884, under a commissioner, Carroll Wright, whose great gift was turning other people’s complaints into tidy tables. So the traders improvised, and their proxies were gloriously physical.
The 1880s macro dashboard
What passed for economic data before payrolls existed. Refresh rate: weekly, if the telegraph was working.
The Wall Street Journal, founded in 1889, printed all of it with a straight face. The 1890 census used Herman Hollerith’s punch-card tabulators and still arrived about as fast as an oxcart. The results were often catastrophic. The Panic of 1893 closed hundreds of banks and thousands of firms; later historians would reconstruct unemployment well into double digits, a number no contemporary could have told you, because nobody was counting. In 1907, with the system collapsing, the nation’s rescue plan was J. P. Morgan, who reportedly locked the city’s leading bankers in his library until they agreed to a deal. It remains the only data release in history delivered by deadbolt.
Before the jobs report, the market’s jobs report was a man named Morgan and a locked door.
How a statistic acquires a fan club
From a Depression-era gap in the data to the most over-caffeinated minute in finance.
The Depression finally pushed Washington into counting. In 1929 America could report its pig-iron output more precisely than its unemployment, which tells you something about priorities. Through the 1930s the monthly payroll survey was assembled, and in 1940 a separate household count of the jobless began. Frances Perkins, Roosevelt’s Labor Secretary, spent a career demanding facts from people who preferred anecdotes, which makes her the honorary founder of every Friday-morning trading desk, and possibly the reason they all drink so much coffee.
From footnote to headline
Scroll sideways. Sources: BLS history; CME Group (2013); Federal Reserve Bank of Richmond; Reuters; Jones Day.
The number got a fan club almost by accident. Postwar economists made employment a national goal; Congress wrote it into the Fed’s mandate; and once the Fed stopped targeting the money supply in the 1980s, the jobs report inherited the spotlight (source: CME Group, 2013). Academics started calling the employment report the “king” of economic announcements, which is a lot of pressure for a survey that can’t always get a reply. Nobody planned any of it. It simply happened, one Friday at a time, the way most traditions do.
A survey, a model and a great deal of arithmetic
Every great number has its fine print. This one has a lot of it, and it’s rather good reading.
The establishment survey asks about 121,000 businesses and government agencies, covering roughly 631,000 worksites and about a third of all payroll jobs, one question that matters: how many people were on the payroll in the pay period that includes the 12th of the month (source: BLS). Not the month. One pay period. If a hurricane, a strike or a long weekend lands in the wrong week, the survey records it faithfully and the market reacts as if the economy had changed its mind. It also counts jobs, not people, so someone with three part-time jobs is three jobs, and the entire self-employed population is not counted at all.
From 159 million jobs to one headline
Sources: BLS (sample, coverage); CRS (2024 collection rate). The last step is derived; the confidence is extra.
The response rate is the quiet issue. When the first estimate is published, after 10 to 16 days of collection, about 60.4% of the sample has replied; by the second estimate it is 89%, by the third 90.9% (source: CRS, 2024 averages). The market, naturally, trades the 60% version with the most enthusiasm. The underlying willingness to answer is fading too: the survey’s response rate fell from about 58% before 2020 to 43% in 2024 (source: CRS), and the household survey behind the unemployment rate slid from about 90% in 2013 to below 70% by 2024 (source: Federal Reserve Bank of Atlanta). Americans will happily share their location, heart rate and sleep cycle with an app, but not their headcount with a government statistician.
Then comes seasonal adjustment. Employment swings wildly through the year, with retailers hiring for Christmas and letting everyone go in January, so the raw count is compared with what a typical month looks like. The adjustment is not a rounding error. It is most of the story, as the chart shows.
2026, before and after the arithmetic (thousands)
Sources: unadjusted change and birth-death contribution: BLS CES birth-death table; adjusted headline: BLS series (22 Oct 2026). Aug–Sep unadjusted figures are preliminary.
In January 2026, America’s raw payrolls fell by 2,630,000. Adjusted for the fact that they always fall in January, the headline said +160,000, and the market celebrated a decent start to the year. In July the raw count fell by 1,025,000 and the headline said −10,000 (derived from BLS data). Both are perfectly correct, which is the clever part and also the joke: the market trades a statement about how this January compares with an average January, delivered as though someone had walked the aisles with a clipboard. And in October 2025 there was no household survey at all. A 43-day government shutdown stopped collection, and the BLS confirmed that the October unemployment rate could never be recovered (source: Reuters via GV Wire). The world’s most closely watched labour market now has a month that officially did not get measured.
The nutrition label
What is inside a headline. Please read before trading.
Payrolls Facts
Thirty-six years of readings, as they stand today
Booms, busts, a telephone strike and the strangest spring in history.
Here is every monthly reading from January 1990 to September 2026 as it stands now, after all the revisions and benchmarks have had their say (source: BLS series, 22 October 2026). Tap a bar or change the era; the 2020 collapse is clipped so it doesn’t flatten the rest of the century.
Monthly payroll change, settled values (thousands)
Source: BLS CES0000000001 via useconomicdata.com snapshot of 22 Oct 2026. Bars beyond ±1,000k are clipped. “Settled” means “for now.”
The 1990s added around 200,000 jobs a month and barely flinched. The 2001 and 2008 recessions show up as long red valleys, bottoming at −824,000 in March 2009. Then April 2020: −20,469,000, the lowest reading on record, a figure so large it needed its own chart. Two months later came +4,631,000, the highest. And there are oddities: September 1983 shows +1,118,000 straight after a −308,000 August, which was not a boom and a bust but a telephone strike ending. Steel strikes in 1952 and 1956 did the same. The most important number in finance has, on occasion, been written by a picket line.
The extremes, at a glance
Derived from the series above (Jan 1990–Sep 2026) and the sources noted.
The long-run average since 1947 is about 121,000 a month, with a median of 156,000. Recent years form a staircase: 606,000 a month in 2021 (the reopening), 377,000 in 2022, 210,000 in 2023, 122,000 in 2024, 10,000 in 2025 and about 68,000 so far in 2026. The labour market has not so much cooled as taken the stairs, one careful step at a time, holding the banister.
Average monthly job gain: by era and by recent year
Derived from the series above (2020s = Jan 2020–Sep 2026). Recent years: BLS calendar-year averages.
| Recession | At peak | At trough | Worst month | Best in recovery |
|---|---|---|---|---|
| Jul 1990–Mar 1991 | −35 | −167 | −323 (Feb 1991) | +77 (Jun 1991) |
| Mar–Nov 2001 | −37 | −308 | −311 (Oct 2001) | +115 (Oct 2002) |
| Dec 2007–Jun 2009 | +105 | −458 | −824 (Mar 2009) | +522 (May 2010) |
| Feb–Apr 2020 | +262 | −20,469 | −20,469 (Apr 2020) | +4,631 (Jun 2020) |
That is the record as the history books will tell it. But history books are written from settled numbers, and the market has never traded a settled number in its life. It trades first drafts, at full size, with leverage.
First draft, second draft, final draft, benchmark
The number that changes its mind more often than a trader with a stop-loss.
Below, the first release for 26 consecutive months (July 2023 to September 2025; February 2025 omitted because its first print could not be sourced) is set against today’s value and against the consensus the market had positioned for. Red is what moved prices. Green is what actually happened, eventually.
Consensus vs first print vs settled value (thousands)
Sources: first prints and consensus: forexfundamentals NFP release table; settled: BLS series (22 Oct 2026). Tap a bar.
The average first print was about +189,000; the average settled value about +101,000. Of 26 first prints, 23 were later revised down, a hit rate that would make any forecaster proud if it were the forecast. The typical revision (about 93,000) was bigger than the typical surprise against consensus (about 71,000) that actually moved prices. In 9 of the 26 months, the settled number landed on the other side of consensus: the market that sold the “beat” had, with hindsight, sold a miss. Economists, meanwhile, deserve credit. Their forecasts often land impressively close to the first print, which is quite an achievement given that the first print is only within 136,000 of the truth.
Jobs created per year: as reported at the time vs settled (thousands)
Sources: as-previously-reported totals: Ritholtz/BLS; settled: BLS series. 2025 lost about nine-tenths of itself along the way.
The annual audit is tougher still. The February 2026 benchmark cut the March 2025 payroll level by 898,000 jobs, 0.6% of all employment and the largest downward benchmark since 2009; since 1979, benchmarks have typically stayed within ±0.2% (source: First Trust, citing BLS). By calendar year, 2025’s job creation went from a reported 1,208,000 to 116,000 today, which is less a revision than a rewrite. Since 2003, the average monthly revision has been about 51,000 jobs either way, with extremes of −672,000 (March 2020) and +437,000 (November 2021) (source: CRS). The May–June 2025 revision of −258,000 was the largest two-month cut since at least 1978 outside the pandemic (source: Federal Reserve Bank of Richmond), and on the day it was published, 1 August 2025, President Trump dismissed BLS Commissioner Erika McEntarfer (source: Charles Schwab). The number now carries weight well beyond the trading floor.
The crowd, the average move and the fifteen days that made the legend
Less than the legend says, faster than you’d think, and occasionally unforgettable.
Every first Friday the same cast assembles. They are all very good at their jobs, and all slightly ridiculous for about ten minutes.
A field guide to the 8:30 crowd
Spot them in the wild, usually between 8:29 and 8:35 New York time.
What do they actually achieve? In the first fifteen minutes, gold typically moves about a quarter of one percent, and EUR/USD and GBP/USD by similar fractions, with weak prints producing the bigger reaction (sources: FXStreet studies of 13 releases to July 2021 for the pairs and 35 releases to January 2025 for gold; percentages derived). Over the whole day, the 10-year yield moves about twice a normal day (8.5bp against 4.3bp) and the 2-year about 2.35 times (source: macroornoise.com, 36 releases, 2023–25); the S&P 500 averages 1.05% against 0.65% normally, and small caps 1.70% (source: Russell Rhoads, 2023).
How far do things move? Four ways to look
Published averages (sources above); percentage conversions and 2007–13 ratios derived.
The archive has a lovely detail. Between 2007 and 2013, payrolls days widened the 10-year T-note futures’ daily range by a third and the Eurodollar range by nearly 40%, yet the E-mini S&P 500 actually finished NFP days with a slightly smaller close-to-close move than an average day (source: CME Group, 2013). Stocks had a dramatic morning every first Friday and then, by the closing bell, had largely forgotten what the fuss was about. Averages, though, are for actuaries. Legends are made on particular Fridays.
The hall of fame: what was printed, what was true, what moved
Fifteen documented release days, 1986–2026. “Settled” is today’s BLS value for the month reported (derived). Consensus figures vary by survey. Tap a date.
Look closely and a pattern appears. Many of the most famous days were reactions to numbers that later changed. The dismal 39,000 of November 2010 grew up to be 129,000. The perfect zero of August 2011 became 133,000. The 517,000 that knocked gold flat in February 2023 now reads 434,000. The 114,000 that helped set off the August 2024 carry-trade unwind now reads 53,000. The market’s greatest hits were performed to a backing track that was later re-recorded, and nobody asked for a refund.
The legends, first print vs settled (thousands)
Ten hall-of-fame days with both values available (June 2020 left out for scale; October 2026 not yet revised).
The three most recent reports show the whole routine in miniature. In August, jobs fell and stocks hit a record. In September, jobs beat and stocks fell. In October, a miss lifted gold and bonds on the headline; by the close both had reversed, the market having decided over lunch that inflation mattered more than jobs after all (sources: Reuters, CNBC, CME Group, CoinCentral, Eurasia Business News). Three releases, three different logics, one very busy set of commentators.
The three most recent reports
The sixty-second stampede and the whole-day shrug
The busiest minute on the calendar, followed by a surprisingly ordinary afternoon.
CME Group’s economists measured futures volume against data surprises from January 2021 to January 2025. On a no-surprise day, the first minute after 8:30 sees about 20,663 interest-rate futures, 1,704 FX futures and 3,395 equity-index futures trade. After a one-standard-deviation payrolls surprise, that becomes about 194,836, 19,836 and 18,205: roughly 9, 12 and 5 times normal, all in the time it takes to read the headline twice. No other release comes close; a CPI surprise adds only 20,000 to 30,000 rate contracts (sources: CME Group, July and August 2025). Options traders start fidgeting the day before: 10-year Treasury options expiring on payrolls day trade at visibly higher implied volatility than later expiries (source: CME Group, June 2024).
Futures contracts traded around the report
Sources: CME Group Economic Research (2025; Jan 2021–Jan 2025) and CME Group, “Impact of Economic Indicators” (2013; Jan 2007–May 2013). Baseline = no-surprise day.
Now the punchline. Over the whole day, the headline surprise adds nothing statistically meaningful to FX or equity futures volume (p ≈ 0.86 and 0.74). The headline gets all the attention and leaves no trace in the daily totals. What does move whole-day volume is the unemployment-rate surprise, worth about 196,000 extra FX futures and 1.2 million extra equity futures, comparable to an entire Fed meeting (source: CME Group, 2025). The headline is the fireworks; the unemployment rate is what everyone is still talking about at dinner. In money terms, 10-year T-note futures averaged 2.78 million contracts on payrolls days in 2007–13 against 2.07 million normally, roughly $278bn of face value against $207bn (derived). The modern first-minute spike is smaller than the legend: about $6.0bn of equity-futures notional and $2.5bn to $2.9bn of FX at most (derived upper bounds).
Where payrolls sits among record days
Records are usually set by crises and Fed shocks. Payrolls borrows one now and then and gives it back quickly.
| Date | What happened | Volume | Source |
|---|---|---|---|
| 4 Dec 2009 (NFP) | November payrolls −11k vs about −120k expected | Record CME FX futures day: 1.4m contracts, $184.9bn notional | FX Week |
| Jan 2007–May 2013 | Average NFP day vs average day | 10-yr T-note futures +34%; E-mini S&P +15%; Eurodollar +4% | CME Group (2013) |
| 28 May 2013 (Tue) | Taper fears after a US holiday | Record Treasury futures day: 10,476,906 contracts | CME Group |
| 2 Aug 2024 (NFP) → 5 Aug | July payrolls 114k; carry unwind the following Monday | Aug 2024 Treasury ADV record 11.5m; BrokerTec $249bn on 5 Aug | CME Group |
| 9 Oct 2025 (Thu) | Gold and silver frenzy, no payrolls involved | Record CME metals day: 2,148,990 contracts | CME Group |
| Sep 2026 | Ordinary background for scale | ≈1.8m E-mini S&P contracts a day; $115bn a day on BrokerTec | CME Group |
So payrolls owns the most frantic minute in the trading calendar and then, within the hour, quietly hands the stage back. It is a sprint, not a marathon, and the crowd is usually at lunch before the runners have caught their breath. Which leaves the question every reader of a broker’s blog is really asking: so what is the plan for Friday?
How to trade a number you can’t quite trust
The headline is a noisy draft. The reaction is a very predictable human event.
Three facts shape every sensible plan. Spreads at the release can widen several-fold; practitioner write-ups put it at 3 to 6 times. A surprise has to exceed about 83,000, one standard error, before it is distinguishable from sampling noise; anything smaller is a coin toss dressed as news. And the regime decides the direction: in an inflation scare, good news is bad news for stocks (February 2018, February 2023); in a growth scare, bad news is bad news (August 2024). Drag the slider and watch the logic flip.
Trade planner
Rules of thumb built from the evidence above. Not a signal, not a promise, not a substitute for a stop.
From that evidence come seven plays, ranked by how much sleep they cost.
Seven plays for payrolls day
| Play | What you do | Instruments | Risk and invalidation |
|---|---|---|---|
| 1. The deliberate absence | Flat or sharply reduced size 15 minutes either side of 8:30. The only play with a positive expectancy for most retail accounts, and the only one you can do in bed. | Everything | Cost: missed moves. Log what you skipped for 3 months. |
| 2. The second move | Let the first 1–5 minutes (5–12× normal volume) exhaust themselves. Trade 8:35–9:00 once revisions, unemployment and wages are digested. | XAUUSD, US500, USDJPY | Stop beyond the first-spike extreme. Invalid if price re-enters the 8:30 range. |
| 3. The revision trade | Read the prior two months first; a −100k revision can matter more than the new print. Join the Revision Readers. Bring snacks. | US10Y proxy, USDJPY | Invalid when revisions turn positive for two months running. |
| 4. The wages and unemployment override | When wages or the jobless rate disagree with the headline, follow them; they drive whole-day volume. | US10Y/2Y, EURUSD | Invalid if CPI later that month contradicts. |
| 5. The three-month trend | Ignore single prints; act only when the 3-month average and unemployment agree for two releases. | Index CFDs, gold | Review monthly. Cheapest play; looks least like trading. |
| 6. Fade the overreaction | When a beat is under ~83k but the first move is large, fade part of it: statistically, it was a coin flip with a press release. | USDJPY, XAUUSD | Highest risk. Small size, hard stop; skip in trends. |
| 7. The structural hedge | Size anything held into the print as if the headline were ±136k wrong, because it might be. | Portfolio | A risk rule, not an edge. |
Freelancers, machines, basic income and markets that never sleep
A survey designed for 1940 meets an economy that keeps changing the definition of “a job.”
What counts as a job. Payrolls counts positions on employer payrolls. The self-employed and independent contractors are outside it by design, which made perfect sense in 1940 and makes slightly less sense in an age of side hustles. If you freelance for six clients, drive for an app or run a one-person company with a stable of AI agents doing the work of fifty, the survey has no idea you exist. A whole economy of solo founders could be booming while the headline shrugs.
The growing blind spot (% of employed)
Source: BLS Contingent Worker Supplement (May 2017; July 2023, published Nov 2024). App-based platform work was surveyed in 2023; the results are, fittingly, still pending.
The machines. The fear is old. The Luddites broke looms in 1811; Keynes predicted a 15-hour working week by 2030, and everyone remains, regrettably, on email. Aggregate evidence of AI job losses is still thin: the August report showed information-sector jobs down 23,000, with a 12-month average loss of 8,000, a whisper rather than a roar. But tariffs, tighter immigration, an energy shock and an ageing workforce have all lowered the hiring pace needed to keep unemployment steady. With unemployment between 4.1% and 4.3% while payrolls averaged about 68,000 a month this year, a breakeven of roughly 50,000 to 80,000 is the logical inference (derived). A 29,000 print does not mean what it meant in 2019, though it will still be traded as if it does.
Income without a job. If work and income start to come apart, the basic-income debate returns. Alaska has paid an annual dividend since 1982; Finland tested a basic income on 2,000 unemployed people in 2017–18; OpenResearch’s US trial paid $1,000 a month and found modestly lower working hours. A true UBI would change the Fed’s world: if income no longer depends on employment, the jobless rate stops being the master measure of welfare, and payrolls loses some of its policy weight, if not its ability to ruin a Friday morning.
The market never closes. For decades the jobs report had the courtesy to arrive just as New York was waking up. That arrangement is ending. CME has traded crypto futures and options around the clock since 29 May 2026 (source: Markets Media), and Nasdaq and NYSE Arca plan to trade US stocks overnight on weeknights from 6 December 2026, after the SEC approved Nasdaq’s proposal in April (source: Jones Day).
A New York weekday, from December 2026
Planned US stock sessions (Jones Day); crypto futures run 24/7 (CME). The jobs report will land at 8:30 into a market that has been up all night.
Two effects seem likely. The sixty-second stampede may spread out, as more of the positioning happens before the bell; and overnight liquidity is thin, with most volume clustered in the first hour of the session (source: Jones Day, citing an SEC roundtable), so a surprise at the wrong moment could move prices further, not less. The verdict: payrolls is not going anywhere. The Fed’s mandate keeps it centre stage and nothing else commands the same shared attention. But alternative data eats a little more of its lunch every year, the unemployment rate already drives more whole-day volume than the headline, and a 24-hour market will take some of the theatre out of a single minute. Expect it to become what famous old benchmarks become: still quoted, still respected, still capable of ruining a weekend, just a little less often.
Three roads, quarter by quarter
Scenarios, not forecasts. Please apply the usual ±136,000 of humility.
The set-up: the Fed, chaired by Kevin Warsh, hiked 25bp to 3.75–4.00% on 16 September (12–0), then held there on 28 October by 10–2, with Lisa Cook and Beth Hammack voting for another hike; futures price roughly an 80% chance of a December hike (sources: Federal Reserve, FXStreet). September PCE inflation was 3.6%, core 3.1% (source: BEA, 29 Oct). The 10-year yield, which touched a 2002-level high near 5.3% in early October, has since slipped to about 4.9% after a late-October tech sell-off and the 3 November midterms, in which Democrats took both chambers. Gold had its worst month since 2008 in October, bottoming near $3,870, before rebounding above $4,000 on 4 November. Payrolls average 68,000 a month in 2026. The paths below show average monthly payrolls per quarter, with asset ranges off dated anchors (Fed funds 3.75–4.00%; 10-year ≈ 4.90%, S&P 500 7,689 and gold ≈ $4,040, all 4 Nov close).
Payrolls by quarter (k/month) and asset ranges by end-2028
Each road has its signposts. Stagflation: core PCE stays above 3%, payrolls hover below 60,000, the Fed hikes once more and holds. AI shock: continuing claims climb, graduate hiring falls, unemployment pushes above 4.6% while productivity rises, and the Fed pivots to cuts in 2027. Soft landing: energy prices ease, inflation drifts to about 3%, payrolls settle near 80,000 to 100,000. Each fails if its signposts stop lining up for two releases in a row. Whichever road arrives, the jobs report will be there to announce it, approximately, and to correct itself later.
How to live with a number that keeps changing its mind
Respect the reaction. Question the reading. Read the revisions.
A survey built because a country once could not count its own jobless now steers the price of money for the planet. It is compiled from six in ten replies, completed by a model, reshaped by seasonal arithmetic and revised for a year, and it is still the most powerful number in finance. It earned that power not by being precise but by being shared. It belongs with finance’s other glorious oddities: a gold price once set by a handful of bankers on a phone call, a Dow still calculated by share price, a global oil benchmark named after a goose. Watch it closely, trade it carefully, and allow yourself a small smile when the revisions come in.
Checklist for the next release
Next dates: October payrolls 6 Nov (consensus +65k, unemployment 4.2%) · CPI 10 Nov · PCE 25 Nov · overnight US stocks planned 6 Dec · Fed 9 Dec (sources: BLS, Reuters, BEA, Nasdaq, Fed).
The Silk Road merchants had it right: the cargo was never as valuable as the rumour that arrived ahead of it, and the clever ones carried a little less of both than they were tempted to. Every month the caravan assembles, the rumour arrives, the number is revised, and the market moves on to the next one. The only real mistake is forgetting which part is the cargo.
Quick answers, then the full ledger
When is the next report?
October payrolls are due on Friday 6 November 2026 at 8:30 a.m. New York time. US clocks went back on 1 November, so that is 13:30 GMT and 5:30 p.m. in the UAE, an hour later than in the summer (source: BLS). Economists polled by Reuters expect +65,000 jobs and unemployment unchanged at 4.2%; ADP’s private count on 4 November showed +86,000. The revisions to August and September will arrive at the same time, unannounced as usual.
How big does a surprise need to be to matter?
About 83,000 jobs, one standard error, before it is distinguishable from sampling noise (derived from the BLS ±136,000 interval). Smaller surprises still move prices; they are just coin tosses with a press release.
Which part of the report should I read first?
The revisions to the previous two months, then the unemployment rate and average hourly earnings, then the headline. Over a whole day, the unemployment-rate surprise drives far more futures volume than the headline (source: CME Group, 2025).
Which markets move the most?
Short-dated Treasury yields (about 2.35× a normal day), then the 10-year (about 2×), then equities (1.3–1.7×). Gold and the major dollar pairs typically move about a quarter of one percent in the first fifteen minutes (sources: macroornoise.com, Russell Rhoads, FXStreet).
Is the number unreliable on purpose?
No. The BLS publishes its margins of error, revision history and methods in full. The first estimate is fast by design and rests on partial responses; accuracy improves with each revision. The surprising part is not the uncertainty, but how little of it the market prices in on the day.
The data ledger
Every figure in the article, with sample, window and source. Tap to open.
A. How the number is made
| Item | Value | Source |
|---|---|---|
| Sample | ≈121,000 businesses and agencies; ≈631,000 worksites; ≈⅓ of payroll jobs | BLS |
| Reference period | Pay period including the 12th | CRS |
| Collection rate 1st / 2nd / 3rd estimate | 60.4% / 89% / 90.9% (2024); 10–16 days to first estimate | CRS |
| Replies at first print | ≈73,000 employers (121,000 × 60.4%, derived) | Derived |
| Establishment survey response rate | ≈58% pre-2020 → 43% (2024) | CRS |
| Household survey response rate | ≈90% (2013); 82% (Feb 2020); below 70% (2024); −5 points Sep–Nov 2025 | Federal Reserve Bank of Atlanta |
| Household survey size | ≈60,000 households; unemployment-rate margin ±0.2pt | BLS |
| Birth-death 2026 (raw) | Jan −61k; Feb 90k; Mar −47k; Apr 391k; May 158k; Jun 8k; Jul 235k; Aug 74k; Sep −190k | BLS |
| Raw vs adjusted 2026 | Jan −2,630k → +160k; Jul −1,025k → −10k | BLS (derived comparison) |
| October 2025 | Household survey not collected (43-day shutdown); unemployment rate never published | Reuters via GV Wire |
B. Studies of the average market reaction
| Market | Measure | Sample | Result | Source |
|---|---|---|---|---|
| Gold | 15 min after release | 35 releases to Jan 2025 | +$7.83 weak; −$5.07 strong (≈+0.29% / −0.19%, derived at $2,700) | FXStreet |
| Gold | 15 min after release | Releases to Jul 2021 | +$2.75 weak; +$0.44 strong (≈+0.16% / +0.03%, derived at $1,760) | FXStreet |
| EUR/USD · GBP/USD | 15 min after release | 13 releases to Jul 2021 | +19.4 / +3.5 pips · +19.3 / +9 pips (weak / strong) | FXStreet |
| 10-yr · 2-yr Treasury | Absolute daily yield change | 36 releases, 2023–25 | 8.5bp vs 4.3bp (1.98×) · 2.35× | macroornoise.com |
| Broad dollar | Absolute daily change | 2023–25 | 1.38×; not statistically robust | macroornoise.com |
| S&P · Nasdaq-100 · Russell 2000 · Euro Stoxx 50 | Close-to-close | 11 NFP days, 2023 | 1.05 vs 0.65% · 1.28 vs 0.91% · 1.70 vs 1.01% · 0.87 vs 0.65% | Russell Rhoads |
| E-mini · T-note · Eurodollar futures | High-low range ratio; close-to-close ratio | Jan 2007–May 2013 | 1.06×, 0.96× · 1.33×, 1.33× · 1.38×, 1.43× | CME Group (2013) |
| Forecast error | Average absolute surprise | Jan 2007–May 2013 | 51.7k; NFP the only indicator significant for volume, range and direction | CME Group (2013) |
C. The hall of fame in full
D. Volume
| Window | Market | Baseline | NFP effect | Source |
|---|---|---|---|---|
| First minute | Interest-rate futures | 20,663 | +174,173 per 1σ surprise (≈9.4×) | CME (Jul 2025) |
| First minute | FX futures | 1,704 | +18,132 (≈11.6×) | CME (Aug 2025) |
| First minute | Equity-index futures | 3,395 | +14,810 (≈5.4×) | CME (Aug 2025) |
| First ten minutes | FX · equity futures | 11,030 · 28,671 | +18,466 to +49,638 · +10,880 to +66,502 (by component) | CME (Aug 2025) |
| Whole day | FX futures | 770,656 | Headline +38,505 (p 0.86); unemployment +195,939 (p 0.048); FOMC +215,748 | CME (Aug 2025) |
| Whole day | Equity-index futures | 5,266,740 | Headline +319,566 (p 0.74); unemployment +1,197,086 (p 0.005); FOMC +990,768 | CME (Aug 2025) |
| Daily, 2007–13 | T-note · E-mini · Eurodollar | 2,067,652 · 1,124,528 · 2,129,108 | 2,779,526 (+34%) · 1,294,633 (+15%) · 2,216,011 (+4%) | CME (2013) |
| 4 Dec 2009 | CME FX futures | — | Record 1.4m contracts, $184.9bn | FX Week |
E. Revisions
| Measure | Value | Source |
|---|---|---|
| 90% interval, monthly change | ±136,000 (standard error ≈83,000, derived) | BLS |
| Monthly revisions since 2003 | Avg 51k either way; largest −672k (Mar 2020), +437k (Nov 2021) | CRS |
| May–June 2025 | −258k, largest two-month cut since at least 1978 outside 2020 | Richmond Fed |
| 26 months, Jul 2023–Sep 2025 | Mean first ≈189k; settled ≈101k; 23 revised down; |revision| ≈93k; |surprise| ≈71k; 9 sign flips | forexfundamentals; BLS (derived) |
| Benchmark, March 2025 | −898k (−0.6%), largest since 2009; typical ±0.2% | First Trust, citing BLS |
| Calendar years, reported → settled | 2022: 4,619k → 4,526k; 2023: 3,140k → 2,515k; 2024: 2,589k → 1,459k; 2025: 1,208k → 116k | Ritholtz; Wolf Street; BLS |
F. The changing market
| Item | Value | Source |
|---|---|---|
| CME crypto futures and options | 24/7 from 29 May 2026; ≈7,200 contracts, ≈$50m first weekend | Markets Media |
| US stocks overnight | SEC approved Nasdaq 10 Apr 2026; 21:00–04:00 ET weeknights planned from 6 Dec 2026 | Jones Day |
| Independent contractors · contingent | 7.4% · 4.3% of employed (2023), from 6.9% · 3.8% (2017) | BLS |
For informational and educational purposes only. Not financial advice. Leveraged products such as CFDs and FX can move against you quickly and losses can exceed expectations; trade only with money you can afford to lose. Sources: BLS CES series (via useconomicdata.com snapshot, 22 Oct 2026), technical note and birth-death tables; BLS Contingent and Alternative Employment Arrangements (Nov 2024); BLS “Why are there revisions to jobs numbers?” (2013); CRS IF13084 (Aug 2025); Federal Reserve Banks of Richmond (Aug 2025) and Atlanta (Apr 2026); First Trust (Feb 2026); Ritholtz and Wolf Street (Feb 2026); forexfundamentals NFP table; FXStreet NFP studies (2021, 2025); macroornoise.com (2023–25); Russell Rhoads (2024); CME Group research (2013, 2025), press releases, newsletters and videos (2013–2026); FX Week (Dec 2009); Markets Media (Jun 2026); Jones Day (Sep 2026); Reuters via GV Wire (Nov 2025); Christian Science Monitor (1986); Bank of England Quarterly Bulletin (1996); Motley Fool (1996); Ticker.com (2009, 2011); Reuters via Kitco and Investing.com; UPI (2010); NPR and The Fiscal Times (2018); CNBC, Al Jazeera, Business Standard (2020); AP via ABC News (2024); Barchart and RTTNews via Nasdaq (2025); Charles Schwab (2025); Anadolu Agency (2023); StarTrader (2023); CoinCentral and Eurasia Business News (Oct 2026); CNBC, Reuters, EBC and Bernama (Aug–Oct 2026); market update to 5 Nov 2026: Federal Reserve and Admiral Markets (28 Oct FOMC), BEA (September PCE), Reuters (ADP, October consensus), CNBC (4 Nov close), FXStreet and Investing.com (gold, 10-year yield, Fed odds), U.S. Treasury par yields (2-year), Nasdaq (overnight session). Consensus figures vary by survey. Historical background is standard published history.
↑ Back to the top