Wall Street Tests Channel Floors at 7,321, FTSE and DAX Break Support and Hang Seng Slides as Markets Brace for the Fed Minutes at 19:00 GMT | Technical Analysis | 18 Nov 2026
LIVE Indices | Wednesday 18 November 2026 | Updated 17:25 GMT, prices as of 17:18 GMT, Europe and Hong Kong closed, US session live, FOMC minutes at 19:00 GMT still to come
Wall Street Tests Channel Floors at 7,321, FTSE and DAX Break Support and Hang Seng Slides as Markets Brace for the Fed Minutes at 19:00 GMT
Market Overview
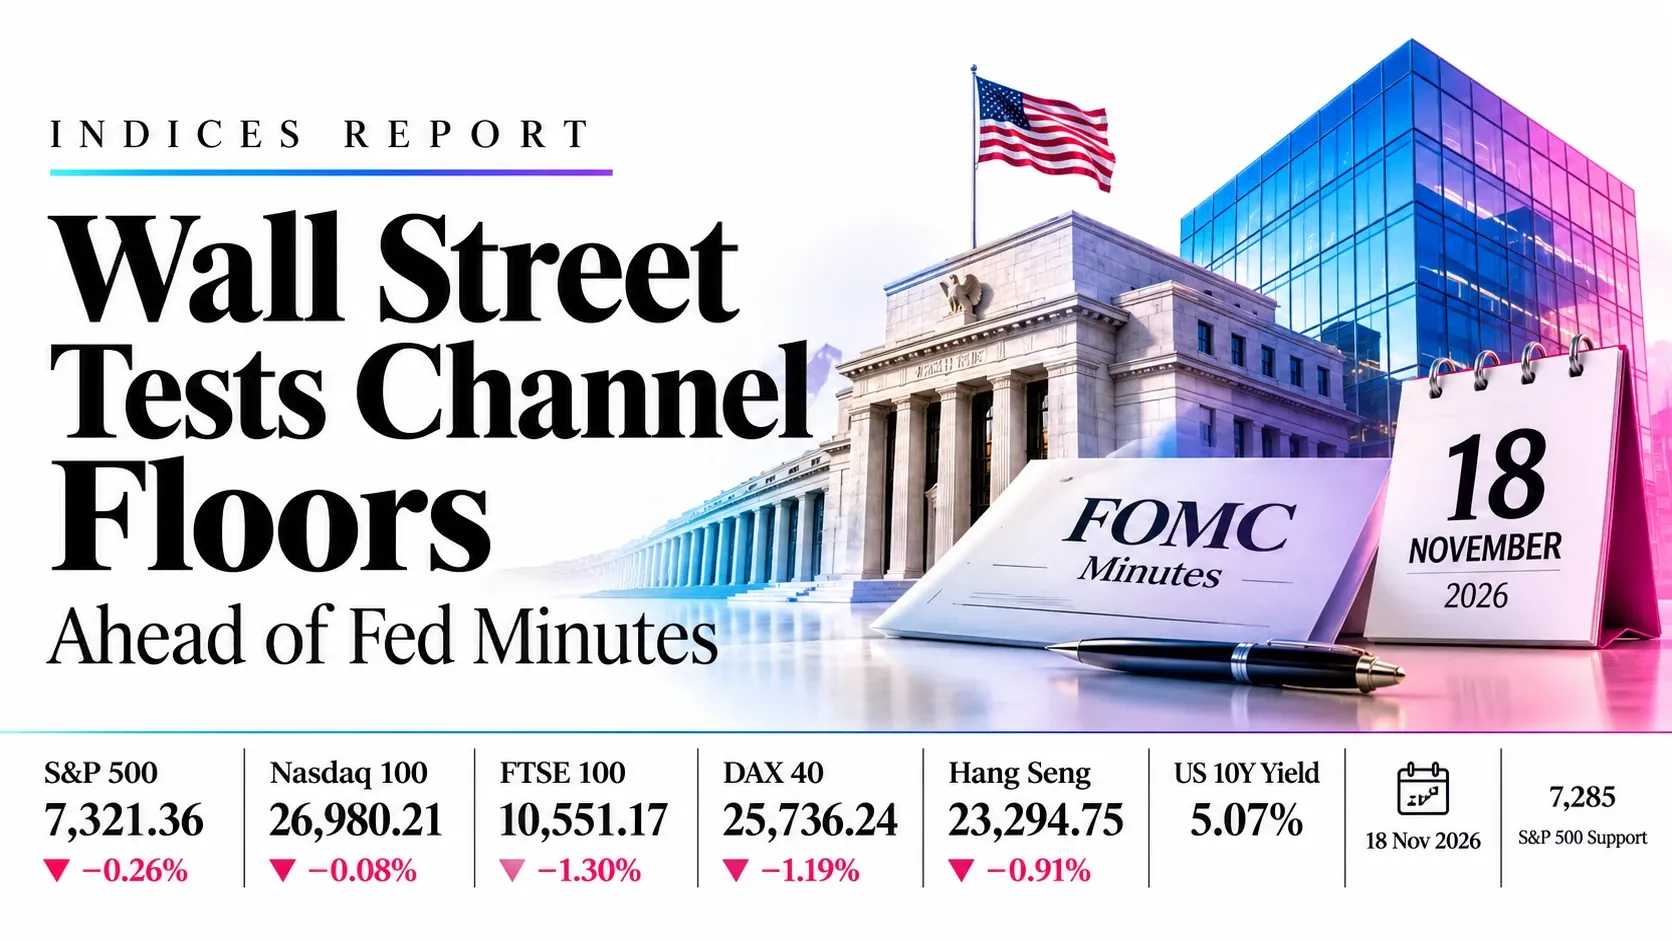
Global equities are under pressure, with every index below its short-term averages ahead of the Fed. The S&P 500 is at 7,321.36 (−0.26%) on the floor of a falling channel after a fourth straight loss, and the Nasdaq 100 is at 26,980.21 (−0.08%) after its Nvidia pop faded. The FTSE 100 closed at 10,551.17 (−1.30%) on its rising trendline, the DAX 40 at 25,736.24 (−1.19%) just under its channel floor and the Hang Seng at 23,294.75 (−0.91%). The US 10-year yield is near 5.07% and a 25bp December hike is about 95% priced.
The Fed minutes at 19:00 GMT are the shock risk. Minutes that back a 50bp move, as Waller has urged, could break 7,285 in the S&P 500 and the FTSE trendline near 10,500, while a split over pace could spark bounces from RSI readings of 36 to 46. We sell bounces in the S&P 500, FTSE 100, DAX 40 and Hang Seng, and buy the Nasdaq 100 only on a pullback with low conviction. Ideas lapse at the next cash close, or 21:00 GMT for the US.
Key highlights
- S&P 500: Price 7,321.36 (-0.26%); 7,400 caps and 7,285 supports.
- Nasdaq 100: Price 26,980.21 (-0.08%); 27,500 caps and 26,850 supports.
- FTSE 100: Price 10,551.17 (-1.30%); 10,690 caps and 10,500 supports.
- DAX 40: Price 25,736.24 (-1.19%); 26,050 caps and 25,400 supports.
- Hang Seng: Price 23,294.75 (-0.91%); 23,660 caps and 23,000 supports.
What’s Moving Indices Today
Wall Street tests channel floors as a December Fed hike is almost fully priced and the 10-year yield holds near 5.07%
The S&P 500 fell 1.03% to 7,340.53 on Tuesday, its fourth straight loss and lowest close since 29 July, and the Dow lost 1.64%. Futures bounced on Nvidia but the cash market has faded. Governor Waller wants a 50bp hike in December unless the Fed signals faster tightening, and St. Louis Fed’s Musalem sees up to four more hikes. The funds rate is 3.75%–4.00% and CME FedWatch shows about a 95% chance of 25bp on 9 December.
Source: CNBC, Yahoo Finance, Benzinga, Admiral Markets, 18 Nov 2026
Nvidia beats and raises, but the chip bounce cools while the CEO exit and Anthropic’s IPO keep AI trades jumpy
Nvidia’s third-quarter profit and revenue beat estimates and it raised its outlook for the year to January 2028, first results since Jensen Huang’s departure. Shares rose in pre-market and trimmed gains after the open. The Nasdaq Composite touched its lowest level since April on Tuesday. Anthropic, the maker of Claude, is expected to price its Nasdaq IPO today and start trading on Thursday under ANT.
Source: CNBC TV18, Yahoo Finance, Investinglive, 18 Nov 2026
FTSE 100 closes at 10,551 after UK inflation rises to 3.6% and miners slide
CPI rose to 3.6% in October from 3.5%, core stayed at 2.8% and services at 3.7%, keeping a December Bank of England hike on the table. Mining stocks fell with copper. The FTSE had already dropped 1.76% to 10,689.87 on Tuesday as the STOXX 600 had its worst day since March.
Source: Proactive Investors, AdvFN, BigGo Finance, 18 Nov 2026
DAX drops 1.19% to 25,736 as AI-spending worries and yields weigh on Europe
Europe opened flat on the Nvidia lift to chips, then sold off through the session. Tuesday’s 2.08% fall had hit tech hardest, and the STOXX 600 is more than 1.7% off its record close. German yields and the US 10-year above 5% keep growth shares under pressure.
Source: AdvFN, Newsquawk, Longbridge, 18 Nov 2026
Hang Seng falls 0.91% to 23,294.75 as JD.com weakens, with US chip curbs and Tencent results in view
Tech, healthcare and non-ferrous metals fell, with the Hang Seng Tech Index down 0.58% to 3,736.33 on turnover near HK$177 billion. JD.com and JD Health dropped after results and Alibaba and Baidu fell on Tuesday after tighter US AI-chip limits. Lenovo and chip names gained. The Shanghai Composite rose 0.09%.
Source: RTHK, Xinhua, Bastille Post, Ad-hoc-news, 18 Nov 2026
Key Drivers for the Rest of Today
Six things that set direction for the S&P 500, Nasdaq 100, FTSE 100, DAX 40 and Hang Seng.
- UK CPI (released)
- 07:00
- Wed 18 Nov, 07:00 GMT
- October inflation 3.6%; December BoE hike bets stay alive
- US stock open
- 14:30
- Wed 18 Nov, 14:30 GMT
- Chip bounce after Nvidia faded; Dow weighed by UnitedHealth
- FOMC minutes
- 19:00
- Wed 18 Nov, 19:00 GMT
- October meeting; December hike about 95% priced, Waller backs 50bp
- Anthropic IPO pricing
- Tonight
- Wed 18 Nov, time unconfirmed
- Pricing expected today, Nasdaq debut Thursday as ANT; sets AI tone
- Asia open and APEC
- 01:30
- Thu 19 Nov, 01:30 GMT
- Hang Seng reopens; APEC summit in Shenzhen runs 18–19 Nov
- Setup expiry
- 21:00
- Wed 18 Nov, 21:00 GMT
- US ideas lapse; FTSE and DAX at 16:30 GMT and Hang Seng at 08:00 GMT Thursday
Swipe the strip to see every driver.
Trade Setups for Today
Ranked in the order S&P 500, Nasdaq 100, FTSE 100, DAX 40 and Hang Seng, validated against the 17:18 GMT live prices.
| Instrument | Direction | Entry | Stop | Target 1 | Target 2 | Reward:risk | Conviction |
|---|---|---|---|---|---|---|---|
| S&P 500 | Short | 7,400 | 7,480 | 7,320 | 7,250 | 1.0 / 1.9 | Medium |
| Nasdaq 100 | Long | 26,500 | 26,100 | 27,000 | 27,500 | 1.2 / 2.5 | Low |
| FTSE 100 | Short | 10,690 | 10,790 | 10,550 | 10,450 | 1.4 / 2.4 | Medium |
| DAX 40 | Short | 26,050 | 26,350 | 25,600 | 25,400 | 1.5 / 2.2 | Medium |
| Hang Seng | Short | 23,660 | 23,950 | 23,300 | 23,000 | 1.2 / 2.3 | Medium |
Reward:risk is the distance from entry to each target divided by the distance from entry to the stop. All entries are limit orders at the levels shown, not market prices. Four setups sell bounces and one buys a pullback; the short setups share the same Fed and AI theme, so they are not independent, and the Nasdaq 100 long would work against the S&P 500 short if both fill. Pending orders lapse at 21:00 GMT today for the US indices, at 16:30 GMT on Thursday for the FTSE 100 and DAX 40 and at 08:00 GMT on Thursday for the Hang Seng.
Risk Scenario Analysis
The tone of the 19:00 GMT Fed minutes and the 10-year yield are the swing factors for the rest of today.
If the minutes show broad support for a 50bp move, the channel floors give way and Europe and Asia follow.
A 10-year yield above 5% and a 50bp debate keep sellers in control. The S&P 500 loses 7,285, the FTSE gives up its trendline, and the DAX and Hang Seng extend lower on Thursday.
- S&P 5007,285, then 7,200
- Nasdaq 10026,850, then 26,150
- FTSE 10010,500, then 10,400
- DAX 4025,400, then 24,950
- Hang Seng23,000, then 22,750
If the minutes show a debate over the pace of hikes, oversold charts bounce and sellers wait at resistance.
Short covering lifts every index, but all five charts still have averages overhead, so bounces stall at the levels below.
- S&P 5007,400, then 7,560
- Nasdaq 10027,500, then 28,200
- FTSE 10010,690, then 10,750
- DAX 4026,050, then 26,450
- Hang Seng23,660, then 24,170
S&P 500 (SPX) | TradingView chart, cash index, US session live
S&P 500 Analysis: Index Sits on the Channel Floor at 7,321 After Four Straight Losses, With 7,400 the Level to Sell a Bounce
7,321.36 −19.17 (-0.26%) at 17:18 GMT Previous close 7,340.53 | Open 7,355.69 | Day range 7,285.76–7,367.68 | Fourth straight loss on Tuesday | Lowest close since 29 July | 10-year yield about 5.07% | FOMC minutes 19:00 GMT
Outlook: Bias is lower on bounces with medium conviction while 7,480 caps. The index has fallen out of its September high and is testing the lower line of a falling channel, with RSI deeply weak. The idea sells a bounce to 7,400, not the low.

Key levels
- Support 2
- 7,200
- Support 1
- 7,285
- Resistance 1
- 7,400
- Resistance 2
- 7,560
- Price (7,321.36) is under the 7,559.16, 7,625.24 and 7,648.46 averages. Tuesday’s 1.03% fall to 7,340.53 was a fourth straight loss and the lowest close since 29 July, and 17 of every 20 stocks fell. A chip bounce after Nvidia’s results has faded and the Dow is down about 0.9%. Main catalysts: FOMC minutes at 19:00 GMT and Anthropic’s IPO pricing.
- RSI 36.48 under its 41.88 average: weak but not yet oversold. A close under 7,285 opens 7,200; a rebound through 7,400 would test the 7,560 average; a 4-hour close above 7,480 would end the bearish view.
Setup: Short at 7,400, stop 7,480, targets 7,320, 7,250, 7,150. Reward:risk 1.0 / 1.9 / 3.1, medium conviction. Cancel if a 4-hour close above 7,480. Cancel if unfilled by 21:00 GMT today.
Nasdaq 100 (NDX) | TradingView chart, cash index, US session live
Nasdaq 100 Analysis: Nvidia Pop Fades and Index Holds 26,980 in a Falling Channel, With a Dip Buy Only Near 26,500
26,980.21 −21.57 (-0.08%) at 17:18 GMT Previous close 27,001.78 | Open 27,177.41 | Day range 26,848.92–27,231.24 | Futures were up about 1.2% pre-market, now flat | Nvidia beat and raised | Anthropic IPO pricing | FOMC minutes 19:00 GMT
Outlook: Bias is a dip buy with low conviction while 26,100 holds. The index is in a falling channel from October and the Nvidia-led chip rally has faded since the open. The idea buys a pullback to 26,500, not the current price.

Key levels
- Support 2
- 26,150
- Support 1
- 26,850
- Resistance 1
- 27,500
- Resistance 2
- 28,200
- Price (26,980.21) is under the 28,205.17, 29,294.94 and 29,360.06 averages. Nvidia reported better-than-expected results and raised its outlook, with shares up almost 5% after hours, but gains cooled after the open as software and large-cap tech sold. Chipmakers outperformed. Main catalysts: FOMC minutes at 19:00 GMT and the planned Anthropic listing on Nasdaq.
- RSI 36.20 under its 37.41 average: weak, with no bullish divergence yet. A daily close above 27,500 would test the channel top near 28,200; a close under 26,850 opens 26,150; a 4-hour close under 26,100 cancels the idea.
Setup: Long at 26,500, stop 26,100, targets 27,000, 27,500, 28,200. Reward:risk 1.2 / 2.5 / 4.2, low conviction. Cancel if a 4-hour close below 26,100. Cancel if unfilled by 21:00 GMT today.
FTSE 100 (UKX) | TradingView chart, cash index, London session closed
FTSE 100 Analysis: Index Closes at 10,551 on the Rising Trendline After a Sell-Off, With 10,690 the Level to Sell a Bounce
10,551.17 −138.70 (-1.30%) at the close, 17:18 GMT Previous close 10,689.87 | Open 10,690.55 | Day range 10,537.47–10,692.25 | UK CPI 3.6% in October | Mining shares weak | Bank of England hike expected in December | Closed 16:30 GMT
Outlook: Bias is lower on bounces with medium conviction while 10,790 caps. London has fallen through its three averages and is resting on the rising line from March inside a wedge. The idea sells a retest of the broken averages at 10,690.

Key levels
- Support 2
- 10,400
- Support 1
- 10,500
- Resistance 1
- 10,690
- Resistance 2
- 10,750
- Price (10,551.17) is under the 10,691.60, 10,713.73 and 10,747.97 averages after Tuesday’s 1.76% fall to 10,689.87 and a further drop today. UK inflation rose to 3.6% in October from 3.5%, core stayed at 2.8% and a December Bank of England hike is expected, while miners fell on weak copper. Main catalysts: FOMC minutes at 19:00 GMT and Thursday’s open.
- RSI 40.30 under its 52.72 average: weakening but not oversold, so there is room to fall. A close under the 10,500 trendline opens 10,400 and the October low near 10,350; a close back above 10,750 would end the bearish view.
Setup: Short at 10,690, stop 10,790, targets 10,550, 10,450, 10,350. Reward:risk 1.4 / 2.4 / 3.4, medium conviction. Cancel if a 4-hour close above 10,790. Cancel if unfilled by 16:30 GMT on Thursday 19 Nov.
DAX 40 (DAX) | TradingView chart, Xetra cash index, session closed
DAX 40 Analysis: Index Closes at 25,736 Just Under Its Rising Channel Floor, With 26,050 the Level to Sell the Retest
25,736.24 −309.13 (-1.19%) at the close, 17:18 GMT Previous close 26,045.37 | Open 26,082.63 | Day range 25,723.67–26,139.16 | Prior close 26,045 after −2.08% Tuesday | AI-spending worries | Rate-hike bets | Closed 16:30 GMT
Outlook: Bias is lower on bounces with medium conviction while 26,350 caps. The DAX has slipped under the floor of the rising channel from October after failing near 27,000. The idea sells a retest of the broken floor at 26,050.

Key levels
- Support 2
- 24,950
- Support 1
- 25,400
- Resistance 1
- 26,050
- Resistance 2
- 26,450
- Price (25,736.24) fell 1.19% to a low of 25,723.67, a second heavy loss after Tuesday’s 2.08% drop. European tech took the biggest hit on Tuesday and Nvidia’s results only steadied chips, while US yields above 5% and a near-certain December Fed hike keep growth stocks under pressure. Main catalysts: FOMC minutes at 19:00 GMT and Thursday’s open.
- RSI 45.98 under its 58.56 average: turning down from neutral, not oversold. A close under 25,400 opens 24,950 and the October low; a daily close back inside the channel above 26,050 would test 26,450; a 4-hour close above 26,350 cancels the idea.
Setup: Short at 26,050, stop 26,350, targets 25,600, 25,400, 24,950. Reward:risk 1.5 / 2.2 / 3.7, medium conviction. Cancel if a 4-hour close above 26,350. Cancel if unfilled by 16:30 GMT on Thursday 19 Nov.
Hang Seng (HSI) | TradingView chart, cash index, Hong Kong session closed
Hang Seng Analysis: Index Slides 0.9% to 23,295 Inside a Falling Channel, With the 23,660 Average the Level to Sell a Bounce
23,294.75 −213.42 (-0.91%) at the close, 17:18 GMT Previous close 23,508.17 | Open 23,428.72 | Day range 23,208.13–23,436.97 | Hang Seng Tech −0.58% | Turnover about HK$177B | JD.com and Baidu earnings disappointments | APEC Shenzhen 18–19 Nov
Outlook: Bias is lower on bounces with medium conviction while 23,950 caps. The index has been in a falling channel since August and has rolled over from the 24,900 area. The idea sells a bounce to the 20-day average near 23,660.

Key levels
- Support 2
- 22,750
- Support 1
- 23,000
- Resistance 1
- 23,660
- Resistance 2
- 24,170
- Price (23,294.75) closed under the 23,663.58, 24,168.26 and 24,614.26 averages, a second straight loss. JD.com and JD Health fell after results, Tencent weakened ahead of its earnings, and tighter US limits on advanced AI chips hit Alibaba and Baidu on Tuesday. Lenovo and chip names rose. Main catalysts: APEC in Shenzhen, FOMC minutes at 19:00 GMT and Thursday’s open.
- RSI 40.14 under its 49.42 average: weak but not oversold. A close under 23,000 opens 22,750 and the 52-week low near 22,518; a daily close above 23,950 would end the bearish view.
Setup: Short at 23,660, stop 23,950, targets 23,300, 23,000, 22,750. Reward:risk 1.2 / 2.3 / 3.1, medium conviction. Cancel if a 4-hour close above 23,950. Cancel if unfilled by 08:00 GMT on Thursday 19 Nov.
Conclusion
A near-certain December Fed hike, a 10-year yield above 5%, AI-spending worries and a firm UK inflation print keep indices pinned near their lows, with the S&P 500 on its channel floor and the FTSE and DAX under support. We prefer selling bounces in the S&P 500, FTSE 100, DAX 40 and Hang Seng, and buying the Nasdaq 100 only on a pullback with low conviction. The Fed minutes at 19:00 GMT decide whether those levels hold.
Trade the S&P 500, Nasdaq 100, FTSE 100, DAX 40 and Hang Seng with Capital Street FX.
Frequently Asked Questions
What is the indices outlook for today?
The S&P 500 is near 7,321.36, the Nasdaq 100 near 26,980.21, the FTSE 100 closed at 10,551.17, the DAX 40 at 25,736.24 and the Hang Seng at 23,294.75. A near-certain December Fed hike and a 10-year yield above 5% keep sentiment weak, and the Fed minutes at 19:00 GMT are the main driver.
Which index trade ideas are live today?
Short the S&P 500 at 7,400, the FTSE 100 at 10,690, the DAX 40 at 26,050 and the Hang Seng at 23,660; long the Nasdaq 100 at 26,500. Each has a stop and three targets and lapses at the next cash close for FTSE, DAX and Hang Seng or 21:00 GMT for the US indices.
What time are the key events in GMT?
UK CPI was at 07:00 GMT, US stocks opened at 14:30 GMT and the FOMC minutes follow at 19:00 GMT. Anthropic’s IPO is expected to price today, with the time unconfirmed, and trading is due on Thursday 19 November. The Hang Seng reopens at 01:30 GMT on Thursday.
Why are stocks falling today?
A December Fed hike is about 95% priced, the 10-year yield is near 5.07%, Waller is pushing for 50bp, and the Nvidia chip bounce has faded. UK inflation of 3.6% and weak miners hit the FTSE, and JD.com and US chip curbs hit Hong Kong.
Is the Nasdaq 100 oversold?
Not yet. Its RSI is 36.20 under a 37.41 average, so it is weak but above the 30 oversold line, and price is still far under the 28,205 average. The idea therefore buys a pullback to 26,500 with low conviction.