S&P 500 Advances to 7,733 as Wall Street Rebounds, While Treasury Yields and AI Investment Risks Put Tech Stocks to the Test | Technical Analysis – Index Report | 20 Oct 2026
Indices Today | Tuesday 20 October 2026
S&P 500 Advances to 7,733 as Wall Street Rebounds, While Treasury Yields and AI Investment Risks Put Tech Stocks to the Test
Market Overview
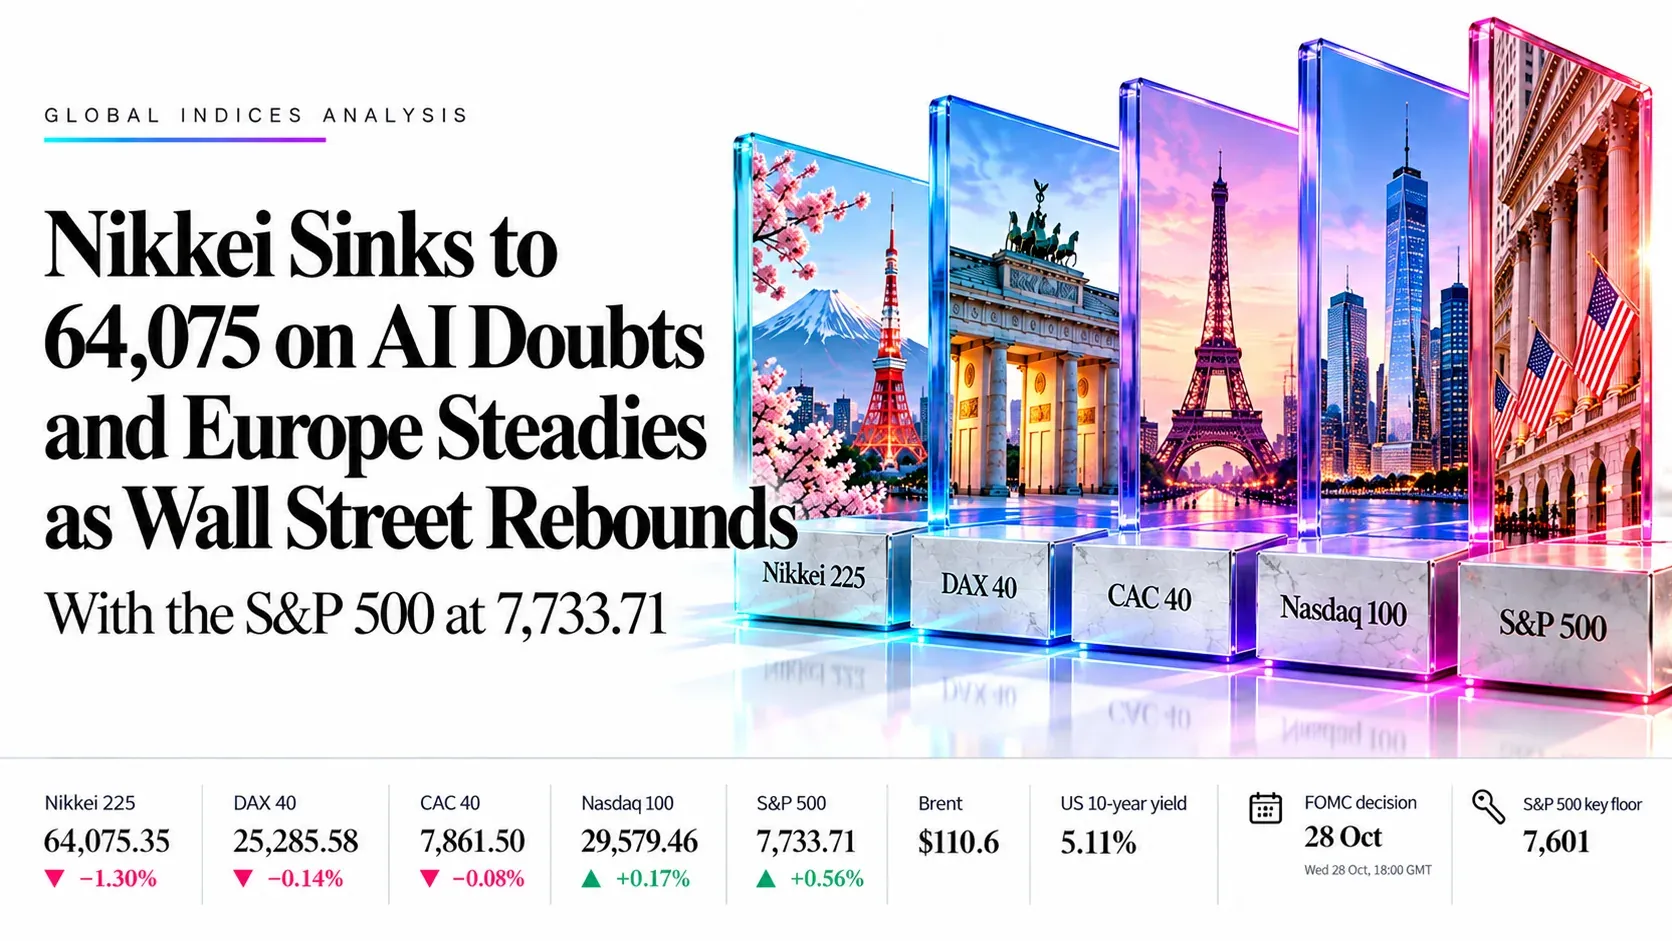
Indices split on Tuesday. At 14:35 GMT the S&P 500 was 7,733.71 (+0.56%) and the Nasdaq 100 29,579.46 (+0.17%), while the DAX 40 was 25,285.58 (−0.14%) and the CAC 40 7,861.50 (−0.08%), both recovered from lows about 1% under Monday’s close. The Nikkei 225 closed at 64,075.35 (−1.30%) after AI-funding worries hit SoftBank and Korean chipmakers. Brent is near $110 on Hormuz risk, the US 10-year yield is about 5.11%, and a December Fed hike is heavily priced in (Investing.com, CNBC, Reuters via syndication). The next catalysts are Netflix tonight, Meta and Tesla on Wednesday after the US close, flash PMIs on Friday and the Fed on 28 October. We read the session as a tech-sensitive market where Asia and France stay weak and the S&P 500 holds up.
Key highlights
- Nikkei 225: Price is 64,075.35 after falling back through a triangle floor; SoftBank −6% and the KOSPI −3.73% show AI-funding stress.
- DAX 40: Price is 25,285.58 inside a falling channel; the 25,430 average caps rallies and 25,050 is the first floor.
- CAC 40: Price is 7,861.50 under all three averages; French curfews and the 23 October Moody’s review keep it heavy.
- Nasdaq 100: Price is 29,579.46 under every average with RSI 42.02; Meta and Tesla earnings on Wednesday are the swing factor.
- S&P 500: Price is 7,733.71 level with its short average inside a rising channel; 7,601 is the key floor.
What’s Moving Indices Today
AI-funding doubts and a SoftBank slump drag the Nikkei to 64,075
The Nikkei closed down 1.30% as SoftBank fell about 6% and the KOSPI dropped 3.73%, even though US chip stocks rebounded on Monday. It is now more than 6,600 points under its 6 October close of 70,683.98, and the 15 October plunge of 4.90% followed a hotter-than-expected US inflation reading.
French unrest, curfews and a Moody’s review weigh on Europe
France imposed partial curfews in Paris and Nice after weekend unrest, the CAC 40 fell 1.1% on Monday and the French 10-year yield rose to about 4.84%. Moody’s reviews France on 23 October. The DAX and CAC both recovered from lows about 1% under Monday’s close, but UBS warns French fiscal risk could keep European debt volatile.
Brent near $110 on Hormuz mines and cable threats
Oil hit its highest since early May on reports of tankers striking mines in the Strait of Hormuz, and an Iranian Guards spokesman threatened undersea cables there. Brent traded near $110.6 earlier. Higher energy costs feed rate-hike fears, which hurt Japan and Europe more than the US.
Wall Street rebounds as industrials lead and chips stabilise
The S&P 500 rose 0.41% to 7,690.73 on Monday and the Nasdaq Composite rose 1.11% after its worst week since June (−4.48%), and chip stocks ended a nine-day losing streak. Today the Dow leads, with 3M up about 4.7% and Merck up about 2.8%, but Nasdaq futures were lower early on semiconductor and AI data-centre names.
US 10-year yield near 5.11% and a December Fed hike priced in
The 10-year yield is about 5.11%. The Fed is in its quiet period before the 27–28 October meeting, where a hold is expected and a December hike is heavily priced in. Hot inflation has put the AI trade under pressure because borrowing costs affect heavy AI spenders most.
Netflix tonight, then Meta and Tesla on Wednesday
Netflix reports after the US close today. Meta, Tesla, IBM, Lam Research and Texas Instruments follow after the close on Wednesday 21 October, and SAP also reports. Investors want proof that AI spending is paying off, so reactions can move the Nasdaq 100 sharply.
Key Drivers Ahead
Six events that set direction for the Nikkei, DAX, CAC, Nasdaq 100 and S&P 500. All times are GMT.
- Netflix earnings
- Q3
- Nasdaq 100 read on consumer tech
- Meta, Tesla earnings
- Q3
- AI spending and Nasdaq 100 direction
- Flash PMIs
- Oct
- Eurozone, UK and US; Moody’s reviews France
- FOMC decision
- 28 Oct
- Hold expected; December hike priced in
- ECB and BoE
- 29 Oct
- Rate decisions; DAX and CAC reaction
- BoJ decision
- 30 Oct
- Nikkei and yen; France Q3 GDP also due
Swipe the strip to see every driver.
Trade Setups for Today
Ranked in index order and valid for today’s session. A 1-hour close beyond the stop cancels the idea.
| Instrument | Direction | Entry | Stop | Target 1 | Target 2 | Reward:risk | Conviction |
|---|---|---|---|---|---|---|---|
| Nikkei 225 | Short | 64,900.00 | 65,900.00 | 62,900.00 | 60,500.00 | 2.0 / 4.4 | Medium |
| DAX 40 | Short | 25,430.00 | 25,720.00 | 25,050.00 | 24,850.00 | 1.3 / 2.0 | Low |
| CAC 40 | Short | 7,910.00 | 8,020.00 | 7,700.00 | 7,500.00 | 1.9 / 3.7 | Medium |
| Nasdaq 100 | Short | 29,860.00 | 30,420.00 | 29,200.00 | 28,780.00 | 1.2 / 1.9 | Low |
| S&P 500 | Long | 7,700.00 | 7,610.00 | 7,820.00 | 7,950.00 | 1.3 / 2.8 | Medium |
Reward:risk is the distance from entry to each target divided by the distance from entry to the stop. Prices are read at about 14:35 GMT on 20 October from TradingView charts (the Nikkei is its Tokyo close); most entries sit away from the current price and need a pullback or a bounce to trigger. Levels are conditional technical references, not recommendations.
Risk Scenario Analysis
AI-funding worries, US yields and oil are the swing factors for Asia and Europe, while Meta and Tesla earnings set the tone for the US. The Fed on 28 October is the next big test.
AI selloff deepens: weak earnings, higher yields and oil
A weak Meta or Tesla report, a hot yield move or a Hormuz escalation would extend the tech selloff and hit growth-heavy indices first.
- Nikkei 22562,900, then 60,500
- DAX 4025,050, then 24,850
- CAC 407,700, then 7,500
- Nasdaq 10029,209, then 28,800
- S&P 5007,601, then 7,520
Earnings relief: AI spending reassures and oil cools
Strong results and easing oil would let indices recover toward their averages before sellers return.
- Nikkei 22564,916, then 66,320
- DAX 4025,430, then 25,678
- CAC 407,913, then 8,165
- Nasdaq 10029,863, then 30,419
- S&P 5007,820, then 8,000
Japan 225 | Nikkei 225, TVC feed
Nikkei 225 Analysis: Price Falls Back Through the Floor of a Triangle as AI Doubts Bite
64,075.35 −841.13 (−1.30%) at the Tokyo close Day range 63,807.15–64,822.22
Outlook: Bias is lower while 66,320 caps rallies. The index closed down 1.30% as SoftBank fell about 6% on AI-funding worries and the KOSPI dropped 3.73%; it is now more than 6,600 points under its 6 October close of 70,683.98.
Key levels
- Support 2
- 60,500.00
- Support 1
- 62,900.00
- Resistance 1
- 64,916.00
- Resistance 2
- 66,320.00
- Price (64,075.35) is under all three averages (66,970.61, 66,713.56 and 66,320.43); Monday’s close of 64,916 and the broken triangle floor are the first resistance.
- RSI 39.43 is far below its signal line at 55.59, a weak reading that favours selling bounces; the September low near 62,900 and the July low near 60,500 are the floors below.
Setup: Short at 64,900.00, stop 65,900.00, targets 62,900.00 and 60,500.00. Reward:risk 2.0 / 4.4, medium conviction.
DAX | DAX 40 Index, XETR feed
DAX 40 Analysis: Price Recovers From a 1% Dip and Tests the Middle of a Falling Channel
25,285.58 −34.19 (−0.14%) at 14:35 GMT Day range 25,050.11–25,288.21
Outlook: Bias is lower while 25,430 caps rallies. The DAX touched a low about 1% under Monday’s close on French unrest and Hormuz tensions, then bounced back to the 25,270 area, but it is still inside a channel that began at the late-August high.
Key levels
- Support 2
- 24,850.00
- Support 1
- 25,050.00
- Resistance 1
- 25,430.00
- Resistance 2
- 25,678.00
- Price (25,285.58) is just above the 25,268.90 average and under the 25,430.00 and 25,678.32 averages; the 25,678 average also sits near the channel roof.
- RSI 47.68 is above its signal line at 45.37, a neutral reading and a modest bounce; a close under 25,050 would open the early-October low near 24,850.
Setup: Short at 25,430.00, stop 25,720.00, targets 25,050.00 and 24,850.00. Reward:risk 1.3 / 2.0, low conviction.
CAC 40 | CAC 40 Index, TVC feed
CAC 40 Analysis: Price Stays Under Its Averages as French Unrest Weighs on Sentiment
7,861.50 −6.56 (−0.08%) at 14:35 GMT Day range 7,783.22–7,867.03
Outlook: Bias is lower while 7,912 caps rallies. French curfews in Paris and Nice, a wider spread over Germany and a Moody’s review of France on 23 October keep the CAC under pressure, and price is about 10% below its 7 August record near 8,755.
Key levels
- Support 2
- 7,500.00
- Support 1
- 7,700.00
- Resistance 1
- 7,912.51
- Resistance 2
- 8,165.41
- Price (7,861.50) is under the 7,912.51, 8,165.41 and 8,287.37 averages; the 7,912 average is the first resistance and the broken channel floor sits well above.
- RSI 40.84 is above its signal line at 35.02, a first bounce from weak territory rather than a trend change; the early-October low near 7,700 is the first floor.
Setup: Short at 7,910.00, stop 8,020.00, targets 7,700.00 and 7,500.00. Reward:risk 1.9 / 3.7, medium conviction.
NDX | Nasdaq 100 Index, NASDAQ feed
Nasdaq 100 Analysis: Price Bounces From a Channel Floor but Stays Under Every Average
29,579.46 +50.11 (+0.17%) at 14:35 GMT Day range 29,208.83–29,591.70
Outlook: Bias is lower while 29,863 caps rallies. The index is up 0.17% after Monday’s chip rebound, but AI-financing doubts remain and Meta and Tesla report after the US close on Wednesday.
Key levels
- Support 2
- 28,800.00
- Support 1
- 29,208.83
- Resistance 1
- 29,863.29
- Resistance 2
- 30,418.93
- Price (29,579.46) is just under the 29,610.28 average, with 29,863.29 and 30,418.93 stacked above; the channel floor near 29,100 held last week.
- RSI 42.02 is under its signal line at 55.09, a soft reading that is not yet oversold; conviction is low because a strong Meta or Tesla report could squeeze shorts.
Setup: Short at 29,860.00, stop 30,420.00, targets 29,200.00 and 28,780.00. Reward:risk 1.2 / 1.9, low conviction.
SPX | S&P 500 Index, SP feed
S&P 500 Analysis: Price Holds the Middle of a Rising Channel Above Its Averages
7,733.71 +42.98 (+0.56%) at 14:35 GMT Day range 7,668.03–7,733.71
Outlook: Bias is higher while 7,601 holds. The index is up 0.56% at its daily high, helped by industrial earnings and a Dow led by 3M and Merck, but breadth is thin and the Fed meets on 27–28 October.
Key levels
- Support 2
- 7,520.00
- Support 1
- 7,601.36
- Resistance 1
- 7,820.00
- Resistance 2
- 8,000.00
- Price (7,733.71) sits on the 7,734.00 average, above the 7,704.69 and 7,601.36 averages; the record close of 7,818.93 on 5 October is the first target.
- RSI 51.35 is under its signal line at 54.64, a neutral reading; a close under 7,601 would put the channel floor near 7,520 in play.
Setup: Long at 7,700.00, stop 7,610.00, targets 7,820.00 and 7,950.00. Reward:risk 1.3 / 2.8, medium conviction.
Conclusion
The S&P 500 is the strongest corner today, while the Nikkei, CAC and Nasdaq 100 sit under their averages. We prefer buying S&P 500 dips while 7,601 holds, selling rallies in the Nikkei and CAC 40 while they stay under 66,320 and 7,912, and treating the DAX and Nasdaq 100 as lower-conviction shorts because both have bounced from key floors. The nearest risks are Netflix tonight, Meta and Tesla on Wednesday after the US close, flash PMIs on Friday, the Moody’s review of France on 23 October and the FOMC at 18:00 GMT on 28 October. A daily close above 29,863 on the Nasdaq 100 would challenge the bearish view.
Trade Nikkei 225, DAX 40, CAC 40, Nasdaq 100 and S&P 500 with Capital Street FX.
Frequently Asked Questions
Why is the Nikkei 225 falling when US chip stocks rebounded?
Japan’s index is heavy in AI-linked names such as SoftBank, Advantest and Tokyo Electron, and investors are worried about how AI spending is financed. Rising yields and oil near $110 add to the pressure, so Monday’s Wall Street rebound did not carry over.
Why is the CAC 40 weaker than the DAX?
French unrest, curfews, a wider spread over German bonds and the 23 October Moody’s review are hitting domestic stocks, while the DAX has more exporters and industrials. The CAC is also about 10% under its August record.
Is the Nasdaq 100 oversold?
No. Its RSI is 42.02, which is soft but not oversold, and price is only just under its long average. That is why the setup is low conviction, and Meta and Tesla earnings on Wednesday can move it either way.
What does the Fed meeting mean for indices?
A hold on 28 October is expected, but a December hike is heavily priced in. A hawkish message would push yields above 5.1% and pressure growth indices such as the Nasdaq 100 and Nikkei 225 most.