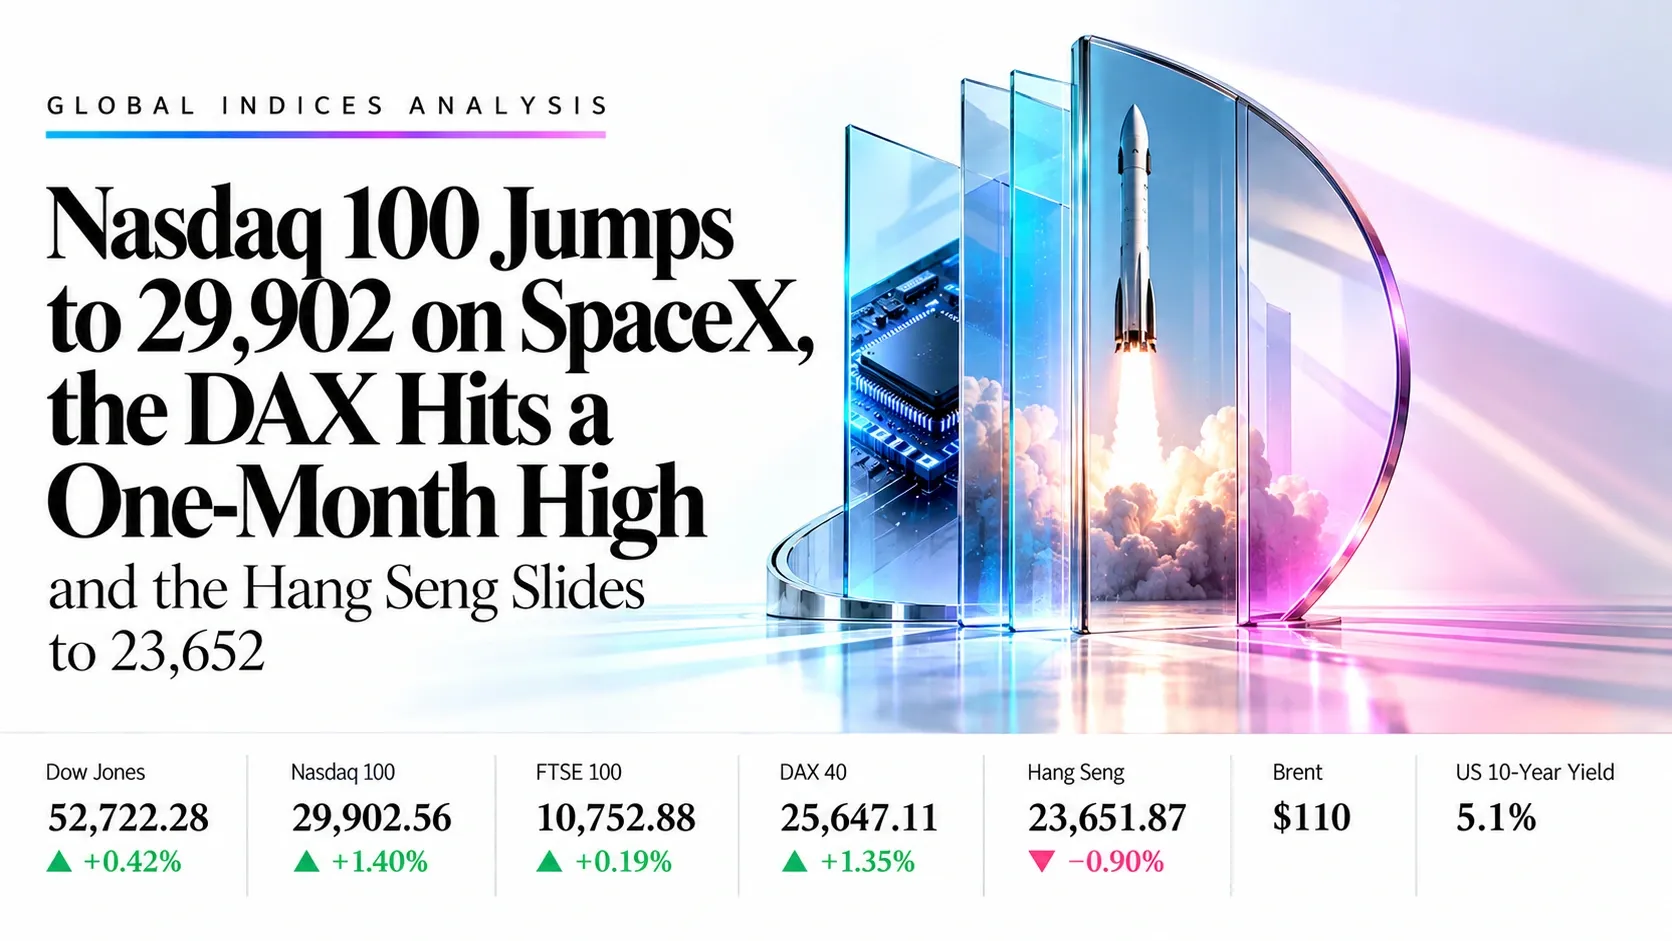
Nasdaq 100 Jumps to 29,902 on SpaceX, the DAX Hits a One-Month High at 25,647 and the Hang Seng Slides to 23,652
Indices Today | Wednesday 21 October 2026
Nasdaq 100 Jumps to 29,902 on SpaceX, the DAX Hits a One-Month High at 25,647 and the Hang Seng Slides to 23,652
Market Overview
Equities were mostly higher on Wednesday. At about 17:28 GMT the Dow Jones was 52,722.28 (+0.42%) and the Nasdaq 100 29,902.56 (+1.40%); Europe closed with the DAX at 25,647.11 (+1.35%) and the FTSE 100 at 10,752.88 (+0.19%), while the Hang Seng closed at 23,651.87 (−0.90%) (Bloomberg, Reuters, Investing.com, MT Newswires). SpaceX and Super Micro revived the AI trade, UK CPI rose to 3.5%, Brent is near $110, the US 10-year yield is about 5.1% and the Fed, ECB and Bank of England all decide within the next 16 days. We read the session as a tech-led rebound that is not yet confirmed: the Dow and DAX are testing resistance, the Nasdaq 100 is still under its short average and Hong Kong is sitting on its channel floor.
Key highlights
- Dow Jones: Price is 52,722 at a triangle roof; 52,400 is the key floor.
- Nasdaq 100: Price is 29,902 under the 30,386 average with RSI 47.40; Meta and Tesla report tonight.
- FTSE 100: Price is 10,753 above all three averages despite UK CPI at 3.5%; a BoE hike is about 95% priced.
- DAX 40: Price is 25,647 at a one-month high under the 25,665 average; SAP reports tonight.
- Hang Seng: Price is 23,652 under every average with RSI 34.96; 23,500 is the channel floor.
What’s Moving Indices Today
SpaceX’s record quarter revives the AI trade
SpaceX posted Q3 revenue of $14.6 billion, up 161%, and net income of $4.4 billion, and its shares rose 8% to 10%. Elon Musk also called a merger with Tesla “a good idea”. The Nasdaq 100 rose about 1.2% to 1.4% and chipmakers gained about 2%, while Meta and Tesla report after the close and Netflix fell about 5% on its ad forecast.
Dow hits a five-week high on earnings and cheaper oil
The Dow rose 1% on Tuesday to about 52,495 on earnings and softer crude, and it is up another 0.4% today. Jobless claims at 12:30 GMT on Thursday are forecast at 200,000 after 199,000 and feed the Fed decision on 28 October.
UK CPI hits 3.5% but the FTSE 100 still closes higher
Inflation rose to 3.5% in September against 3.4% expected and 3.1% in August, with core at 2.8%. Markets price about a 95% chance of a Bank of England hike on 5 November, yet the FTSE 100 closed up 0.19% at 10,752.88 as BP and Shell gained with oil and Entain rose 4.3%.
DAX jumps 1.35% to a one-month high on software and tech
The DAX closed at 25,647.11 and the Euro Stoxx 50 rose 1.50% to 6,213.45. SAP gained 3.5% to €208.65 ahead of its results after the close, while Rheinmetall fell 3.2% and Merck KGaA 2.8%. The ECB decides on 29 October.
Hang Seng gives up an early gain as Tencent and CATL fall
The index opened up 1.1% at 24,139 but closed down 0.90% at 23,651.87, its second straight loss and more than 530 points over two days. Tencent fell about 4% and the Hang Seng Tech Index lost 1.44% on AI spending worries and rising oil. The index is down about 7% for the year.
Oil near $110, the 10-year yield about 5.1% and a Fed hold priced
Brent settled near $108.79 on Tuesday after a high of $111.99 on conflicting US-Iran headlines and traded near $110 today. The Fed (3.75%–4.00%) decides on 28 October with a hold about 83% to 85% priced, and a December hike is heavily priced. Higher oil or yields would hit tech and Hong Kong first.
Key Drivers Ahead
Six events that set direction for the Dow Jones, Nasdaq 100, FTSE 100, DAX 40 and Hang Seng. All times are GMT.
- Meta and Tesla
- Q3
- Wed 21 Oct, after the US close
- Nasdaq 100 heavyweights; merger talk in focus
- SAP results
- Q3
- Wed 21 Oct, about 20:05 GMT
- Sets the tone for DAX software shares
- US jobless claims
- 200K
- Thu 22 Oct, 12:30 GMT
- Forecast 200K after 199K
- FOMC decision
- 28 Oct
- Wed 28 Oct, 18:00 GMT
- Hold about 83% to 85% priced; tone is key
- ECB decision
- 29 Oct
- Thu 29 Oct
- DAX reaction; US Q3 GDP and PCE at 12:30 GMT
- Bank of England
- 5 Nov
- Thu 5 Nov
- Hike about 95% priced after 3.5% CPI
Swipe the strip to see every driver.
Trade Setups for Today
Ranked in the order Dow Jones, Nasdaq 100, FTSE 100, DAX 40 and Hang Seng, valid for today’s session and tomorrow’s Asian open. A 1-hour close beyond the stop cancels the idea.
| Instrument | Direction | Entry | Stop | Target 1 | Target 2 | Reward:risk | Conviction |
|---|---|---|---|---|---|---|---|
| Dow Jones | Long | 52,450 | 51,950 | 53,200 | 53,750 | 1.5 / 2.6 | Medium |
| Nasdaq 100 | Long | 29,650 | 29,100 | 30,390 | 31,000 | 1.3 / 2.5 | Low |
| FTSE 100 | Long | 10,690 | 10,600 | 10,890 | 10,985 | 2.2 / 3.3 | Medium |
| DAX 40 | Long | 25,450 | 25,180 | 26,000 | 26,300 | 2.0 / 3.1 | Medium |
| Hang Seng | Short | 24,300 | 24,650 | 23,500 | 22,950 | 2.3 / 3.9 | Medium |
Reward:risk is the distance from entry to each target divided by the distance from entry to the stop. Prices are read at about 17:28 GMT on 21 October from TradingView daily charts, with DAX, FTSE 100 and Hang Seng closes matched to Investing.com; every entry sits away from the current price and needs a pullback or a bounce to trigger. Levels are conditional technical references, not recommendations.
Risk Scenario Analysis
Oil, US yields and the tech earnings tonight are the swing factors, with the Fed on 28 October the main event next week.
Risk-off returns: oil above $110, a hawkish Fed and weak Meta or Tesla results
Higher oil, a rise in the 10-year yield or a miss from Meta or Tesla would hit the Nasdaq 100 and Hang Seng first.
- Dow Jones52,400, then 51,950
- Nasdaq 10029,605, then 29,100
- FTSE 10010,709, then 10,646
- DAX 4025,439, then 25,180
- Hang Seng23,500, then 22,950
Risk-on extends: an Iran deal eases oil and tech earnings hold up
Easing oil, solid tech results and a cautious Fed would push the Dow and DAX through their roofs.
- Dow Jones53,200, then 53,750
- Nasdaq 10030,386, then 31,000
- FTSE 10010,890, then 10,985
- DAX 4025,665, then 26,000
- Hang Seng24,305, then 24,770
Dow Jones Industrial Average | US 30, TVC feed
Dow Jones Analysis: Price Tests the Falling Roof of a Wide Triangle Near 52,700
52,722.28 +221.04 (+0.42%) at about 17:28 GMT Day range 52,397.24–52,759.28
Outlook: Bias is higher while 52,400 holds. The Dow is at a five-week high after Tuesday’s 1% rally and is pressing the falling trendline from the August peak, but the 28 October Fed decision keeps a cap on risk appetite.
Key levels
- Support 2
- 51,950
- Support 1
- 52,400
- Resistance 1
- 53,200
- Resistance 2
- 53,750
- Price (52,722) sits on the falling line from the 54,800 August high; a daily close above 52,750 would confirm a triangle breakout toward 53,700.
- RSI 61.23 is above its signal line at 48.66, a clear recovery from the early-October low near 50,600; a close under 52,400 would put the breakout in doubt.
Setup: Long at 52,450, stop 51,950, targets 53,200 and 53,750. Reward:risk 1.5 / 2.6, medium conviction.
Nasdaq 100 Index | NDX, Nasdaq feed
Nasdaq 100 Analysis: Price Rebounds From a Rising Channel Floor and Retakes Two Averages Below 30,400
29,902.56 +412.28 (+1.40%) at about 17:28 GMT Day range 29,593.70–29,916.95
Outlook: Bias is neutral to higher while 29,605 holds. SpaceX’s blowout quarter revived the AI trade, but price is still under the 30,386 average and Meta and Tesla report after the close.
Key levels
- Support 2
- 29,100
- Support 1
- 29,605
- Resistance 1
- 30,386
- Resistance 2
- 31,000
- Price (29,902) is above the 29,869 and 29,605 averages and under the 30,386 average, the first hurdle; the channel floor near 29,100 is the main support.
- RSI 47.40 is under its signal line at 54.00, so momentum has not turned yet; a close above 30,386 would aim at the 31,300 October high.
Setup: Long at 29,650, stop 29,100, targets 30,390 and 31,000. Reward:risk 1.3 / 2.5, low conviction.
FTSE 100 Index | UKX, FTSE feed
FTSE 100 Analysis: Price Holds Above All Three Averages Inside a Rising Triangle Under 11,000
10,752.88 +19.88 (+0.19%) at about 17:28 GMT Day range 10,703.95–10,775.94
Outlook: Bias is higher while 10,646 holds. The FTSE 100 shrugged off UK CPI at 3.5% to close up, helped by oil majors, though a Bank of England hike on 5 November is now about 95% priced.
Key levels
- Support 2
- 10,646
- Support 1
- 10,709
- Resistance 1
- 10,890
- Resistance 2
- 10,985
- Price (10,753) is above the 10,709, 10,646 and 10,634 averages, which cluster as support; the 10,890 October high is the first resistance.
- RSI 54.77 is above its signal line at 48.68; a close under 10,634 would send price back to the rising floor near 10,400.
Setup: Long at 10,690, stop 10,600, targets 10,890 and 10,985. Reward:risk 2.2 / 3.3, medium conviction.
DAX 40 Index | GER40, Xetra feed
DAX 40 Analysis: Price Tests the Roof of a Falling Channel at a One-Month High
25,647.11 +342.69 (+1.35%) at about 17:28 GMT Day range 25,249.96–25,706.19
Outlook: Bias is higher while 25,439 holds. The DAX led Europe on software and tech gains, with SAP up 3.5% before its results tonight, but it is pressing the channel roof and the 25,665 average where sellers have appeared before.
Key levels
- Support 2
- 25,180
- Support 1
- 25,439
- Resistance 1
- 25,665
- Resistance 2
- 26,000
- Price (25,647) is above the 25,439 and 25,282 averages and just under 25,665; a daily close above the channel roof would target 26,000.
- RSI 55.26 is above its signal line at 46.88; a failure at the roof would likely send price back to retest 25,439.
Setup: Long at 25,450, stop 25,180, targets 26,000 and 26,300. Reward:risk 2.0 / 3.1, medium conviction.
Hang Seng Index | HK50, HSI feed
Hang Seng Analysis: Price Falls to the Floor of a Falling Channel Under Every Average
23,651.87 −215.87 (−0.90%) at about 17:28 GMT Day range 23,620.10–24,139.11
Outlook: Bias is lower while 24,305 caps rallies. The index gave up a 1.1% opening gain as Tencent and CATL fell, and it is down about 7% this year, but RSI is near oversold so a bounce is likely first.
Key levels
- Support 2
- 22,950
- Support 1
- 23,500
- Resistance 1
- 24,305
- Resistance 2
- 24,770
- Price (23,652) is under the 24,305, 24,771 and 24,904 averages; the 24,305 average is the first resistance on any bounce.
- RSI 34.96 is under its signal line at 39.16 and near oversold; a close under the channel floor near 23,500 would open the June low at 22,518.
Setup: Short at 24,300, stop 24,650, targets 23,500 and 22,950. Reward:risk 2.3 / 3.9, medium conviction.
Conclusion
The Dow Jones and FTSE 100 have the best structure today, with price above rising floors or clustered averages. We prefer buying Dow pullbacks while 51,950 holds and FTSE 100 pullbacks while 10,600 holds, buying the DAX on a retest of 25,439, treating the Nasdaq 100 long as lower conviction until Meta and Tesla report, and selling Hang Seng bounces under 24,650. The nearest risks are Meta, Tesla and SAP results tonight, US jobless claims at 12:30 GMT on Thursday, the FOMC at 18:00 GMT on 28 October, the ECB on 29 October and the Bank of England on 5 November. A daily Dow close above 52,750 would confirm its triangle breakout.
Trade the Dow Jones, Nasdaq 100, FTSE 100, DAX 40 and Hang Seng with Capital Street FX.
Frequently Asked Questions
Why did the Nasdaq 100 rally today?
SpaceX reported Q3 revenue up 161% and a $4.4 billion profit, and Super Micro raised its outlook, easing doubts about AI spending. Price is still under the 30,386 average and Meta and Tesla report after the close, so the move is not yet confirmed.
Why did the Hang Seng fall while Wall Street and Europe rose?
Tencent and CATL fell, AI investment worries hit tech and oil rose, so Hong Kong gave up a 1.1% opening gain. The index is on its channel floor with RSI near 35, so a bounce is possible, but it remains under all three averages.
Why did the DAX beat the FTSE 100 today?
Software and tech shares led Europe, with SAP up 3.5% ahead of results, while the FTSE 100 was held back by UK CPI at 3.5% and a likely Bank of England hike. The DAX rose 1.35% to a one-month high against 0.19% for the FTSE 100.
How does the Fed on 28 October affect these indices?
A hold is about 83% to 85% priced, but a hawkish message with a December hike would lift yields above 5.1% and pressure the Nasdaq 100 and Hang Seng most. A cautious tone would help tech and extend the Dow breakout.