Eurozone Inflation Jumps to 3.3% as Bund Yields Hit a 15-Year High and Oil Extends Its Iran-Driven Surge | Technical Analysis – European Session | 01-09-2026
Eurozone Inflation Jumps to 3.3% as Bund Yields Hit a 15-Year High and Oil Extends Its Iran-Driven Surge
EUR/USD · EUR/CHF · Silver · Crude Oil · DAX 40 · EU 20Y Yield · ETH/USD · Dogecoin — live European market outlook today, updated through the trading session
European Market News — Live Now, 1 September 2026
Top-moving headlines shaping the European market outlook today, updated through the morning
Eurozone Flash CPI Jumps to 3.3% as Energy Inflation Surges on the Iran Conflict
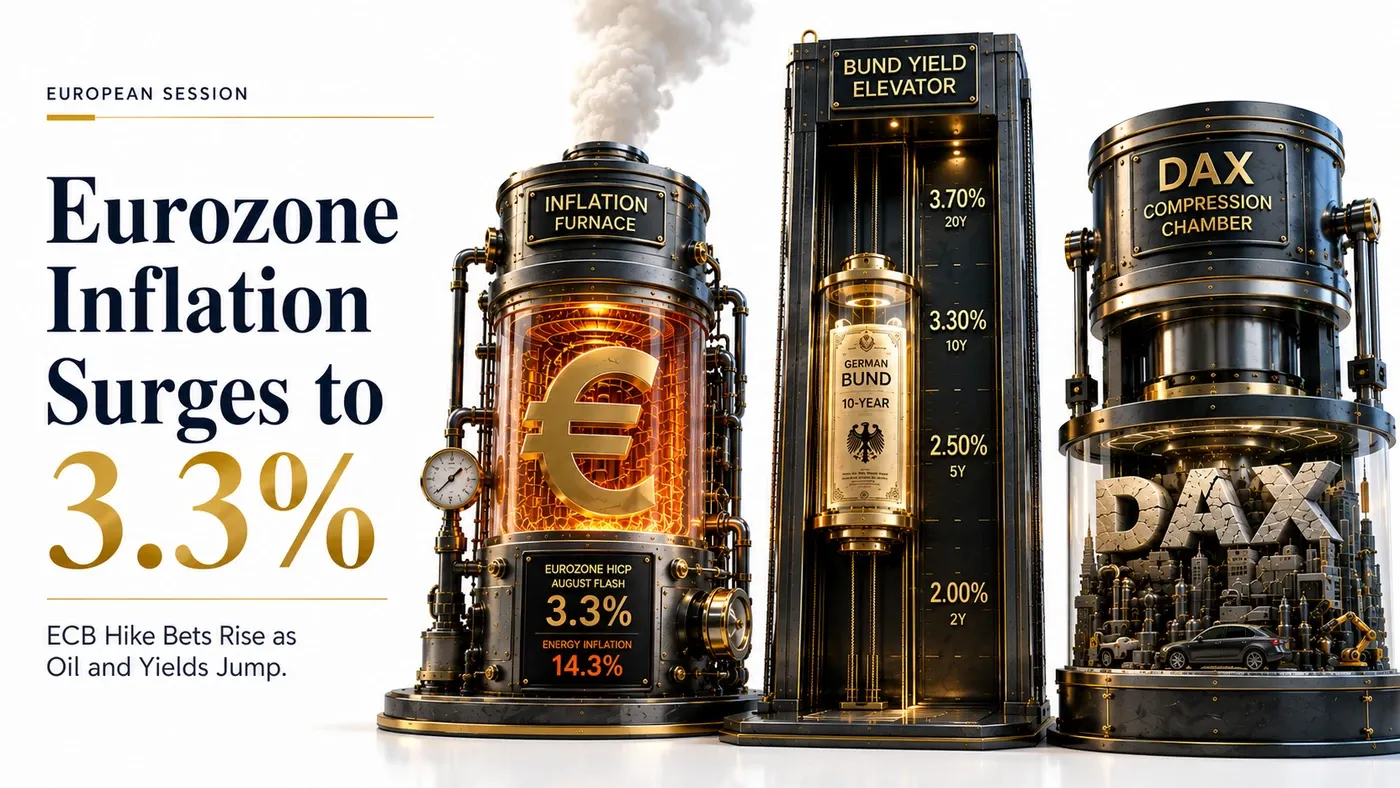
Eurozone headline HICP inflation accelerated to 3.3% year-on-year in August from 2.9% in July, above the 3.2% consensus, as energy inflation jumped to 14.3% from 10.3% amid the renewed Strait of Hormuz escalation. Core inflation eased to 2.4% from 2.5%, undershooting expectations as services inflation cooled to 3.0% from 3.3%, leaving the ECB with a genuine split between accelerating headline prices and softening underlying pressure heading into September.
Macro DataGerman Bund Yields Hit Their Highest Since 2011 as ECB Hike Bets Firm
Germany’s 10-year Bund yield touched 3.3% for the first time since May 2011, with the 20-year trading near 3.70%, as French, Dutch, Italian and Spanish yields all climbed to multi-year highs on the combination of rising oil prices and hawkish central-bank signalling. Markets now price roughly an 80% probability of a 25-basis-point ECB hike to 2.50% at the 10 September meeting, with about a 40% chance of a further move in December.
RatesGerman Manufacturing PMI Confirmed at 54.3, Strongest Since Early 2022
Germany’s final HCOB Manufacturing PMI for August was confirmed at 54.3, up from a 54.1 flash reading and 52.2 in July, marking the strongest pace of production growth since January 2022 as new orders and export sales accelerated. Business expectations improved to their brightest level since before the Middle East conflict escalated in February, even as supply-chain pressures intensified further.
Macro DataOil Extends Its Advance as US-Iran Strikes Continue Near the Strait of Hormuz
Brent crude is holding above $91 a barrel and WTI near $87.87 after US forces targeted Iranian rocket launchers on Larak Island and Tehran retaliated with strikes on Jordan and the UAE, while a tanker reportedly struck naval mines in the southern Strait of Hormuz. Refinery strikes in Russia have further tightened global refining capacity, pushing refined-product margins to fresh highs and keeping a geopolitical risk premium embedded across the energy complex.
GeopoliticsDAX Slips to a Two-Week Low as Banks and Autos Lead the Retreat
Germany’s DAX 40 has fallen 0.4% to around 25,993.90, its lowest level since 24 August, as investors weigh the prospect of a prolonged US-Iran conflict fuelling energy-driven inflation and tighter monetary policy from both the ECB and the Fed. Energy-sensitive industrials, banks and autos are the hardest hit sectors, while gains in pharma, chipmakers, chemicals and utilities are cushioning the broader index’s losses.
EquitiesEthereum and Dogecoin Soften as Hawkish Fed Tone Ends ETH’s ETF Inflow Streak
ETH/USD has eased toward $2,450.50 after a nine-day, $1.42 billion streak of net inflows into US spot Ethereum ETFs came to an end on the same day as Fed Chair Kevin Warsh’s hawkish Jackson Hole keynote, which pushed September rate-hike odds to roughly 56-57%. Dogecoin is trading near $0.0834, down on the day but still on track for its strongest monthly performance in a year after gaining more than 21% in August.
CryptoLive · Updated through the European morning session, Tuesday 1 September 2026
European Economic Calendar This Week — 1 September 2026
Key releases and events shaping price action through the rest of the week
| Time | Event | Forecast / Detail | Impact | Market Read |
|---|---|---|---|---|
| 🇺🇸Friday, 28 August (Recap) | Fed Chair Kevin Warsh’s First Jackson Hole Keynote | Hawkish tone; September Fed odds rose to roughly 56-57% | 🔴 CRITICAL | Still the dominant driver of the Dollar’s broad strength into September |
| 🇪🇺Today (Released) | Eurozone Flash HICP (August) | 3.3% y/y actual vs 3.2% expected, 2.9% prior | 🔴 CRITICAL | Hot headline print firms the case for a September ECB hike |
| 🇩🇪Today (Released) | Germany Final Manufacturing PMI (August) | 54.3 actual vs 54.1 flash, 52.2 prior | 🟢 MEDIUM | Strongest production growth since January 2022; supportive for the Euro |
| 🇩🇪Today (Ongoing) | German 10Y Bund Yield Near 15-Year High | Yield touched 3.3%, highest since May 2011 | 🔴 CRITICAL | Reflects hawkish repricing across the Eurozone rates curve |
| 🇮🇷Ongoing | US Strikes Iranian Assets Near the Strait of Hormuz; Iran Retaliates | Tanker reportedly struck naval mines; Russian refinery strikes add to supply risk | 🔴 CRITICAL | Keeps oil, yields and broader risk sentiment on edge into the European close |
| 🇪🇺Thursday, 10 September | ECB Governing Council Meeting | ~80% probability of a 25bp hike to 2.50%; ~40% for a further December move | 🔴 CRITICAL | The dominant near-term catalyst for EUR/USD and EUR/CHF direction |
| 🇨🇭Ongoing | SNB Holding Policy Rate Near Zero | SNB seen leaning on FX intervention to curb Franc strength | 🟢 MEDIUM | Widening ECB-SNB rate gap keeps EUR/CHF’s tone constructive |
European Session Trade Ideas — EUR/USD, EUR/CHF and More
Technical setups and fundamental context across the session’s eight key instruments
EUR/USD
Why This Setup
The hot Eurozone flash CPI print and the strongest German Manufacturing PMI since early 2022 are genuine tailwinds that firm the case for a September ECB hike, though the broad Dollar bid from Warsh’s hawkish Jackson Hole keynote and roughly 56-57% odds of a September Fed hike remain a real source of two-way risk.

EUR/CHF
Why This Setup
An SNB seen holding near zero and leaning on FX intervention to curb Franc strength, against an ECB likely to hike in September, is a genuine tailwind for the pair’s push toward 0.9400 and UBS’s 0.94 year-end target, though any fresh bout of Middle East-driven risk aversion boosting the Franc’s safe-haven bid is a real source of two-way risk.

Silver
Why This Setup
Firming ECB and Fed rate-hike expectations pushing real yields higher are genuine headwinds for non-yielding Silver near its recent highs, though the same Iran-driven inflation shock lifting energy prices is a real source of two-way risk that could reignite the metal’s inflation-hedge bid.

Crude Oil
Why This Setup
Fresh US strikes near the Strait of Hormuz, a reported tanker mine strike, and Russian refinery outages tightening refined-product supply are genuine tailwinds, though continued Gulf-producer exports and any de-escalation headline out of Tehran are a real source of two-way risk.

DAX 40
Why This Setup
Rising Bund yields and oil-driven inflation concerns weighing on rate-sensitive banks, autos and industrials are genuine headwinds, though the strongest German Manufacturing PMI since early 2022 and resilient pharma, chip and chemical names are a real source of two-way risk that could limit downside.

EU 20Y Yield
Why This Setup
Firming ECB hike bets into the 10 September meeting alongside oil-driven inflation and heavy long-end issuance are genuine tailwinds for yields to grind higher, though any sharp de-escalation in the Strait of Hormuz or a dovish ECB surprise are a real source of two-way risk that could cap the move.

ETH/USD
Why This Setup
The nine-day, $1.42 billion run of US spot Ethereum ETF inflows led by BlackRock’s ETHA fund is a genuine tailwind pointing to structural institutional demand, though the hawkish Fed tone that ended the streak and roughly 56-57% odds of a September Fed hike are a real source of two-way risk.

Dogecoin
Why This Setup
August’s 21%-plus gain, its best month in over a year, alongside its regulatory classification as a digital commodity, is a genuine tailwind for continued institutional and retail interest, though the hawkish-Fed-driven risk-off tone spilling across broader crypto markets is a real source of two-way risk.

European Session FAQ — 1 September 2026
Quick answers to the questions traders are asking this session
Why did Eurozone inflation jump to 3.3% and what does it mean for the ECB?
Why are German Bund yields at their highest level since 2011?
Why is the DAX 40 falling despite a strong German PMI?
Why is Crude Oil extending its advance today?
Why is EUR/CHF pushing toward 0.9400?
Why did Ethereum’s ETF inflow streak come to an end?
Is Dogecoin’s pullback today a concern for its August rally?
What should traders watch for the rest of the European session?
European Session Summary — Tuesday, 1 September 2026 (Live Update)
Tuesday’s European session is trading on the back of a genuinely hot Eurozone inflation print, with flash HICP inflation for August accelerating to 3.3% year-on-year from 2.9% in July, well above the 3.2% consensus, as energy inflation surged to 14.3% amid the renewed Strait of Hormuz escalation, even as core inflation eased to 2.4% on softer services prices. German Bund yields have pushed to their highest level since May 2011, with the 10-year touching 3.3% and the 20-year near 3.70%, as markets price roughly an 80% probability of a 25-basis-point ECB hike to 2.50% at the 10 September meeting.
Germany’s final Manufacturing PMI was confirmed at 54.3, its strongest reading since January 2022, yet the DAX 40 has slipped 0.4% to around 25,993.90 as rate-sensitive banks, autos and industrials are outweighed by rising yields and oil prices, even as pharma, chip and chemical names cushion the broader index. EUR/USD is holding near 1.1595, clawing back part of Monday’s slide as the hot inflation print and strong PMI reinforce ECB hike bets, even against the broad Dollar bid from Fed Chair Kevin Warsh’s hawkish Jackson Hole keynote and roughly 56-57% odds of a September Fed hike. EUR/CHF is firm near 0.9390 as the widening ECB-SNB rate gap keeps pressure on the Franc.
Crude Oil is extending its advance toward $87.87 (Brent near $91.30) after fresh US strikes near the Strait of Hormuz and Russian refinery outages tightened global supply, and Silver is consolidating near $65.03 an ounce as the same hawkish rate repricing weighs on the metal despite its strong August. Crypto markets are softer, with ETH/USD easing toward $2,450.50 as a nine-day, $1.42 billion ETF inflow streak came to an end on Warsh’s keynote day, and Dogecoin cooling near $0.0834 after its strongest monthly gain in over a year.
Highest-conviction session idea: favour dips in the ECB-supported Euro complex and the supply-constrained Crude Oil and EU 20Y yield trades, while fading DAX rallies into resistance, staying alert to any further Strait of Hormuz escalation as the dominant swing factor for risk sentiment into the ECB’s 10 September decision.
For the individual instruments: EUR/USD buy dips toward 1.1550, stop 1.1480, target 1.1750 — the hot Eurozone CPI print and strong German PMI are a genuine tailwind, though the broad post-Warsh Dollar bid is a real source of two-way risk. EUR/CHF buy dips toward 0.9330, stop 0.9280, target 0.9450 — the widening ECB-SNB rate gap is a genuine tailwind, though renewed Middle East-driven safe-haven flows into the Franc are a real source of two-way risk. Silver sell rallies toward $69.00, stop $71.00, target $62.50 — firming ECB and Fed hike bets are a genuine headwind, though the same energy-driven inflation shock is a real source of two-way risk. Crude Oil buy dips toward $82.50, stop $79.50, target $92.00 — renewed Strait of Hormuz strikes and Russian refinery outages are a genuine tailwind, though any de-escalation headline is a real source of two-way risk. DAX 40 sell rallies toward 26,600, stop 27,000, target 25,300 — rising yields and oil-driven inflation concerns are a genuine headwind, though the strong Manufacturing PMI is a real source of two-way risk. EU 20Y Yield buy dips toward 3.60%, stop 3.50%, target 3.95% — firming ECB hike bets are a genuine tailwind, though a dovish ECB surprise is a real source of two-way risk. ETH/USD buy dips toward $2,300, stop $2,150, target $2,750 — the nine-day ETF inflow streak is a genuine tailwind, though the hawkish-Fed-driven pause is a real source of two-way risk. Dogecoin buy dips toward $0.0770, stop $0.0715, target $0.0950 — August’s strong monthly gain is a genuine tailwind, though hawkish-Fed-driven crypto risk-off is a real source of two-way risk. The decisive variable for the rest of the day is the market’s ongoing digestion of the hot Eurozone inflation print alongside the Strait of Hormuz escalation, both of which are likely to define cross-asset sentiment into the ECB’s 10 September decision. Size positions accordingly, and note that fast-moving Middle East headlines carry genuine event risk that could exaggerate moves in either direction.
Ready to act on today’s setups? Open an Account with Capital Street FX and trade every instrument covered in this report on our Zero Account‘s 0.0 Pips Spreads and 1:10000 Leverage, across 2000+ Instruments, with a welcome deposit bonus and 24/7 Live Support on hand for every session.
Not sure which account fits your style? Compare our Account Types side by side with our Account Comparison tool, browse current Promotions / Bonus offers, and trade from our Trading Platform suite. Funding is simple via our Deposit & Withdrawal options. For ongoing coverage, explore our Forex Analysis Pages, Commodity Analysis Pages and Crypto Analysis Pages, plus our Daily Market Analysis and Weekly Market Analysis reports and the full Economic Calendar. New to trading? Visit our Trading Education / Blog, or reach our Contact Us / Live Support team any time.
Access Live European Markets →