Week Ahead, 24–29 August: Jackson Hole, Australia CPI & Nvidia Earnings | Weekly Analysis | Asian Session
Week Ahead, 24–29 August: Jackson Hole Takes Center Stage as Warsh Delivers His First Keynote, Australia’s CPI and Nvidia Earnings Round Out the Agenda
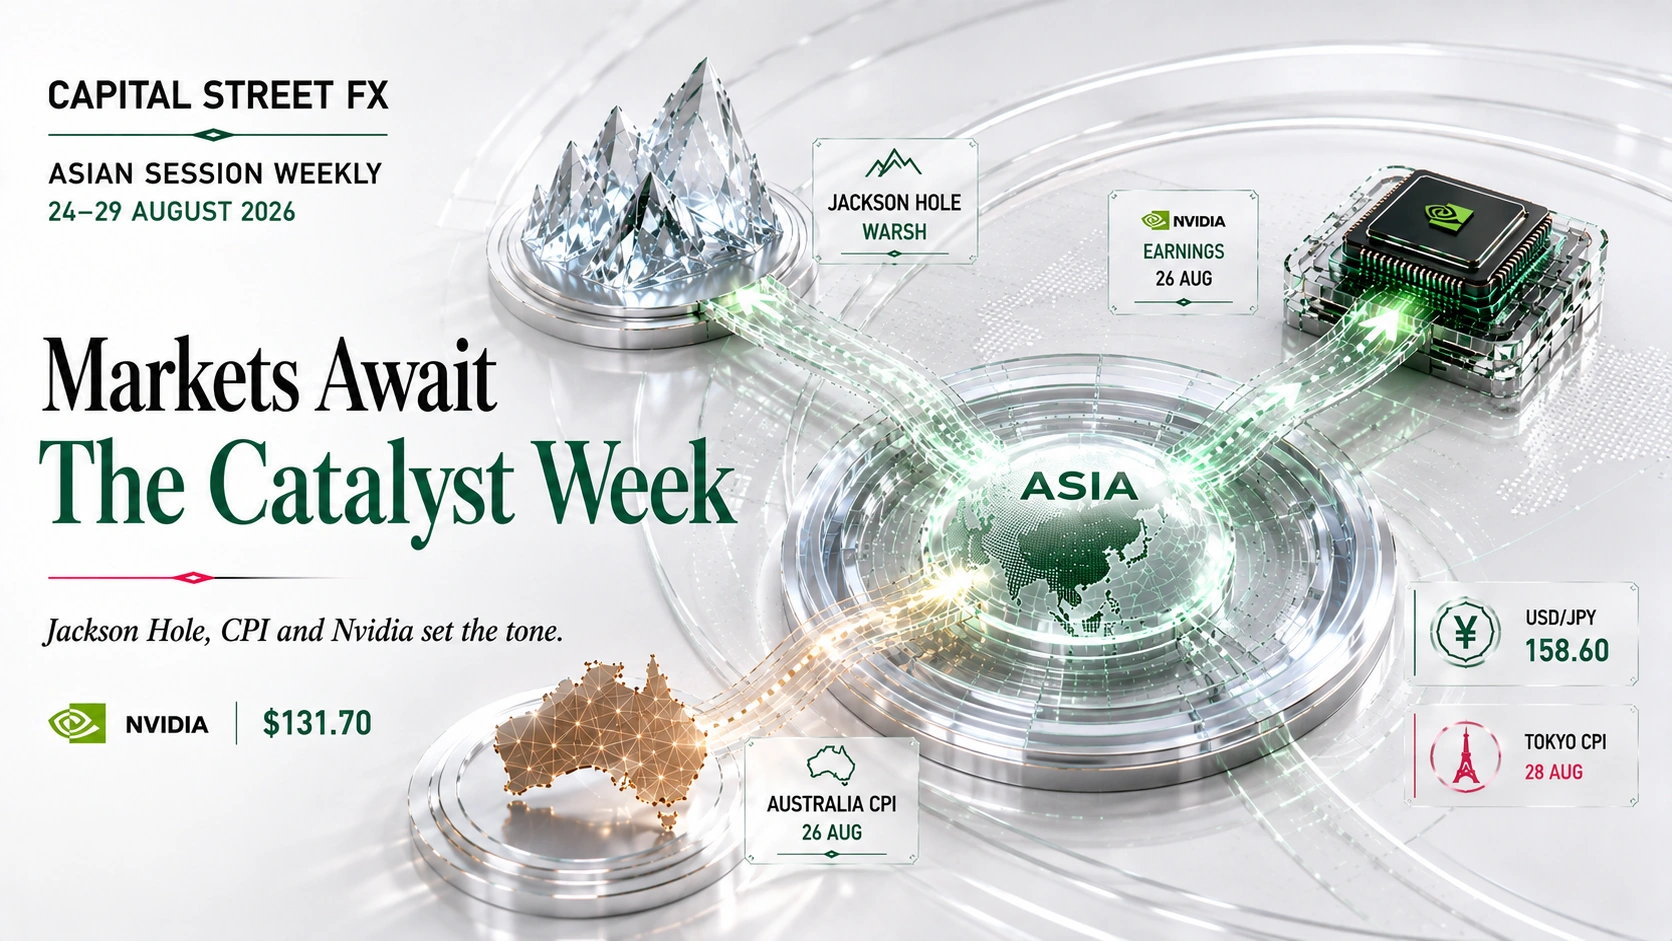
Australia CPI Wed 26 Aug · Nvidia Earnings Wed 26 Aug (Asia Thu AM) · Jackson Hole Symposium Thu–Sat 27–29 Aug, Warsh Keynote Fri 28 Aug · Full Asian session economic calendar for week of 24–29 August 2026
1. USD/JPY — does a hawkish BOJ debate finally halt the yen’s drift back toward 160? USD/JPY at 158.60 sits in a tug-of-war between two forces: Japan’s accelerating inflation, which has strengthened the case for a Bank of Japan hike as soon as September or October, and the still-fresh memory of last month’s confirmed joint US-Japan intervention, which continues to discourage aggressive yen-selling. Friday’s Tokyo CPI for August, the earliest read on the following month’s national inflation figures, is this week’s clearest domestic catalyst; CSFX sees a hot print as the more likely of the two outcomes to move the pair, given the string of upside inflation surprises already logged this month.
2. AUD/USD — Wednesday’s CPI print is the week’s single most important scheduled event for the Aussie. AUD/USD at 0.7160 heads into the week with the Reserve Bank of Australia’s next policy meeting still weeks away, leaving Wednesday’s July Consumer Price Index release at 11:30am AEST as the dominant scheduled catalyst. The June quarter print showed annual inflation running at 3.9%, above the RBA’s target band, and a similarly firm July monthly read would sharpen the case that the central bank’s easing bias is premature. Australia’s Private New Capital Expenditure data, released the same morning, adds a secondary read on business investment appetite.
3. Copper and the Hang Seng — a fading supply squeeze meets an AI-driven risk-on tape. Copper at $6.52/lb enters the week on firmer footing after a weaker dollar lifted metals broadly, but the structural story has shifted: LME warehouse inventories logged their largest weekly inflow since 2020 last week, snapping a seven-week winning streak and easing some of the acute physical tightness that dominated the narrative through much of August. The Hang Seng, at 26,009, has instead been the stronger story, rising for a second straight session as Chinese AI and semiconductor names rallied on new model launches and a marquee Shanghai chip IPO; Wednesday’s Nvidia earnings, landing in the Asian session early Thursday, are the week’s clearest test of whether that AI-driven bid extends or fades.
4. XRP and Litecoin — trading without a catalyst as the regulatory clock keeps ticking toward September. With the Senate confirmed to remain in recess until 14 September, XRP at $1.05 continues to defend the psychologically important $1.00 level without the CLARITY Act catalyst that had underpinned much of its earlier-2026 narrative. Litecoin, at $42.95, faces a more purely technical question this week: after slipping through its closely watched rising trendline last week, whether it can reclaim that level or continues to drift toward the next support band.
Three Forces That Will Drive the Asian Session — 24 to 29 August 2026
The scheduled Asian-session catalysts that will set the direction across FX, equities, and digital assets for the week of 24–29 August 2026
Asian Session Weekly Levels & Bias
Six instrument-specific reference levels for the week of 24–29 August 2026. All levels for reference and informational purposes only; not financial advice. Visit capitalstreetfx.com for live signals and other markets.
What to Watch — Tokyo CPI Friday Is the Key Swing Factor
USD/JPY is caught between building Bank of Japan hike expectations, following two straight months of hotter-than-expected inflation, and the lingering deterrent effect of last month’s confirmed joint US-Japan intervention. Friday’s Tokyo CPI for August is the earliest available read on where national inflation is heading, and CSFX sees a hot print as the more likely trigger for a fresh test of the 156.50 support zone, while a soft surprise or a hawkish Warsh tone at Jackson Hole could instead reopen the door to 160.00.

What to Watch — July CPI Is the Week’s Clearest AUD Catalyst
With no RBA meeting this week, Wednesday’s July CPI at 11:30am AEST carries outsized weight for AUD/USD. June quarter inflation printed at 3.9% year-on-year, above the RBA’s target band, and a similarly firm July read would sharpen questions about how much further easing the central bank can justify. Australia’s Private Capital Expenditure data, released the same morning, is a secondary input worth watching for signs of business investment momentum.

What to Watch — LME’s Largest Weekly Inflow Since 2020 Complicates the Supply Story
Copper’s acute physical squeeze — driven for weeks by the DRC’s concentrate export ban and record-low LME inventories — showed its first real crack last week as warehouse stocks logged their biggest weekly build since 2020, snapping a seven-week price winning streak. A weaker US dollar is providing an offsetting bid heading into this week, and CSFX sees China’s industrial profits data, expected around Thursday, as the next data point most likely to clarify whether demand-side conditions can absorb the newly rebuilding supply.

What to Watch — Nvidia’s Earnings Are the Week’s Clearest Test of the AI-Led Rally
The index has climbed for a second straight session as Chinese AI and chip shares rebounded on new model launches and a marquee Shanghai semiconductor IPO, even as broader manufacturing data has been softer. Wednesday’s Nvidia earnings, landing in the Asian session early Thursday, are the week’s most direct read-through for Hong Kong’s AI and chip-linked complex; a strong report and guidance would likely extend the current bid, while a disappointing outlook could quickly reverse recent gains.

What to Watch — A Genuine Catalyst Vacuum Leaves the Chart in Charge
LTC slipped through the closely watched rising trendline it had defended through much of August, with sellers now in control of the near-term structure. With the CLARITY Act still shelved until at least 14 September, CSFX sees no fundamental catalyst likely to reverse the trend this week; the $40.00 area is the next meaningful technical support, while a reclaim of the broken trendline near $45.00 would be the clearest signal that buyers have regained control.

What to Watch — No Realistic Legislative Catalyst Before Mid-September
XRP has not closed a day below $1.00 all year, and that level remains the key line in the sand for the week ahead. With the Senate confirmed to stay away from Washington until 14 September, CSFX continues to see the token trading as a range instrument between the $1.00 support zone and resistance closer to $1.18, with the next realistic legislative or regulatory catalyst still roughly three weeks away.

What Could Move Asian Markets Sharply This Week
The scheduled and unscheduled events that CSFX is watching most closely for the Asian session, 24–29 August 2026
Asian Session — Economic Calendar, 24–29 August 2026
All times approximate, Hong Kong Time (HKT, UTC+8) unless noted. Key releases for USD/JPY, AUD/USD, Copper, Hang Seng, Litecoin, and XRP.
| Day | Time (HKT) | Release | Impact | Forecast | CSFX View |
|---|---|---|---|---|---|
| Monday, 24 August | |||||
| Mon | All Day | Pre-Jackson Hole Positioning Across FX and Rates | LOW | N/A | A quiet scheduled calendar leaves the session to trade largely on positioning ahead of Wednesday’s CPI and the Thursday–Saturday Jackson Hole symposium. |
| Tuesday, 25 August | |||||
| Tue | Evening HKT | US Conference Board Consumer Confidence (August) | MED | N/A | Lands after the Asian close but sets the tone for Wednesday’s opening in Tokyo and Hong Kong. |
| Wednesday, 26 August | |||||
| Wed | ~09:30 HKT | Australia CPI (July) & Private Capital Expenditure | HIGH | N/A | The week’s single most important scheduled event for AUD/USD, released 11:30am AEST in the absence of a fresh RBA meeting. |
| Wed | ~04:00 HKT (Thu) | Nvidia Fiscal Q2 Earnings | HIGH | N/A | Reported after the US close; the reaction hits Asian AI and semiconductor names first thing Thursday morning. |
| Thursday, 27 August | |||||
| Thu | All Day | Jackson Hole Economic Policy Symposium Begins | MED | N/A | Day one of the three-day symposium; markets begin positioning ahead of Friday’s Warsh keynote. |
| Thu | All Day | China Industrial Profits (January–July) | MED | N/A | Cumulative profits data typically lands in the final days of the month; relevant context for copper and the Hang Seng. |
| Friday, 28 August | |||||
| Fri | ~07:30 HKT | Tokyo CPI (August) | HIGH | N/A | The earliest read on national inflation and the week’s key domestic catalyst for USD/JPY given the ongoing BOJ hike debate. |
| Fri | Evening HKT | Fed Chair Kevin Warsh’s Jackson Hole Keynote & US July PCE Inflation | HIGH | N/A | Warsh’s first keynote as chair, alongside the Fed’s preferred inflation gauge; both land after the Asian close, with the fullest reaction likely carrying into the following week. |
| Saturday, 29 August | |||||
| Sat | All Day | Jackson Hole Symposium Concludes | LOW | N/A | No Asian trading session, but follow-up commentary from attending officials over the weekend can still shape Monday’s open. |
Asian Session — Trader Questions Answered
Key questions from CSFX clients ahead of Jackson Hole, Australia’s CPI, and Nvidia’s earnings
CSFX View: Jackson Hole, Australia’s CPI, and Nvidia’s Earnings Set the Tone for the Week Ahead
The week of 24–29 August 2026 opens the Asian session with USD/JPY at 158.60, caught between building Bank of Japan hike bets after two straight months of hot inflation prints and the lingering deterrent of last month’s confirmed US-Japan intervention, while AUD/USD at 0.7160 holds firm heading into Wednesday’s July CPI, the week’s dominant scheduled catalyst with no RBA meeting on the calendar. Copper at $6.52/lb enters the week on a two-sided footing after LME inventories logged their largest weekly inflow since 2020, easing — though not eliminating — the structural supply squeeze that had driven prices for weeks, while the Hang Seng at 26,009 has rallied for a second straight session on AI and semiconductor strength ahead of Wednesday’s Nvidia earnings. In crypto, Litecoin at $42.95 has broken the rising trendline it defended through much of August, while XRP at $1.05 continues to defend the psychologically important $1.00 level with the CLARITY Act still shelved until at least 14 September.
Wednesday is the pivot point for the entire week: Australia’s CPI and Nvidia’s earnings land within hours of each other, before Thursday through Saturday’s Jackson Hole symposium — and Fed Chair Warsh’s first keynote as chair on Friday — take over as the dominant macro backdrop. USD/JPY’s path depends heavily on Friday’s Tokyo CPI and whether it reinforces the BOJ-hike narrative that has kept a lid on the pair. In commodities, copper’s easing supply squeeze argues for a more two-sided approach than the aggressive dip-buying seen in recent weeks. The Hang Seng’s AI-led rally should find out quickly, via Nvidia’s results, whether it can extend through the Jackson Hole window. In crypto, both XRP and Litecoin remain purely technical trades this week, with the sector’s next realistic legislative catalyst not arriving before the Senate reconvenes on 14 September.
CSFX’s key levels for the week: watch 156.50 support and 160.00 resistance on USD/JPY, 0.7080 support and 0.7250 resistance on AUD/USD ahead of Wednesday’s CPI, and $40.00 support on Litecoin following last week’s trendline break. Copper is a watch between $6.20 support and $6.75 resistance as the supply narrative recalibrates; the Hang Seng’s next test is 26,800 resistance pending Nvidia’s results, with 24,900 as the key support if sentiment sours; and XRP remains range-bound between $1.00 and $1.18. CSFX will issue intra-week alerts if Japanese or US authorities signal fresh intervention rhetoric, if Wednesday’s Australian CPI surprises materially in either direction, if Warsh’s Jackson Hole keynote reveals a sharper-than-expected policy signal, or if Litecoin fails to reclaim its broken trendline. Follow all updates at capitalstreetfx.com.
New clients can also take advantage of a limited-time deposit bonus when they open an account this week, on top of the usual account benefits — tight spreads, high leverage, and access to 2000+ instruments across FX, commodities, indices, and crypto. Full terms and other promotions are available on the CSFX website.
Trade Asian Markets at CSFX →