Oil Tops $97 as US-Iran Clashes Escalate | Technical Analysis | Asian Session | 7 Sep 2026
Oil Tops $97 as US-Iran Clashes Escalate While Asia Splits on Firming Fed Hike Bets
USD/JPY · AUD/USD · Copper · Corn · Hang Seng · Cardano · Litecoin — live Asian market outlook today, updated through the trading session
Asian Session Live News — Monday, 7 September 2026
The headlines moving Asian FX, equities, commodities and crypto right now
US Strikes Iranian Oil Tankers, Tehran Threatens Hormuz Exclusion Zone
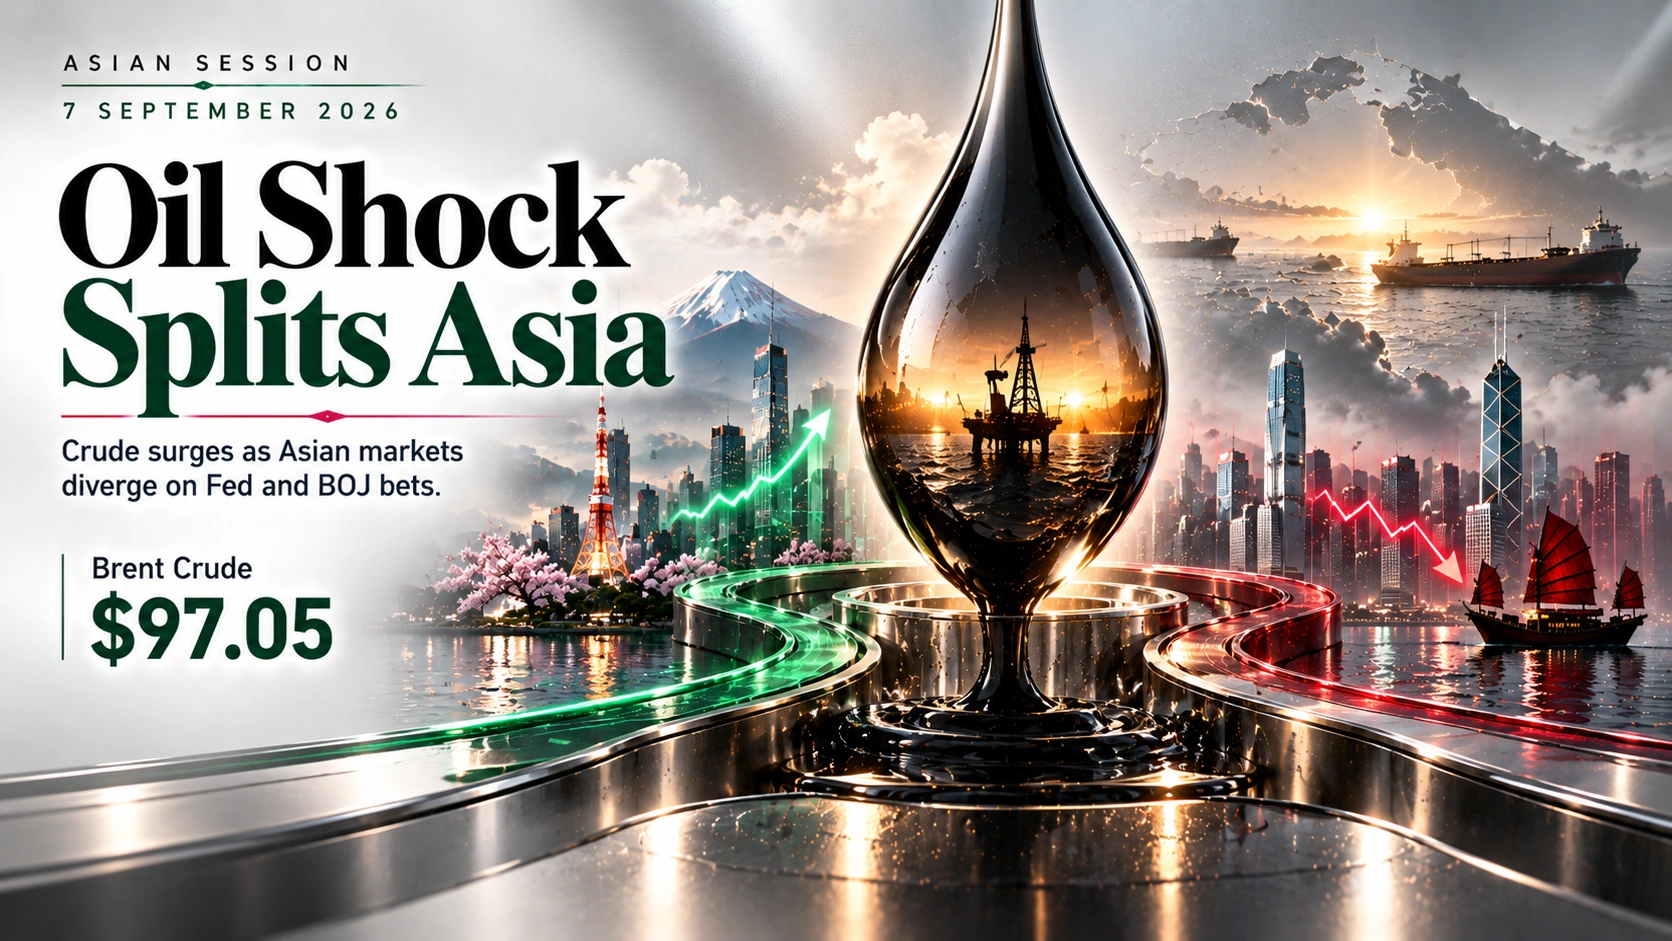
The US struck three Iranian oil tankers over the weekend in response to alleged ballistic-missile attacks on US Navy warships, prompting Iran to hit vessels linked to Washington and signal a “restricted” maritime zone beyond the Strait of Hormuz. Brent crude has jumped toward $97.05 a barrel, its highest level since July, extending last week’s near 9% surge.
GeopoliticsFed Hike Odds Stay Elevated After Friday’s Blowout Payrolls Beat
Futures markets are pricing a roughly 58-70% probability of a Federal Reserve rate hike at the September 16 meeting after August payrolls smashed expectations, keeping the 10-year Treasury yield pinned near 4.78-4.84%. Wall Street is closed for Labor Day, leaving Asian markets to lead price discovery on the repricing.
RatesHang Seng Slides Toward 25,428 as Tech Names and Rate Fears Bite
Hong Kong equities opened only marginally higher before reversing lower, with the Hang Seng Index down close to 0.9% near 25,428 after touching a two-week high on Friday. Xiaomi slid almost 4% while Bilibili and NetEase each dropped more than 2%, as investors weighed the hawkish US jobs data against domestic tech-sector jitters.
EquitiesNikkei Rallies 2% and Kospi Surges 3% as Asia Reads Jobs Data as Growth-Positive
Japan’s Nikkei 225 has rallied about 2% and South Korea’s Kospi has surged roughly 3%, with the small-cap Kosdaq up over 1%, as regional investors lean into a “good jobs data is good for growth” framing even as it narrows the odds on further Fed tightening. The broader MSCI Asia-Pacific ex-Japan index is up close to 0.9%.
EquitiesBOJ Hike Odds Climb to 75% for the September 18 Meeting
Markets are now pricing roughly a 75% probability that the Bank of Japan raises rates at its September 18 policy meeting, with a further 60% chance of another move by December, after board member Hajime Takata floated the prospect of outsized or back-to-back hikes. USD/JPY is holding a firm range near 156.20 as the hawkish BOJ offsets an equally hawkish Fed.
Central BanksCopper and Corn Hold Firm on Persistent Supply-Side Squeezes
Copper is trading near $6.65 a pound, supported by a Congo export ban and weaker output from Chile and Peru, while corn is holding close to three-year highs near $5.39 a bushel after the USDA trimmed its 2026 yield forecast. Both markets now look to Friday’s USDA crop production update for fresh direction.
CommoditiesLast refreshed during the Asian morning session, Monday 7 September 2026 · cross-checked against Reuters, Investing.com, Bloomberg and FXStreet
Asian Session Overview
“Asian shares rallied on Monday as the robust US jobs report was seen as positive for global growth even as it narrowed the odds on a rate hike.” — Reuters market wrap, cited by Yahoo Finance
Asian markets opened the week digesting two competing forces: a blowout US jobs report that has kept Federal Reserve Federal Reserve rate-hike odds elevated near 58-70% for the September 16 decision, and a sharp escalation in the US-Iran conflict that has sent oil prices surging. The 10-year Treasury yield is holding near 4.78-4.84%, its highest since late 2023, while Wall Street itself remains shut for the Labor Day holiday, leaving Asian trading desks to absorb Friday’s payrolls beat largely on their own. The reaction has been a “good news is good news” one across most of the region, with Japan’s Nikkei 225 up about 2% and South Korea’s Kospi surging roughly 3%, even as rising Bank of Japan hike odds, now near 75% for the September 18 meeting, keep the yen from weakening as much as the broader Dollar move might otherwise suggest.
Hong Kong has been the exception. The Hang Seng Index opened only marginally firmer before reversing to trade down close to 0.9% near 25,428, weighed by a near 4% slide in Xiaomi and losses of more than 2% in Bilibili and NetEase as investors balance the hawkish US data against domestic technology-sector jitters. Commodities are firmly in focus after the weekend’s exchange of strikes between the US and Iran: Brent crude has jumped toward $97.05 a barrel and WTI toward $92.20, both the highest since July, while copper near $6.65 a pound and corn near $5.39 a bushel are both riding separate, longer-running supply-side squeezes. In FX, USD/JPY is consolidating a firm 155.30-156.75 range as a hawkish Fed offsets a hawkish BOJ, and AUD/USD has climbed toward 0.7205 on the risk-on regional tone and elevated RBA tightening bets. Crypto majors Cardano and Litecoin are both extending double-digit weekly gains as the broader digital-asset market outperforms.
Asian Session Economic Calendar — 7 September 2026
Key releases and events shaping price action through the rest of the day
| Time | Event | Forecast / Detail | Impact | Market Read |
|---|---|---|---|---|
| 🇺🇸Weekend (Released) | US Strikes Three Iranian Oil Tankers; Iran Retaliates | Washington targets tankers after warships reportedly targeted; Tehran threatens a restricted zone beyond the Strait of Hormuz | 🔴 CRITICAL | Sent Brent toward $97.05/bbl and WTI toward $92.20/bbl, both the highest since July |
| 🇳🇰09:30 HKT (Ongoing) | Hang Seng Index Reverses Lower After a Firmer Open | Down close to 0.9% near 25,428 as Xiaomi slides almost 4% and Bilibili, NetEase drop over 2% | 🔴 CRITICAL | Domestic tech weakness compounds hawkish-Fed jitters, decoupling Hong Kong from the regional rally |
| 🇯🇵09:00 JST / KST (Ongoing) | Nikkei 225 and Kospi Rally on “Good News Is Good News” Framing | Nikkei 225 up roughly 2%, Kospi surging about 3%, Kosdaq up over 1% | 🔴 CRITICAL | Regional equities read the payrolls beat as a growth signal, shrugging off narrower Fed hike odds for now |
| 🇺🇸All Day | US Labor Day — Wall Street Closed | US equity and bond cash markets shut; futures trading only, thinning session liquidity | 🟢 MEDIUM | Leaves Asian desks to set the tone on Friday’s payrolls beat with less depth than usual |
| 🇯🇵Ongoing (Rates Market) | Bank of Japan September 18 Hike Odds Firm to 75% | BOJ board member Hajime Takata flags scope for outsized or back-to-back hikes; 60% odds of a further move by December | 🔴 CRITICAL | Keeps USD/JPY capped inside its 155.30-156.75 range even as the Dollar firms broadly |
| 🇺🇸Ongoing (Rates Market) | Fed September 16 Hike Odds Hold Near 58-70% | 10-year Treasury yield near 4.78-4.84%, its highest since late 2023, after Friday’s payrolls beat | 🔴 CRITICAL | Underpins the broad-Dollar bid against AUD, JPY and most Asian currencies into next week’s CPI |
| 🇨🇳Tuesday, 8 September | China August Trade Balance (Exports and Imports) | Markets watch for signs of resilient export demand despite tariff and geopolitical headwinds | 🟢 MEDIUM | A soft print would add to pressure on the Hang Seng and CSI 300 into midweek |
| 🇪🇺Thursday, 10 September | ECB Policy Meeting | A 25-basis-point hike is seen as a near certainty by markets | 🟢 MEDIUM | A hawkish tone would reinforce the global tightening narrative pressuring risk assets |
| 🇺🇸Friday, 11 September | US August CPI and USDA September Crop Production Report | Core CPI seen around +0.2-0.3% m/m; USDA to update its 2026 corn and soybean yield estimates | 🔴 CRITICAL | The decisive inputs for the Fed’s September 16 decision and for the corn trade heading into harvest |
Asian Session Trade Ideas — USD/JPY, Hang Seng, Cardano and More
Technical setups and fundamental context across the session’s seven key instruments
USD/JPY
Why This Setup
Elevated Fed hike odds near 58-70% for September 16 keep the broad-Dollar bid intact, but rising Bank of Japan hike odds, now near 75% for the September 18 meeting after board member Takata’s outsized-hike comments, are capping USD/JPY’s advance and keeping it inside a well-defined 155.30-156.75 range. A break of the range in either direction, likely triggered by this week’s BOJ rhetoric or Friday’s US CPI print, is the key risk to this setup.

AUD/USD
Why This Setup
The Aussie is riding the region’s broad risk-on tone, with the Nikkei up about 2% and the Kospi surging roughly 3%, alongside firm RBA rate-hike pricing after strong Australian GDP and trade data. That said, a firmer Dollar on elevated Fed hike odds and the fresh US-Iran escalation, which tends to pressure commodity-linked currencies when it spikes energy prices sharply, are the main sources of two-way risk into Friday’s US CPI report.

Copper
Why This Setup
A Congo export ban, weaker Chilean and Peruvian output and tariff-driven front-loading into US Comex warehouses are keeping physical copper tight even as macro headwinds, including this weekend’s oil-price spike, momentarily cap gains. The metal is holding most of its pullback from the August 25 record near $6.87, with China’s August trade data on Tuesday a near-term catalyst for the demand side of the story.

Corn
Why This Setup
The USDA has cut its 2026 US corn yield forecast to 180.7 bushels per acre, and the Pro Farmer Crop Tour flagged heat and disease damage across the Corn Belt, keeping the crop rated just 57% good-to-excellent. Friday’s updated USDA crop production report is the decisive near-term catalyst; reports that China is discussing fresh US agricultural purchases ahead of a possible Trump-Xi meeting are an additional source of two-way risk.

Hang Seng
Why This Setup
The index opened only marginally firmer before reversing as Xiaomi slid almost 4% and Bilibili and NetEase each dropped more than 2%, decoupling Hong Kong from the broader regional rally led by the Nikkei and Kospi. Elevated Fed hike odds are the genuine headwind behind the reversal, though a strong China trade data print on Tuesday or fresh policy support for the tech sector are real sources of two-way risk to the downside case.

Cardano
Why This Setup
ADA is extending a strong weekly rally, up roughly 14% and comfortably outperforming both the broader crypto market and similar smart-contract platforms, helped by governance progress including the ratification of Cardano’s 2026 Constitutional Committee. A broader risk-off move tied to the US-Iran escalation or renewed Fed-hike-driven Dollar strength are the main sources of two-way risk to this setup.

Litecoin
Why This Setup
Litecoin is riding the same broad-crypto tailwind lifting Cardano, extending a roughly 13% weekly advance as trading volumes pick up across major exchanges. The $44 area remains a well-tested support zone from earlier in the year, while a break above the $62 fifty-day moving average region would confirm the rebound; a risk-off shock from the US-Iran escalation is the main threat to the bullish case.

Asian Session FAQ — 7 September 2026
Quick answers to the questions traders are asking right now
Why are Asian equities rallying even as Fed hike odds stay elevated?
Why is the Hang Seng falling while the rest of Asia rallies?
What is driving oil prices sharply higher this morning?
Why are USD/JPY and AUD/USD moving in different directions from the Dollar Index?
What is the single biggest risk to today’s Asian-session trades?
Asian Session Summary — Monday, 7 September 2026 (Live Update)
Monday’s Asian session is being shaped by two forces pulling in different directions: a blowout US jobs report that has kept Federal Reserve rate-hike odds near 58-70% for the September 16 meeting, and a fresh escalation in the US-Iran conflict that has sent oil prices surging. The 10-year Treasury yield is holding near 4.78-4.84%, its highest since late 2023, while Wall Street remains closed for Labor Day, leaving Asian desks to set the tone. Brent crude has jumped toward $97.05 a barrel and WTI toward $92.20, both the highest since July, after the US struck three Iranian oil tankers over the weekend and Tehran threatened a restricted maritime zone beyond the Strait of Hormuz.
Regional equities have split sharply on the payrolls beat. Japan’s Nikkei 225 has rallied about 2% and South Korea’s Kospi has surged roughly 3% as investors lean into a growth-positive reading of the data, helped by Bank of Japan hike odds climbing to near 75% for the September 18 meeting. Hong Kong’s Hang Seng Index is the outlier, down close to 0.9% near 25,428 as a near 4% slide in Xiaomi and losses in Bilibili and NetEase compound the hawkish-Fed jitters. USD/JPY is consolidating a firm 155.30-156.75 range as the hawkish Fed and hawkish BOJ offset one another, while AUD/USD has climbed toward 0.7205 on the region’s broad risk-on tone. Copper near $6.65 a pound and corn near $5.39 a bushel are both holding firm on separate supply-side squeezes, and crypto majors Cardano and Litecoin are extending double-digit weekly gains as the broader digital-asset market outperforms.
Highest-conviction session idea: fade the Hang Seng’s failed bounce, selling rallies toward 25,650 while the rest of Asia extends its jobs-data-driven rally, while staying long the region’s broader risk-on tailwind via AUD/USD and the commodity complex, and staying alert to fast-moving US-Iran headlines that can reverse every one of these positions within minutes once fresh developments land.
For the individual instruments: USD/JPY buy dips toward 155.60, stop 155.00, target 157.20 — a hawkish Fed is a genuine tailwind, though rising BOJ hike odds are a real source of two-way risk. AUD/USD buy dips toward 0.7150, stop 0.7090, target 0.7280 — the region’s risk-on tone and firm RBA pricing are a genuine tailwind, though a firmer broad Dollar is a real source of two-way risk. Copper buy dips toward $6.50, stop $6.35, target $6.85 — persistent supply disruptions are a genuine tailwind, though the oil-driven macro headwind is a real source of two-way risk. Corn buy dips toward $5.20, stop $5.00, target $5.60 — tightening US supply is a genuine tailwind, though Friday’s USDA report is a real source of two-way risk. Hang Seng sell rallies toward 25,650, stop 25,900, target 24,950 — domestic tech weakness and hawkish-Fed jitters are a genuine tailwind for the downside case, though strong China trade data would be a real source of two-way risk. Cardano buy dips toward $0.208, stop $0.195, target $0.245 — strong governance-driven momentum is a genuine tailwind, though crypto’s sensitivity to risk-off shocks is a real source of two-way risk. Litecoin buy dips toward $51.50, stop $48.00, target $62.00 — broad crypto-market strength is a genuine tailwind, though the same risk-off sensitivity is a real source of two-way risk. The decisive variable for the rest of the day is whether the US-Iran conflict escalates further, and every position here should be sized with the knowledge that fast-moving Middle East headlines and the thin Labor Day liquidity can exaggerate moves in either direction.
Ready to act on today’s setups? Open an Account with Capital Street FX and trade every instrument covered in this report on our Zero Account’s 0.0 Pips Spreads and 1:10000 Leverage, across 2000+ Instruments, with a welcome deposit bonus and 24/7 Live Support on hand for every session.
Not sure which account fits your style? Compare our Account Types side by side with our Account Comparison tool, browse current Promotions / Bonus offers, and trade from our Trading Platform suite. Funding is simple via our Deposit & Withdrawal options. For ongoing coverage, explore our Forex Analysis Pages, Commodity Analysis Pages and Crypto Analysis Pages, plus our Daily Market Analysis and Weekly Market Analysis reports and the full Economic Calendar. New to trading? Visit our Trading Education / Blog, or reach our Contact Us / Live Support team any time.
Access Live Asian Markets →