Capital Street FX

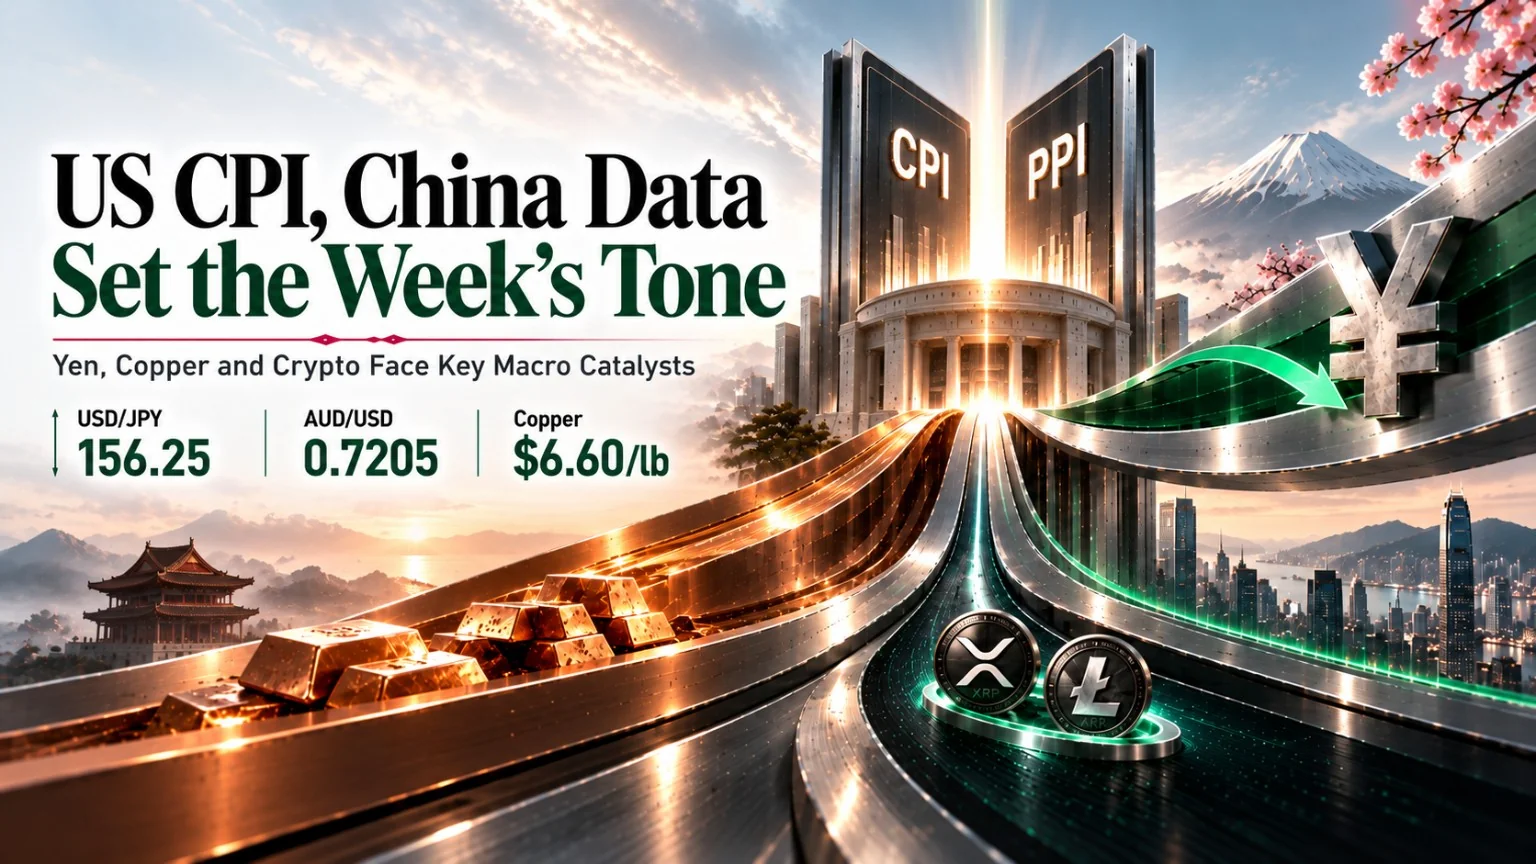
US CPI and China data set the week's tone as yen, copper and crypto face key macro catalysts

US CPI and China Data Set the Stage | Technical Analysis | Asian Session | 7 -12 Sep 2026

September 5, 2026
CSFXadmin
Week Ahead, 7–12 September: US CPI and China’s Data Deluge Set the Stage Ahead of the Fed, as the CLARITY Act Countdown and Australia’s Confidence Surveys Round Out the Asian Session Agenda | CSFX Asian Session Weekly
Asian Market Weekly Preview
Saturday 5 September 2026 · Week of 7–12 September 2026 · Full Asian Trading Week

Week Ahead, 7–12 September: US CPI and China’s Data Deluge Set the Stage Ahead of the Fed, as the CLARITY Act Countdown and Australia’s Confidence Surveys Round Out the Agenda

USD/JPY 156.25 · AUD/USD 0.7205 · Copper $6.60/lb · Hang Seng 25,651 · Litecoin $51.15 · XRP $1.45
China CPI & PPI Wed 9 Sep · Australia Confidence Data Tue 8 Sep · US PPI Thu 10 Sep, CPI Fri 11 Sep · CLARITY Act Senate Vote Countdown to 15 Sep · Full Asian session economic calendar for week of 7–12 September 2026
USD/JPY· AUD/USD· Copper· Hang Seng· Litecoin· XRP
📋 Upcoming Week at a Glance · 7–12 September 2026
China’s Inflation Data, US CPI, and a CLARITY Act Countdown Define the Asian Session This Week, 7–12 September
The week of 7–12 September 2026 opens with the Japanese yen fresh off its sharpest two-day rally since July’s confirmed US-Japan intervention, pulling USD/JPY down to around 156.25 even after Friday’s US payrolls report smashed expectations, as traders instead lean on rising Bank of Japan hike bets (63% priced for the 17–18 September meeting) to keep the pair capped. AUD/USD, at 0.7205, sits just off a four-year high with no Reserve Bank of Australia meeting on the calendar this week — the next is 28–29 September — leaving Tuesday’s Westpac Consumer Confidence and NAB Business Confidence surveys, alongside a speech from an RBA Assistant Governor, as the week’s domestic Aussie catalysts. The heavier lifting for copper and the Hang Seng comes from China, which publishes its August trade balance on Tuesday, CPI and PPI on Wednesday, and money supply data on Thursday — a data-dense stretch that will shape both the demand outlook for industrial metals and sentiment across Hong Kong’s tech-heavy index after a turbulent week that saw the Hang Seng slide to 24,960 before rebounding 1.74% on Friday. Overhanging the entire week is Thursday’s US Producer Price Index and Friday’s Consumer Price Index — the final inflation readings before the Federal Reserve’s 15–16 September meeting, where futures markets currently price a coin-flip-to-slightly-favoured quarter-point hike following Fed Chair Kevin Warsh’s hawkish Jackson Hole keynote. In crypto, XRP and Litecoin enter the week already sharply higher than a month ago, with XRP near $1.45 (up from an August low near $0.99) as traders position ahead of the Senate’s 15 September cloture vote on the CLARITY Act market-structure bill.
🇨🇳 China CPI & PPI Wed 9 Sep 🇦🇺 AU Confidence Data Tue 8 Sep 🇺🇸 US PPI Thu 10 Sep / CPI Fri 11 Sep 🏦 FOMC 15–16 Sep · BOJ 17–18 Sep ⚖️ CLARITY Act Cloture Vote 15 Sep
Section 1 · About the Asian Market This Week
Four threads carry into the Asian session this week, each tied to its own asset: a sharp yen rally testing USD/JPY’s downside ahead of the BOJ, at 156.25; a quiet RBA calendar leaving confidence data to drive AUD/USD (0.7205) just off four-year highs; a data-heavy week from China ($6.60/lb copper, 25,651 Hang Seng) that will set the tone for industrial demand and Hong Kong risk appetite; and a genuine catalyst finally arriving for XRP ($1.45) and Litecoin ($51.15) as the Senate’s CLARITY Act vote approaches.

1. USD/JPY — can the yen’s sharpest rally since July’s intervention hold into the BOJ and Fed decisions? USD/JPY tumbled to around 156.25 on Friday, capping its strongest weekly performance since Tokyo and Washington’s confirmed joint intervention in late July, even as Friday’s US payrolls report smashed forecasts (162K versus 56K expected). Traders have instead focused on rising odds of a Bank of Japan hike at the 17–18 September meeting, now priced near 63%, alongside speculation that Japanese authorities conducted a rate check ahead of possible fresh intervention. This week’s domestic docket — preliminary leading indicators Monday, then Q2 GDP’s final revision, wage, current account and Eco Watchers data Tuesday — is unlikely to move the pair as much as Friday’s US CPI print, the last major input before the Fed’s own 15–16 September decision.

2. AUD/USD — no RBA meeting this week Week Ahead, 7–12 September: US CPI and China’s Data Deluge Set the Stage Ahead of the Fed, as the CLARITY Act Countdown and Australia’s Confidence Surveys Round Out the Asian Session Agenda | CSFX Asian Session Weekly

Asian Market Weekly Preview
Saturday 5 September 2026 · Week of 7–12 September 2026 · Full Asian Trading Week

Week Ahead, 7–12 September: US CPI and China’s Data Deluge Set the Stage Ahead of the Fed, as the CLARITY Act Countdown and Australia’s Confidence Surveys Round Out the Agenda

USD/JPY 156.25 · AUD/USD 0.7205 · Copper $6.60/lb · Hang Seng 25,651 · Litecoin $51.15 · XRP $1.45
China CPI & PPI Wed 9 Sep · Australia Confidence Data Tue 8 Sep · US PPI Thu 10 Sep, CPI Fri 11 Sep · CLARITY Act Senate Vote Countdown to 15 Sep · Full Asian session economic calendar for week of 7–12 September 2026
USD/JPY· AUD/USD· Copper· Hang Seng· Litecoin· XRP
📋 Upcoming Week at a Glance · 7–12 September 2026
China’s Inflation Data, US CPI, and a CLARITY Act Countdown Define the Asian Session This Week, 7–12 September
The week of 7–12 September 2026 opens with the Japanese yen fresh off its sharpest two-day rally since July’s confirmed US-Japan intervention, pulling USD/JPY down to around 156.25 even after Friday’s US payrolls report smashed expectations, as traders instead lean on rising Bank of Japan hike bets (63% priced for the 17–18 September meeting) to keep the pair capped. AUD/USD, at 0.7205, sits just off a four-year high with no Reserve Bank of Australia meeting on the calendar this week — the next is 28–29 September — leaving Tuesday’s Westpac Consumer Confidence and NAB Business Confidence surveys, alongside a speech from an RBA Assistant Governor, as the week’s domestic Aussie catalysts. The heavier lifting for copper and the Hang Seng comes from China, which publishes its August trade balance on Tuesday, CPI and PPI on Wednesday, and money supply data on Thursday — a data-dense stretch that will shape both the demand outlook for industrial metals and sentiment across Hong Kong’s tech-heavy index after a turbulent week that saw the Hang Seng slide to 24,960 before rebounding 1.74% on Friday. Overhanging the entire week is Thursday’s US Producer Price Index and Friday’s Consumer Price Index — the final inflation readings before the Federal Reserve’s 15–16 September meeting, where futures markets currently price a coin-flip-to-slightly-favoured quarter-point hike following Fed Chair Kevin Warsh’s hawkish Jackson Hole keynote. In crypto, XRP and Litecoin enter the week already sharply higher than a month ago, with XRP near $1.45 (up from an August low near $0.99) as traders position ahead of the Senate’s 15 September cloture vote on the CLARITY Act market-structure bill.
🇨🇳 China CPI & PPI Wed 9 Sep 🇦🇺 AU Confidence Data Tue 8 Sep 🇺🇸 US PPI Thu 10 Sep / CPI Fri 11 Sep 🏦 FOMC 15–16 Sep · BOJ 17–18 Sep ⚖️ CLARITY Act Cloture Vote 15 Sep
Section 1 · About the Asian Market This Week
Four threads carry into the Asian session this week, each tied to its own asset: a sharp yen rally testing USD/JPY’s downside ahead of the BOJ, at 156.25; a quiet RBA calendar leaving confidence data to drive AUD/USD (0.7205) just off four-year highs; a data-heavy week from China ($6.60/lb copper, 25,651 Hang Seng) that will set the tone for industrial demand and Hong Kong risk appetite; and a genuine catalyst finally arriving for XRP ($1.45) and Litecoin ($51.15) as the Senate’s CLARITY Act vote approaches.

1. USD/JPY — can the yen’s sharpest rally since July’s intervention hold into the BOJ and Fed decisions? USD/JPY tumbled to around 156.25 on Friday, capping its strongest weekly performance since Tokyo and Washington’s confirmed joint intervention in late July, even as Friday’s US payrolls report smashed forecasts (162K versus 56K expected). Traders have instead focused on rising odds of a Bank of Japan hike at the 17–18 September meeting, now priced near 63%, alongside speculation that Japanese authorities conducted a rate check ahead of possible fresh intervention. This week’s domestic docket — preliminary leading indicators Monday, then Q2 GDP’s final revision, wage, current account and Eco Watchers data Tuesday — is unlikely to move the pair as much as Friday’s US CPI print, the last major input before the Fed’s own 15–16 September decision.

2. AUD/USD — no RBA meeting this week, but confidence data and China’s docket still matter. AUD/USD at 0.7205 sits just below its four-year high of 0.7280, having gained roughly 2.6% since its early-August low. With the Reserve Bank of Australia’s next meeting not until 28–29 September, Tuesday’s Westpac Consumer Confidence and NAB Business Confidence surveys — alongside a speech from an RBA Assistant Governor — are this week’s clearest domestic inputs, following a Q2 GDP print (0.4% quarter-on-quarter, 2.1% year-on-year) that beat forecasts and pushed the market-implied odds of a September hike toward 66%. China’s trade, inflation and money-supply data this week are arguably just as important for the Aussie given the currency’s sensitivity to Chinese demand.

3. Copper and the Hang Seng — a data-heavy week from China is the clearest test of demand. Copper at $6.60/lb sits just below its August 2026 record high, up nearly 48% year-on-year, with China’s August trade balance (Tuesday), CPI and PPI (Wednesday), and money supply figures (Thursday) the week’s key demand-side signals. The Hang Seng, at 25,651, endured a rocky week — sliding as low as 24,960 amid a weak Hong Kong trading debut for Shein and renewed China property weakness — before rebounding 1.74% on Friday as global tech shares rallied and near-term Fed hike bets eased. China’s inflation data and the ongoing digestion of Nvidia’s late-August earnings both remain live inputs for Hong Kong’s AI and chip-linked complex.

4. XRP and Litecoin — a genuine catalyst arrives as the CLARITY Act vote approaches. Unlike recent weeks, XRP at $1.45 and Litecoin at $51.15 now have a concrete event to trade into: the Senate’s cloture vote on the CLARITY Act market-structure bill, scheduled for 15 September, just after this window closes. XRP has rallied more than 40% from its 17 August low near $0.99 on that anticipation, with SEC Chair Paul Atkins signalling he expects the Senate to advance the bill, even as prediction markets still assign the vote’s success only modest odds.

USD/JPY
156.25
▼ Sharpest yen rally since July intervention
US CPI Friday is the week’s key swing factor
AUD/USD
0.7205
▲ Just off a four-year high
No RBA meeting · Confidence data Tuesday
Copper (COMEX)
$6.60/lb
■ Near record highs, +48% YoY
China trade, CPI & PPI data Tue–Wed key to demand
Hang Seng Index
25,651
▲ Rebounded 1.74% into the weekend
Recovered from a 24,960 mid-week low
Litecoin (LTC)
$51.15
▲ Recovering with broader crypto risk mood
CLARITY Act vote Monday-after-next in view
XRP
$1.45
▲ Up over 40% since 17 August low
CLARITY Act Senate cloture vote set for 15 Sep
Section 2 · What Moves Markets This Week

Three Forces That Will Drive the Asian Session — 7 to 12 September 2026

The scheduled Asian-session catalysts that will set the direction across FX, commodities, equities, and digital assets for the week of 7–12 September 2026

🇺🇸
Force 1 · US PPI and CPI Are the Final Readings Before a Coin-Flip Fed Decision
Thursday’s Producer Price Index and Friday’s Consumer Price Index for August are the last major US inflation data points before the Federal Reserve’s 15–16 September meeting. Futures markets currently price roughly a 55–64% chance of a quarter-point hike, up sharply from about a third before Fed Chair Kevin Warsh’s hawkish Jackson Hole keynote, and reinforced by an August payrolls report that nearly tripled expectations. Both releases land after the Asian close, but the reaction carries directly into Friday and Monday’s regional open.
🇨🇳
Force 2 · China’s Trade, CPI and PPI Data Are the Week’s Clearest Test for Copper and the Hang Seng
China publishes its August trade balance on Tuesday, followed by CPI and PPI on Wednesday and money-supply figures on Thursday. Economists expect CPI to rebound to around 0.9% year-on-year on firmer food prices and PPI to extend its recovery to around 3.2%, though high-frequency data suggests the improvement remains more price-driven than demand-driven — a distinction that matters for whether copper’s near-record prices and the Hang Seng’s tech-led rebound can be sustained.
⚖️
Force 3 · XRP and Litecoin’s CLARITY Act Countdown Builds Toward 15 September
The Senate’s cloture vote on the CLARITY Act — the market-structure bill that would classify XRP as a commodity — is scheduled for 15 September, just after this window closes, but positioning is already building through the week ahead of it. The vote needs 60 votes to advance, meaning Republicans’ 53 seats require Democratic support; SEC Chair Paul Atkins has said he expects and hopes the Senate will advance the bill, while prediction markets still price the odds of full passage this year in the teens to low twenties.

Section 3 · Key Levels to Watch

Asian Session Weekly Levels & Bias

Six instrument-specific reference levels for the week of 7–12 September 2026. All levels for reference and informational purposes only; not financial advice. Visit capitalstreetfx.com for live signals and other markets.

USD/JPY
156.25
▼ Testing whether renewed BOJ hike bets extend the yen’s rally
▼ CAUTIOUS / WATCH 155.00 SUPPORT, 158.50 RESISTANCE
Support
155.00
Pivot
156.25
Resistance
158.50

What to Watch — Friday’s US CPI Is the Week’s Key Swing Factor

USD/JPY posted its sharpest two-day rally in the yen’s favour since July’s confirmed US-Japan intervention, with traders speculating that Japanese authorities may have conducted a rate check ahead of possible fresh action. That move held even through Friday’s blowout US payrolls report, underscoring how firmly rising Bank of Japan hike bets (63% priced for 17–18 September) are anchoring the pair. Friday’s US CPI print is the week’s clearest swing factor: a hot reading would likely reinforce Fed hike bets and offer the dollar some support, while a soft surprise could extend the yen’s advance toward the 155.00 area ahead of next week’s Fed and BOJ decisions.

usdjpy weekly chart
Chart by TradingView
AUD/USD
0.7205
▲ Consolidating just below a four-year high
▲ CONSTRUCTIVE / WATCH 0.7280 RESISTANCE, 0.7125 SUPPORT
Support
0.7125
Pivot
0.7205
Resistance
0.7280

What to Watch — Confidence Data Fills the Gap Left by an Empty RBA Calendar

With the Reserve Bank of Australia’s next decision not due until 28–29 September, Tuesday’s Westpac Consumer Confidence and NAB Business Confidence surveys are this week’s clearest domestic reference points for AUD/USD, alongside a scheduled speech from an RBA Assistant Governor. The pair enters the week supported by a stronger-than-expected Q2 GDP print and market pricing of roughly a 66% chance of a September hike. China’s trade, CPI and PPI data in the middle of the week are a secondary but meaningful driver given the Aussie’s sensitivity to Chinese demand.

audusd weekly chart
Chart by TradingView
Copper (COMEX)
$6.60/lb
■ Consolidating just below record highs
■ NEUTRAL / WATCH $6.83 RESISTANCE, $6.20 SUPPORT
Support
$6.20
Pivot
$6.60
Resistance
$6.83

What to Watch — China’s Inflation Data Is the Clearest Read on Demand

Copper is trading just below its August 2026 record high and remains up nearly 48% year-on-year, but the past month has seen prices ease slightly as markets digest whether the rally has run ahead of physical fundamentals. Wednesday’s China CPI and PPI prints, alongside Tuesday’s trade balance, are this week’s clearest signals on whether the recent upstream price recovery reflects genuine demand strength or remains largely price-driven — a distinction CSFX sees as central to whether copper can sustain a push toward its recent highs.

copper weekly chart
Chart by TradingView
Hang Seng Index
25,651
▲ Rebounded off a volatile mid-week low
▲ CONSTRUCTIVE / WATCH 26,000 RESISTANCE, 24,900 SUPPORT
Support
24,900
Pivot
25,651
Resistance
26,000

What to Watch — China’s Data Docket Meets a Fragile Risk-On Mood

The index slid to as low as 24,960 mid-week as a weak Hong Kong trading debut for Shein and renewed China property weakness weighed on sentiment, before rebounding 1.74% on Friday as global technology shares rallied and near-term Fed hike bets eased on dovish comments from a Fed governor. China’s trade, CPI and PPI data this week are the clearest tests of whether that rebound has genuine legs, alongside the ongoing digestion of Nvidia’s late-August earnings across Hong Kong’s AI and semiconductor-linked names.

hangseng weekly chart
Chart by TradingView
Litecoin (LTC)
$51.15
▲ Recovering with the broader crypto risk mood
▲ CONSTRUCTIVE / WATCH $58.00 RESISTANCE, $45.00 SUPPORT
Support
$45.00
Pivot
$51.15
Resistance
$58.00

What to Watch — Broader Crypto Sentiment Ahead of the CLARITY Act Vote

LTC has climbed roughly 15% over the past month, tracking a broader improvement in crypto risk appetite as XRP’s rally ahead of the CLARITY Act vote lifts sentiment across altcoins. Without a token-specific catalyst of its own this week, CSFX sees Litecoin largely trading as a beta play on that broader mood; the $45.00 area is the level to watch for signs of the recovery losing steam, while a push through $58.00 would put the token back within range of its recent highs.

litecoin weekly chart
Chart by TradingView
XRP
$1.45
▲ Up over 40% from its 17 August low
▲ CONSTRUCTIVE / WATCH $1.55 RESISTANCE, $1.35 SUPPORT
Support
$1.35
Pivot
$1.45
Resistance
$1.55

What to Watch — Positioning Builds Ahead of the 15 September Cloture Vote

XRP has rallied sharply from its 17 August cycle low near $0.99 as traders price in rising odds that the Senate advances the CLARITY Act, with SEC Chair Paul Atkins publicly saying he expects the chamber to move the bill forward. The $1.55 zone capped the token for roughly seven months and is the clearest technical ceiling this week; a hold above the $1.35 support area keeps the bullish structure intact, while prediction markets’ still-modest odds on the vote’s ultimate success (in the teens to low twenties) leave real two-way risk into 15 September.


Section 4 · Key Catalysts

What Could Move Asian Markets Sharply This Week

The scheduled and unscheduled events that CSFX is watching most closely for the Asian session, 7–12 September 2026

MACRO
US PPI (Thursday) & CPI (Friday) — Final Data Before the Fed
The Bureau of Labor Statistics releases August PPI on Thursday and CPI on Friday, both at 8:30am ET (evening HKT). These are the last major inflation readings before the Fed’s 15–16 September decision, where futures currently price roughly a coin-flip-to-slightly-favoured quarter-point hike after Chair Warsh’s hawkish Jackson Hole keynote and a blowout August jobs report.
MACRO
China Trade Balance, CPI, PPI & Money Supply — Tuesday–Thursday
China’s August trade balance lands Tuesday, followed by CPI and PPI Wednesday and M0/M1/M2 money supply Thursday. Economists expect CPI to rebound toward 0.9% year-on-year on firmer food prices, with PPI extending its recovery to around 3.2% — a data-dense stretch central to the demand outlook for copper and sentiment across the Hang Seng.
CENTRAL BANK
Australia Confidence Data & RBA Speech — Tuesday, 8 September
Westpac Consumer Confidence (10:30am AEST) and NAB Business Confidence (11:30am AEST) are released Tuesday, alongside a speech from an RBA Assistant Governor in the evening. With no RBA meeting until 28–29 September, these are the week’s clearest domestic gauges for AUD/USD following a stronger-than-expected Q2 GDP print.
FX
Japan Data Docket — Monday & Tuesday
Monday brings Japan’s preliminary Coincident and Leading Economic Indexes alongside foreign exchange reserves; Tuesday adds the final revision to Q2 GDP, Average Cash Earnings, the Current Account balance, Bank Lending data, and the Eco Watchers Survey. None carries the weight of Friday’s US CPI, but together they add context to the ongoing BOJ hike debate ahead of the 17–18 September meeting.
CRYPTO / POLICY
CLARITY Act Cloture Vote Countdown — Building Toward 15 September
The Senate’s cloture vote on the CLARITY Act market-structure bill is scheduled for 15 September, just after this window closes, requiring 60 votes with Republicans holding 53 seats. SEC Chair Paul Atkins has said he expects and hopes the Senate will advance the bill, and positioning in XRP and, to a lesser extent, Litecoin is likely to keep building through the week ahead of it.
GEOPOLITICS
Middle East Tensions & Oil Prices — Ongoing
Renewed flare-ups in the Iran conflict pushed oil prices higher and briefly rattled Asian equities in the past two weeks, adding an inflation-risk premium that feeds directly into the Fed’s calculus ahead of its September meeting. CSFX is watching for any fresh escalation that could revive the risk-off, inflation-fear dynamic seen earlier this month.

Section 5 · Economic Calendar

Asian Session — Economic Calendar, 7–12 September 2026

All times approximate, Hong Kong Time (HKT, UTC+8) unless noted. Key releases for USD/JPY, AUD/USD, Copper, Hang Seng, Litecoin, and XRP.

Day Time (HKT) Release Impact Forecast CSFX View
Monday, 7 September
Mon~07:50 HKT Japan Preliminary Coincident & Leading Economic Indexes (July) LOWN/A Background context for the BOJ hike debate rather than a standalone catalyst; released alongside Japan’s FX reserves figures.
Tuesday, 8 September
Tue~08:30 HKT Australia Westpac Consumer Confidence (September) MEDN/A The week’s first read on how households are digesting resilient GDP data and rising RBA hike bets ahead of the 29 September decision.
Tue~09:30 HKT Australia NAB Business Confidence (August) MEDN/A A key gauge of how firms are pricing rising cost pressures through to consumers; watched closely given the empty RBA calendar this week.
Tue~07:30 HKT Japan Final Q2 GDP, Average Cash Earnings, Current Account & Bank Lending MEDN/A A bundle of secondary Japanese data adding context to the yen’s sharp rally and the ongoing BOJ tightening debate.
TueAll Day China Trade Balance & Import/Export YoY (August) HIGHN/A The week’s first major China data point, setting the tone ahead of Wednesday’s inflation prints for both copper and the Hang Seng.
Wednesday, 9 September
Wed~09:30 HKT China CPI & PPI (August) HIGHCPI ~0.9% YoY / PPI ~3.2% YoY The week’s single most important China release; a firm PPI print in particular would support the case that copper’s near-record prices are demand-justified.
Thursday, 10 September
ThuAll Day China M0/M1/M2 Money Supply (August) MEDN/A A secondary gauge of credit and liquidity conditions relevant to the broader China demand narrative for copper.
Thu~20:30 HKT US Producer Price Index (August) HIGHN/A Lands after the Asian close but sets the tone into Friday’s Asia open ahead of the CPI print and the following week’s FOMC decision.
Friday, 11 September
Fri~06:30 HKT New Zealand BusinessNZ Manufacturing PMI (August) LOWN/A A minor regional data point with limited spillover into the week’s major instruments.
Fri~20:30 HKT US Consumer Price Index (August) HIGHN/A The week’s single most important release overall; the last major inflation print before the Fed’s 15–16 September meeting, landing after the Asian close with the fullest reaction likely carrying into Monday’s open.
Saturday, 12 September
SatAll Day No Scheduled Asian Session Releases LOWN/A A quiet close to the week as markets digest Friday’s US CPI print and position ahead of the FOMC (15–16 Sep), the CLARITY Act vote (15 Sep) and the BOJ meeting (17–18 Sep).

Section 6 · FAQ

Asian Session — Trader Questions Answered

Key questions from CSFX clients ahead of US CPI, China’s data deluge, and the CLARITY Act vote

Why does this week’s US CPI matter so much if the FOMC decision isn’t until the following week?
Because it’s the last significant inflation data point the Fed will see before it meets on 15–16 September. Markets currently price roughly a coin-flip-to-slightly-favoured chance of a quarter-point hike, up from about a third before Fed Chair Kevin Warsh’s hawkish Jackson Hole keynote, and that pricing has already proven sensitive to incoming data — Friday’s blowout payrolls report reinforced the hawkish case, while dovish comments from a Fed governor pulled the odds back down earlier in the week. A hot CPI print would likely push hike odds higher still, while a soft one could tip the balance back toward a hold.
Why is USD/JPY falling even after a much stronger-than-expected US jobs report?
Because the yen side of the equation has been moving just as forcefully. USD/JPY posted its sharpest two-day rally in the yen’s favour since July’s confirmed intervention, with traders speculating that Japanese authorities may have conducted a rate check ahead of possible fresh action, layered on top of rising odds (63% priced) of a Bank of Japan hike at the 17–18 September meeting. That yen strength has so far offset the dollar’s positive reaction to Friday’s payrolls beat.
Why does China’s data week matter so much for copper and the Hang Seng specifically?
Because China is both the world’s largest copper consumer and the key swing factor for sentiment in Hong Kong-listed equities. Wednesday’s CPI and PPI prints, alongside Tuesday’s trade balance and Thursday’s money supply data, are the clearest available signals this week on whether China’s recent price recovery reflects genuine demand strength or remains largely driven by upstream input costs — a distinction that matters for whether copper’s near-record prices and the Hang Seng’s fragile rebound can hold.
With no RBA meeting this week, what should AUD/USD traders actually watch?
Tuesday’s Westpac Consumer Confidence and NAB Business Confidence surveys are the clearest domestic reference points, alongside a scheduled speech from an RBA Assistant Governor. The pair enters the week supported by a stronger-than-expected Q2 GDP print and market pricing of roughly a 66% chance of a hike at the RBA’s 28–29 September meeting, but China’s trade and inflation data in the middle of the week are arguably just as relevant given the Aussie’s sensitivity to Chinese demand.
What’s driving XRP and Litecoin’s rally, and how does the CLARITY Act vote change the calculus?
XRP has climbed more than 40% from its 17 August low as traders position ahead of the Senate’s 15 September cloture vote on the CLARITY Act, the bill that would classify XRP as a commodity under federal law. The vote needs 60 votes to advance, meaning Republicans’ 53 seats require Democratic support, and SEC Chair Paul Atkins has publicly said he expects the Senate to move the bill forward — though prediction markets still price the odds of the bill’s ultimate passage this year only in the teens to low twenties, leaving genuine two-way risk. Litecoin has largely tracked that improving sentiment as a broader crypto beta play rather than moving on any catalyst of its own.
Is Middle East geopolitical risk still a factor for Asian markets this week?
Yes, at the margin. Renewed flare-ups in the Iran conflict have pushed oil prices higher and briefly weighed on Asian equities in recent weeks, adding an inflation-risk premium that feeds into the Fed’s calculus ahead of its September meeting. CSFX is not treating this as a headline instrument this week, but any fresh escalation could quickly revive the risk-off, inflation-fear dynamic seen earlier in the month and spill over into both the Hang Seng and the yen’s safe-haven flows.
CSFX View · Week of 7 September 2026

CSFX View: China’s Data Deluge, US CPI, and a CLARITY Act Countdown Set the Tone for the Week Ahead


The week of 7–12 September 2026 opens the Asian session with USD/JPY at 156.25, still digesting the sharpest yen rally since July’s confirmed intervention even after a blowout US payrolls print, while AUD/USD at 0.7205 holds just below a four-year high with no RBA meeting to compete for attention until 28–29 September, leaving Tuesday’s confidence surveys as the week’s clearest domestic Aussie catalyst. Copper at $6.60/lb sits just below its August record as China’s trade balance, CPI and PPI data (Tuesday–Wednesday) test whether the recent price recovery is demand-led, while the Hang Seng at 25,651 enters the week rebuilding confidence after a volatile stretch that saw it slide to 24,960 before Friday’s 1.74% rebound. In crypto, XRP at $1.45 and Litecoin at $51.15 both trade meaningfully higher than a month ago as the Senate’s 15 September CLARITY Act cloture vote comes into view.

Thursday and Friday are the pivot points for the entire week: US PPI and CPI land in quick succession, the final inflation readings before the Fed’s 15–16 September decision, where futures currently price a coin-flip-to-slightly-favoured quarter-point hike. China’s Tuesday-through-Thursday data run is the parallel storyline for copper and the Hang Seng, testing whether the recent price recovery in industrial metals reflects genuine demand strength. AUD/USD’s path leans on confidence data and China’s docket in the absence of a live RBA meeting, while USD/JPY’s fate hinges on whether Friday’s CPI print reinforces or unwinds the yen’s sharp recent rally ahead of next week’s BOJ decision. In crypto, both XRP and Litecoin now have a concrete event to trade into for the first time in weeks, even if the CLARITY Act’s ultimate fate remains genuinely uncertain.

CSFX’s key levels for the week: watch 155.00 support and 158.50 resistance on USD/JPY, 0.7125 support and 0.7280 resistance on AUD/USD, and $1.35 support on XRP heading into the CLARITY Act vote. Copper is a watch between $6.20 support and $6.83 resistance as China’s data clarifies the demand picture; the Hang Seng’s next test is 26,000 resistance, with 24,900 as the key support if this week’s rebound fades; and Litecoin remains a broader crypto-sentiment play between $45.00 support and $58.00 resistance. CSFX will issue intra-week alerts if Japanese authorities signal fresh intervention, if China’s inflation data surprises materially in either direction, if Thursday’s or Friday’s US inflation prints move Fed hike odds sharply, or if the CLARITY Act’s Senate prospects shift meaningfully ahead of the 15 September vote. Follow all updates at capitalstreetfx.com.

New clients can also take advantage of a limited-time deposit bonus when they open an account this week, on top of the usual account benefits — tight spreads, high leverage, and access to 2000+ instruments across FX, commodities, indices, and crypto. Full terms and other promotions are available on the CSFX website.

Trade Asian Markets at CSFX →
, but confidence data and China’s docket still matter.
AUD/USD at 0.7205 sits just below its four-year high of 0.7280, having gained roughly 2.6% since its early-August low. With the Reserve Bank of Australia’s next meeting not until 28–29 September, Tuesday’s Westpac Consumer Confidence and NAB Business Confidence surveys — alongside a speech from an RBA Assistant Governor — are this week’s clearest domestic inputs, following a Q2 GDP print (0.4% quarter-on-quarter, 2.1% year-on-year) that beat forecasts and pushed the market-implied odds of a September hike toward 66%. China’s trade, inflation and money-supply data this week are arguably just as important for the Aussie given the currency’s sensitivity to Chinese demand.

3. Copper and the Hang Seng — a data-heavy week from China is the clearest test of demand. Copper at $6.60/lb sits just below its August 2026 record high, up nearly 48% year-on-year, with China’s August trade balance (Tuesday), CPI and PPI (Wednesday), and money supply figures (Thursday) the week’s key demand-side signals. The Hang Seng, at 25,651, endured a rocky week — sliding as low as 24,960 amid a weak Hong Kong trading debut for Shein and renewed China property weakness — before rebounding 1.74% on Friday as global tech shares rallied and near-term Fed hike bets eased. China’s inflation data and the ongoing digestion of Nvidia’s late-August earnings both remain live inputs for Hong Kong’s AI and chip-linked complex.

4. XRP and Litecoin — a genuine catalyst arrives as the CLARITY Act vote approaches. Unlike recent weeks, XRP at $1.45 and Litecoin at $51.15 now have a concrete event to trade into: the Senate’s cloture vote on the CLARITY Act market-structure bill, scheduled for 15 September, just after this window closes. XRP has rallied more than 40% from its 17 August low near $0.99 on that anticipation, with SEC Chair Paul Atkins signalling he expects the Senate to advance the bill, even as prediction markets still assign the vote’s success only modest odds.

USD/JPY
156.25
▼ Sharpest yen rally since July intervention
US CPI Friday is the week’s key swing factor
AUD/USD
0.7205
▲ Just off a four-year high
No RBA meeting · Confidence data Tuesday
Copper (COMEX)
$6.60/lb
■ Near record highs, +48% YoY
China trade, CPI & PPI data Tue–Wed key to demand
Hang Seng Index
25,651
▲ Rebounded 1.74% into the weekend
Recovered from a 24,960 mid-week low
Litecoin (LTC)
$51.15
▲ Recovering with broader crypto risk mood
CLARITY Act vote Monday-after-next in view
XRP
$1.45
▲ Up over 40% since 17 August low
CLARITY Act Senate cloture vote set for 15 Sep
Section 2 · What Moves Markets This Week

Three Forces That Will Drive the Asian Session — 7 to 12 September 2026

The scheduled Asian-session catalysts that will set the direction across FX, commodities, equities, and digital assets for the week of 7–12 September 2026

🇺🇸
Force 1 · US PPI and CPI Are the Final Readings Before a Coin-Flip Fed Decision
Thursday’s Producer Price Index and Friday’s Consumer Price Index for August are the last major US inflation data points before the Federal Reserve’s 15–16 September meeting. Futures markets currently price roughly a 55–64% chance of a quarter-point hike, up sharply from about a third before Fed Chair Kevin Warsh’s hawkish Jackson Hole keynote, and reinforced by an August payrolls report that nearly tripled expectations. Both releases land after the Asian close, but the reaction carries directly into Friday and Monday’s regional open.
🇨🇳
Force 2 · China’s Trade, CPI and PPI Data Are the Week’s Clearest Test for Copper and the Hang Seng
China publishes its August trade balance on Tuesday, followed by CPI and PPI on Wednesday and money-supply figures on Thursday. Economists expect CPI to rebound to around 0.9% year-on-year on firmer food prices and PPI to extend its recovery to around 3.2%, though high-frequency data suggests the improvement remains more price-driven than demand-driven — a distinction that matters for whether copper’s near-record prices and the Hang Seng’s tech-led rebound can be sustained.
⚖️
Force 3 · XRP and Litecoin’s CLARITY Act Countdown Builds Toward 15 September
The Senate’s cloture vote on the CLARITY Act — the market-structure bill that would classify XRP as a commodity — is scheduled for 15 September, just after this window closes, but positioning is already building through the week ahead of it. The vote needs 60 votes to advance, meaning Republicans’ 53 seats require Democratic support; SEC Chair Paul Atkins has said he expects and hopes the Senate will advance the bill, while prediction markets still price the odds of full passage this year in the teens to low twenties.

Section 3 · Key Levels to Watch

Asian Session Weekly Levels & Bias

Six instrument-specific reference levels for the week of 7–12 September 2026. All levels for reference and informational purposes only; not financial advice. Visit capitalstreetfx.com for live signals and other markets.

USD/JPY
156.25
▼ Testing whether renewed BOJ hike bets extend the yen’s rally
▼ CAUTIOUS / WATCH 155.00 SUPPORT, 158.50 RESISTANCE
Support
155.00
Pivot
156.25
Resistance
158.50

What to Watch — Friday’s US CPI Is the Week’s Key Swing Factor

USD/JPY posted its sharpest two-day rally in the yen’s favour since July’s confirmed US-Japan intervention, with traders speculating that Japanese authorities may have conducted a rate check ahead of possible fresh action. That move held even through Friday’s blowout US payrolls report, underscoring how firmly rising Bank of Japan hike bets (63% priced for 17–18 September) are anchoring the pair. Friday’s US CPI print is the week’s clearest swing factor: a hot reading would likely reinforce Fed hike bets and offer the dollar some support, while a soft surprise could extend the yen’s advance toward the 155.00 area ahead of next week’s Fed and BOJ decisions.

usdjpy weekly chart
Chart by TradingView
AUD/USD
0.7205
▲ Consolidating just below a four-year high
▲ CONSTRUCTIVE / WATCH 0.7280 RESISTANCE, 0.7125 SUPPORT
Support
0.7125
Pivot
0.7205
Resistance
0.7280

What to Watch — Confidence Data Fills the Gap Left by an Empty RBA Calendar

With the Reserve Bank of Australia’s next decision not due until 28–29 September, Tuesday’s Westpac Consumer Confidence and NAB Business Confidence surveys are this week’s clearest domestic reference points for AUD/USD, alongside a scheduled speech from an RBA Assistant Governor. The pair enters the week supported by a stronger-than-expected Q2 GDP print and market pricing of roughly a 66% chance of a September hike. China’s trade, CPI and PPI data in the middle of the week are a secondary but meaningful driver given the Aussie’s sensitivity to Chinese demand.

audusd weekly chart
Chart by TradingView
Copper (COMEX)
$6.60/lb
■ Consolidating just below record highs
■ NEUTRAL / WATCH $6.83 RESISTANCE, $6.20 SUPPORT
Support
$6.20
Pivot
$6.60
Resistance
$6.83

What to Watch — China’s Inflation Data Is the Clearest Read on Demand

Copper is trading just below its August 2026 record high and remains up nearly 48% year-on-year, but the past month has seen prices ease slightly as markets digest whether the rally has run ahead of physical fundamentals. Wednesday’s China CPI and PPI prints, alongside Tuesday’s trade balance, are this week’s clearest signals on whether the recent upstream price recovery reflects genuine demand strength or remains largely price-driven — a distinction CSFX sees as central to whether copper can sustain a push toward its recent highs.

copper weekly chart
Chart by TradingView
Hang Seng Index
25,651
▲ Rebounded off a volatile mid-week low
▲ CONSTRUCTIVE / WATCH 26,000 RESISTANCE, 24,900 SUPPORT
Support
24,900
Pivot
25,651
Resistance
26,000

What to Watch — China’s Data Docket Meets a Fragile Risk-On Mood

The index slid to as low as 24,960 mid-week as a weak Hong Kong trading debut for Shein and renewed China property weakness weighed on sentiment, before rebounding 1.74% on Friday as global technology shares rallied and near-term Fed hike bets eased on dovish comments from a Fed governor. China’s trade, CPI and PPI data this week are the clearest tests of whether that rebound has genuine legs, alongside the ongoing digestion of Nvidia’s late-August earnings across Hong Kong’s AI and semiconductor-linked names.

hangseng weekly chart
Chart by TradingView
Litecoin (LTC)
$51.15
▲ Recovering with the broader crypto risk mood
▲ CONSTRUCTIVE / WATCH $58.00 RESISTANCE, $45.00 SUPPORT
Support
$45.00
Pivot
$51.15
Resistance
$58.00

What to Watch — Broader Crypto Sentiment Ahead of the CLARITY Act Vote

LTC has climbed roughly 15% over the past month, tracking a broader improvement in crypto risk appetite as XRP’s rally ahead of the CLARITY Act vote lifts sentiment across altcoins. Without a token-specific catalyst of its own this week, CSFX sees Litecoin largely trading as a beta play on that broader mood; the $45.00 area is the level to watch for signs of the recovery losing steam, while a push through $58.00 would put the token back within range of its recent highs.

litecoin weekly chart
Chart by TradingView
XRP
$1.45
▲ Up over 40% from its 17 August low
▲ CONSTRUCTIVE / WATCH $1.55 RESISTANCE, $1.35 SUPPORT
Support
$1.35
Pivot
$1.45
Resistance
$1.55

What to Watch — Positioning Builds Ahead of the 15 September Cloture Vote

XRP has rallied sharply from its 17 August cycle low near $0.99 as traders price in rising odds that the Senate advances the CLARITY Act, with SEC Chair Paul Atkins publicly saying he expects the chamber to move the bill forward. The $1.55 zone capped the token for roughly seven months and is the clearest technical ceiling this week; a hold above the $1.35 support area keeps the bullish structure intact, while prediction markets’ still-modest odds on the vote’s ultimate success (in the teens to low twenties) leave real two-way risk into 15 September.


Section 4 · Key Catalysts

What Could Move Asian Markets Sharply This Week

The scheduled and unscheduled events that CSFX is watching most closely for the Asian session, 7–12 September 2026

MACRO
US PPI (Thursday) & CPI (Friday) — Final Data Before the Fed
The Bureau of Labor Statistics releases August PPI on Thursday and CPI on Friday, both at 8:30am ET (evening HKT). These are the last major inflation readings before the Fed’s 15–16 September decision, where futures currently price roughly a coin-flip-to-slightly-favoured quarter-point hike after Chair Warsh’s hawkish Jackson Hole keynote and a blowout August jobs report.
MACRO
China Trade Balance, CPI, PPI & Money Supply — Tuesday–Thursday
China’s August trade balance lands Tuesday, followed by CPI and PPI Wednesday and M0/M1/M2 money supply Thursday. Economists expect CPI to rebound toward 0.9% year-on-year on firmer food prices, with PPI extending its recovery to around 3.2% — a data-dense stretch central to the demand outlook for copper and sentiment across the Hang Seng.
CENTRAL BANK
Australia Confidence Data & RBA Speech — Tuesday, 8 September
Westpac Consumer Confidence (10:30am AEST) and NAB Business Confidence (11:30am AEST) are released Tuesday, alongside a speech from an RBA Assistant Governor in the evening. With no RBA meeting until 28–29 September, these are the week’s clearest domestic gauges for AUD/USD following a stronger-than-expected Q2 GDP print.
FX
Japan Data Docket — Monday & Tuesday
Monday brings Japan’s preliminary Coincident and Leading Economic Indexes alongside foreign exchange reserves; Tuesday adds the final revision to Q2 GDP, Average Cash Earnings, the Current Account balance, Bank Lending data, and the Eco Watchers Survey. None carries the weight of Friday’s US CPI, but together they add context to the ongoing BOJ hike debate ahead of the 17–18 September meeting.
CRYPTO / POLICY
CLARITY Act Cloture Vote Countdown — Building Toward 15 September
The Senate’s cloture vote on the CLARITY Act market-structure bill is scheduled for 15 September, just after this window closes, requiring 60 votes with Republicans holding 53 seats. SEC Chair Paul Atkins has said he expects and hopes the Senate will advance the bill, and positioning in XRP and, to a lesser extent, Litecoin is likely to keep building through the week ahead of it.
GEOPOLITICS
Middle East Tensions & Oil Prices — Ongoing
Renewed flare-ups in the Iran conflict pushed oil prices higher and briefly rattled Asian equities in the past two weeks, adding an inflation-risk premium that feeds directly into the Fed’s calculus ahead of its September meeting. CSFX is watching for any fresh escalation that could revive the risk-off, inflation-fear dynamic seen earlier this month.

Section 5 · Economic Calendar

Asian Session — Economic Calendar, 7–12 September 2026

All times approximate, Hong Kong Time (HKT, UTC+8) unless noted. Key releases for USD/JPY, AUD/USD, Copper, Hang Seng, Litecoin, and XRP.

Day Time (HKT) Release Impact Forecast CSFX View
Monday, 7 September
Mon~07:50 HKT Japan Preliminary Coincident & Leading Economic Indexes (July) LOWN/A Background context for the BOJ hike debate rather than a standalone catalyst; released alongside Japan’s FX reserves figures.
Tuesday, 8 September
Tue~08:30 HKT Australia Westpac Consumer Confidence (September) MEDN/A The week’s first read on how households are digesting resilient GDP data and rising RBA hike bets ahead of the 29 September decision.
Tue~09:30 HKT Australia NAB Business Confidence (August) MEDN/A A key gauge of how firms are pricing rising cost pressures through to consumers; watched closely given the empty RBA calendar this week.
Tue~07:30 HKT Japan Final Q2 GDP, Average Cash Earnings, Current Account & Bank Lending MEDN/A A bundle of secondary Japanese data adding context to the yen’s sharp rally and the ongoing BOJ tightening debate.
TueAll Day China Trade Balance & Import/Export YoY (August) HIGHN/A The week’s first major China data point, setting the tone ahead of Wednesday’s inflation prints for both copper and the Hang Seng.
Wednesday, 9 September
Wed~09:30 HKT China CPI & PPI (August) HIGHCPI ~0.9% YoY / PPI ~3.2% YoY The week’s single most important China release; a firm PPI print in particular would support the case that copper’s near-record prices are demand-justified.
Thursday, 10 September
ThuAll Day China M0/M1/M2 Money Supply (August) MEDN/A A secondary gauge of credit and liquidity conditions relevant to the broader China demand narrative for copper.
Thu~20:30 HKT US Producer Price Index (August) HIGHN/A Lands after the Asian close but sets the tone into Friday’s Asia open ahead of the CPI print and the following week’s FOMC decision.
Friday, 11 September
Fri~06:30 HKT New Zealand BusinessNZ Manufacturing PMI (August) LOWN/A A minor regional data point with limited spillover into the week’s major instruments.
Fri~20:30 HKT US Consumer Price Index (August) HIGHN/A The week’s single most important release overall; the last major inflation print before the Fed’s 15–16 September meeting, landing after the Asian close with the fullest reaction likely carrying into Monday’s open.
Saturday, 12 September
SatAll Day No Scheduled Asian Session Releases LOWN/A A quiet close to the week as markets digest Friday’s US CPI print and position ahead of the FOMC (15–16 Sep), the CLARITY Act vote (15 Sep) and the BOJ meeting (17–18 Sep).

Section 6 · FAQ

Asian Session — Trader Questions Answered

Key questions from CSFX clients ahead of US CPI, China’s data deluge, and the CLARITY Act vote

Why does this week’s US CPI matter so much if the FOMC decision isn’t until the following week?
Because it’s the last significant inflation data point the Fed will see before it meets on 15–16 September. Markets currently price roughly a coin-flip-to-slightly-favoured chance of a quarter-point hike, up from about a third before Fed Chair Kevin Warsh’s hawkish Jackson Hole keynote, and that pricing has already proven sensitive to incoming data — Friday’s blowout payrolls report reinforced the hawkish case, while dovish comments from a Fed governor pulled the odds back down earlier in the week. A hot CPI print would likely push hike odds higher still, while a soft one could tip the balance back toward a hold.
Why is USD/JPY falling even after a much stronger-than-expected US jobs report?
Because the yen side of the equation has been moving just as forcefully. USD/JPY posted its sharpest two-day rally in the yen’s favour since July’s confirmed intervention, with traders speculating that Japanese authorities may have conducted a rate check ahead of possible fresh action, layered on top of rising odds (63% priced) of a Bank of Japan hike at the 17–18 September meeting. That yen strength has so far offset the dollar’s positive reaction to Friday’s payrolls beat.
Why does China’s data week matter so much for copper and the Hang Seng specifically?
Because China is both the world’s largest copper consumer and the key swing factor for sentiment in Hong Kong-listed equities. Wednesday’s CPI and PPI prints, alongside Tuesday’s trade balance and Thursday’s money supply data, are the clearest available signals this week on whether China’s recent price recovery reflects genuine demand strength or remains largely driven by upstream input costs — a distinction that matters for whether copper’s near-record prices and the Hang Seng’s fragile rebound can hold.
With no RBA meeting this week, what should AUD/USD traders actually watch?
Tuesday’s Westpac Consumer Confidence and NAB Business Confidence surveys are the clearest domestic reference points, alongside a scheduled speech from an RBA Assistant Governor. The pair enters the week supported by a stronger-than-expected Q2 GDP print and market pricing of roughly a 66% chance of a hike at the RBA’s 28–29 September meeting, but China’s trade and inflation data in the middle of the week are arguably just as relevant given the Aussie’s sensitivity to Chinese demand.
What’s driving XRP and Litecoin’s rally, and how does the CLARITY Act vote change the calculus?
XRP has climbed more than 40% from its 17 August low as traders position ahead of the Senate’s 15 September cloture vote on the CLARITY Act, the bill that would classify XRP as a commodity under federal law. The vote needs 60 votes to advance, meaning Republicans’ 53 seats require Democratic support, and SEC Chair Paul Atkins has publicly said he expects the Senate to move the bill forward — though prediction markets still price the odds of the bill’s ultimate passage this year only in the teens to low twenties, leaving genuine two-way risk. Litecoin has largely tracked that improving sentiment as a broader crypto beta play rather than moving on any catalyst of its own.
Is Middle East geopolitical risk still a factor for Asian markets this week?
Yes, at the margin. Renewed flare-ups in the Iran conflict have pushed oil prices higher and briefly weighed on Asian equities in recent weeks, adding an inflation-risk premium that feeds into the Fed’s calculus ahead of its September meeting. CSFX is not treating this as a headline instrument this week, but any fresh escalation could quickly revive the risk-off, inflation-fear dynamic seen earlier in the month and spill over into both the Hang Seng and the yen’s safe-haven flows.
CSFX View · Week of 7 September 2026

CSFX View: China’s Data Deluge, US CPI, and a CLARITY Act Countdown Set the Tone for the Week Ahead


The week of 7–12 September 2026 opens the Asian session with USD/JPY at 156.25, still digesting the sharpest yen rally since July’s confirmed intervention even after a blowout US payrolls print, while AUD/USD at 0.7205 holds just below a four-year high with no RBA meeting to compete for attention until 28–29 September, leaving Tuesday’s confidence surveys as the week’s clearest domestic Aussie catalyst. Copper at $6.60/lb sits just below its August record as China’s trade balance, CPI and PPI data (Tuesday–Wednesday) test whether the recent price recovery is demand-led, while the Hang Seng at 25,651 enters the week rebuilding confidence after a volatile stretch that saw it slide to 24,960 before Friday’s 1.74% rebound. In crypto, XRP at $1.45 and Litecoin at $51.15 both trade meaningfully higher than a month ago as the Senate’s 15 September CLARITY Act cloture vote comes into view.

Thursday and Friday are the pivot points for the entire week: US PPI and CPI land in quick succession, the final inflation readings before the Fed’s 15–16 September decision, where futures currently price a coin-flip-to-slightly-favoured quarter-point hike. China’s Tuesday-through-Thursday data run is the parallel storyline for copper and the Hang Seng, testing whether the recent price recovery in industrial metals reflects genuine demand strength. AUD/USD’s path leans on confidence data and China’s docket in the absence of a live RBA meeting, while USD/JPY’s fate hinges on whether Friday’s CPI print reinforces or unwinds the yen’s sharp recent rally ahead of next week’s BOJ decision. In crypto, both XRP and Litecoin now have a concrete event to trade into for the first time in weeks, even if the CLARITY Act’s ultimate fate remains genuinely uncertain.

CSFX’s key levels for the week: watch 155.00 support and 158.50 resistance on USD/JPY, 0.7125 support and 0.7280 resistance on AUD/USD, and $1.35 support on XRP heading into the CLARITY Act vote. Copper is a watch between $6.20 support and $6.83 resistance as China’s data clarifies the demand picture; the Hang Seng’s next test is 26,000 resistance, with 24,900 as the key support if this week’s rebound fades; and Litecoin remains a broader crypto-sentiment play between $45.00 support and $58.00 resistance. CSFX will issue intra-week alerts if Japanese authorities signal fresh intervention, if China’s inflation data surprises materially in either direction, if Thursday’s or Friday’s US inflation prints move Fed hike odds sharply, or if the CLARITY Act’s Senate prospects shift meaningfully ahead of the 15 September vote. Follow all updates at capitalstreetfx.com.

New clients can also take advantage of a limited-time deposit bonus when they open an account this week, on top of the usual account benefits — tight spreads, high leverage, and access to 2000+ instruments across FX, commodities, indices, and crypto. Full terms and other promotions are available on the CSFX website.

Trade Asian Markets at CSFX →