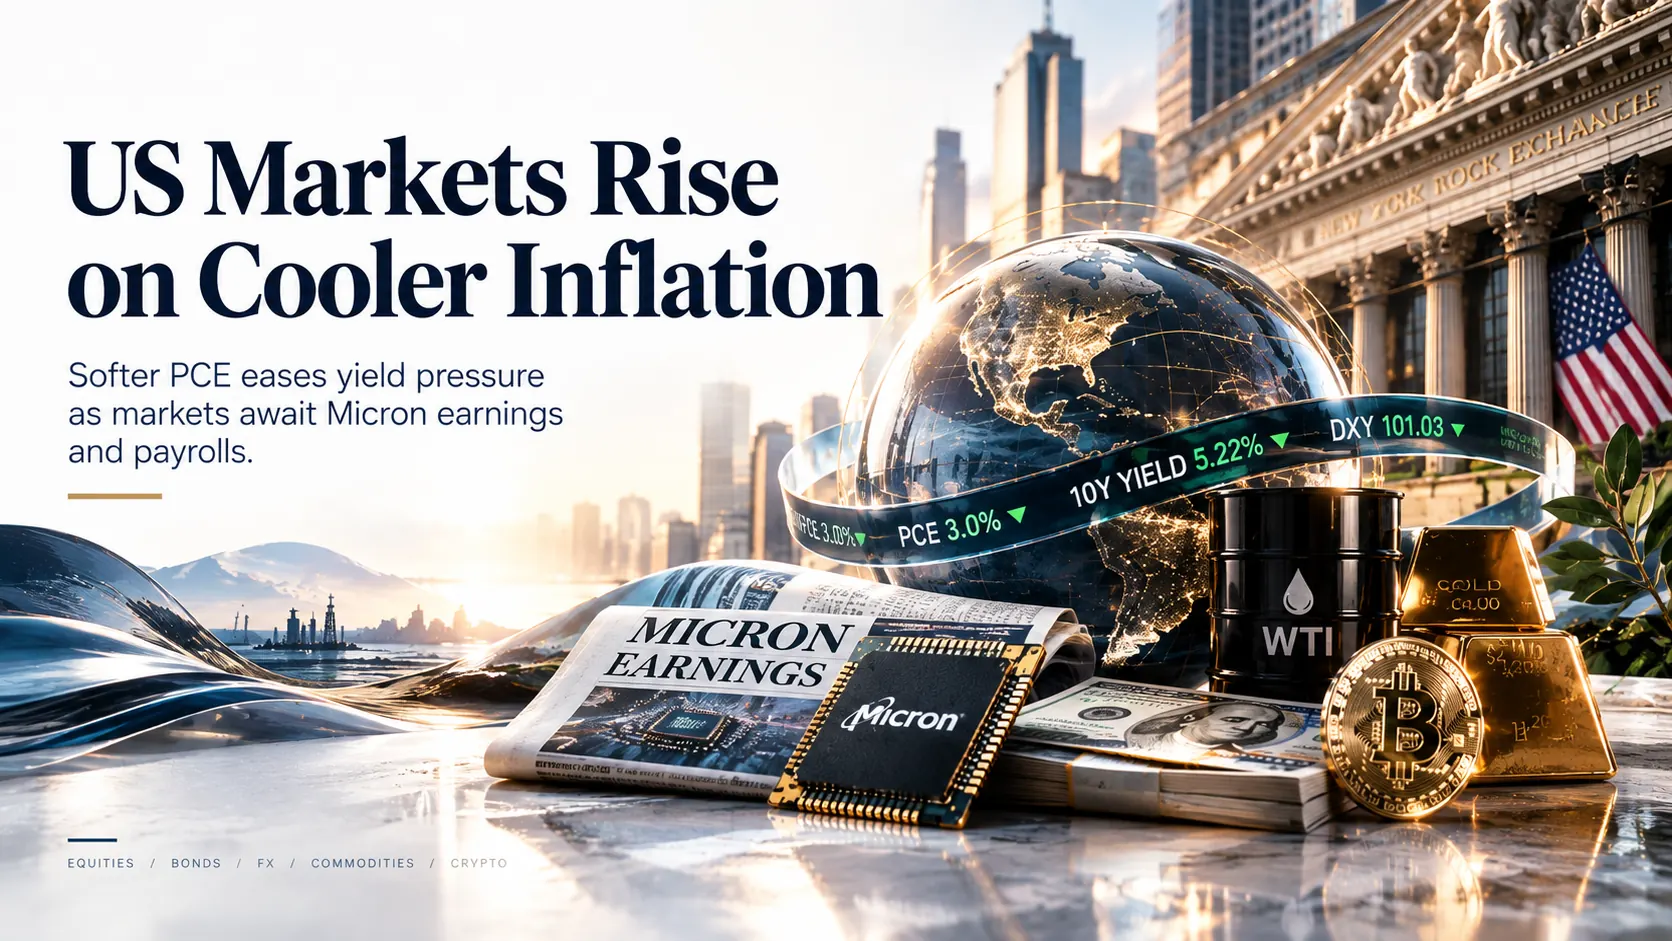
US Session Report: Cool PCE Pulls Yields Off 2007 Highs as Dollar Slips and Wall Street Bounces Into Quarter-End Ahead of Micron and Payrolls | 30 September 2026
US Session Report: Yields Resume Climb as Dollar Firms at Q4 Open — Wall Street Edges Higher Ahead of Payrolls
Wall Street edged higher on Thursday as Q4 got under way with yesterday’s cooler PCE (core 3.0%) still in focus, though the 10-year Treasury yield has ticked back toward 5.30% as the post-data relief rally fades. The S&P 500 is near 7,709, the Nasdaq leads with gains of about 0.9% near 27,040 and the Dow is flat near 51,371 at the open. The dollar index has steadied near 101.33 and ADP's 90K beat for September was digested in yesterday’s session.
WTI is near $91.43 as Middle East supply uncertainty persists, gold is near $4,188 and Bitcoin holds near $83,521. Today’s focus: ISM Manufacturing (14:00 GMT), weekly jobless claims and the Fed speaker calendar, with Friday’s non-farm payrolls (consensus ~90K, unemployment 4.1%) the week’s defining event.
Snapshot: US session, 1 October 2026 (~13:45-14:45 GMT / 17:45-18:45 UAE / 09:45-10:45 ET)Top Stories Moving the Market
Stocks start Q4 cautiously higher as yields edge back up
Nasdaq leads at +0.9% near 27,040 and the Dow is near 51,371 at the open. Investors focus on Friday’s payrolls as the first major macro test of Q4.
Yesterday’s cooler PCE still anchors tone as yields drift back up
Core PCE rose just 0.2% m/m vs 0.3% forecast (3.0% y/y vs 3.3%). Markets have partially priced out an October hike, but the 10Y is already retracing toward 5.30%.
Payrolls watch: Friday NFP seen at ~84-90K; ADP beat already in
ADP printed 90K vs 73K forecast yesterday. Friday’s government payrolls (consensus ~84-90K, unemployment 4.1%) are the week’s key event and will set October hike odds.
10-year yields retrace as post-PCE relief fades at Q4 open
The 10-year is back near 5.30%, the 20-year near 5.62%. Yesterday’s PCE-driven dip has largely unwound; the 2-year sits near 4.89% and NFP Friday looms large.
Dollar steadies at Q4 open after yesterday’s PCE-driven dip
DXY has retraced to 101.33 as yields recover. USD/CAD is near 1.4175, USD/CHF holds near 0.8337 and USD/JPY stays below 147 on BoJ intervention risk.
Oil holds near $91 after EIA confirmed modest inventory build
Yesterday’s EIA data confirmed a small crude build. Middle East supply risks remain as Hormuz disruption concerns persist. WTI holds above $91 at the Q4 open.
Gold fades from $4,200 as yields and dollar rebound at Q4 start
Gold retreats to $4,188 as the PCE-driven rally gives back ground. Silver near $60.89 holds Monday’s closing reversal; payrolls Friday is the next key driver.
Bitcoin holds $83K level at Q4 open as macro uncertainty persists
Bitcoin consolidates near $83,521 with yields retracing yesterday’s drop. XRP is near $1.495-$1.50, holding the $1.50 technical area as the market watches payrolls Friday.
Technical Summary
USD/CAD
FX · Dollar steadies; CAD stays pressured by soft oil and risk-off tone
USD/CAD holds near 1.4175, well within the five-month high area near 1.4250 reached last week. Yesterday’s PCE-driven dip to 1.4155 was quickly retraced as yields and the dollar recovered. Wide US-Canada yield spreads and soft oil continue to support the pair; rallies into 1.4200-1.4210 can be faded toward 1.4110. A daily close above 1.4265 would extend the run higher ahead of Friday’s NFP.
| Resistance | Support |
|---|---|
| R11.4210 | S11.4155 |
| R21.4250 | S21.4100 |
| R31.4300 | S31.4055 |
USD/CHF
FX · Pair consolidates below 16-month highs as Q4 begins
USD/CHF eases back to 0.8337 at the Q4 open, just below its 16-month high of 0.8358 set earlier in the week. Yesterday’s cooler PCE trimmed dollar demand, though rising yields are limiting the pullback. Switzerland’s KOF rose to a six-year high at 109.1, giving the franc some fundamental support. Sellers can look to fade into 0.8358 targeting 0.8290; a sustained close above 0.8390 extends the uptrend into Friday’s payrolls.
| Resistance | Support |
|---|---|
| R10.8358 | S10.8290 |
| R20.8390 | S20.8250 |
| R30.8430 | S30.8210 |
Silver (XAG/USD)
Metals · Holding reversal gains near $60.89 as yields rebound
Silver holds near $60.89 at the Q4 open, building on Tuesday’s reversal candle off the $60.30 low. It remains below its 20-day EMA near $64. The bounce needs to clear $61.80 to gain traction; a move above $62.60 would flip the short-term bias higher. Renewed yield pressure is a headwind; failure below $60.30 re-opens $58.50 ahead of payrolls Friday.
| Resistance | Support |
|---|---|
| R1$62.60 | S1$60.30 |
| R2$64.09 | S2$58.50 |
| R3$65.00 | S3$55.00 |
Crude Oil (WTI)
Energy · Holding above $91 at Q4 start after EIA confirmed build
WTI holds near $91.43 at the Q4 open. Wednesday’s EIA report confirmed a modest crude inventory build, limiting upside. Middle East supply risk persists after talks stalled; Trump’s rejection of sanctions relief underpins the floor. Below $92.50 the next targets are $90.00 then $87.87 (50% Fib); a close above $93.60 would reinstate a bullish leg. Friday’s payrolls will drive demand-growth expectations.
| Resistance | Support |
|---|---|
| R1$92.50 | S1$90.00 |
| R2$94.30 | S2$87.87 |
| R3$95.50 | S3$85.00 |
Dow Jones (US30)
Indices · Q4 opens flat as yields rebound limits blue-chip recovery
The Dow closed Q3 at 51,350 and opens Q4 near 51,371. September’s ~3.6% decline driven by surging yields is behind it; the PCE-driven improvement in sentiment provides a Q4 base. With yields already retracing higher, the 51,830 level is the first upside hurdle. ISM Manufacturing today and Friday’s payrolls are the near-term tests; a close under 50,850 would cancel the bullish read.
| Resistance | Support |
|---|---|
| R151,830 | S151,000 |
| R252,490 | S250,850 |
| R353,185 | S350,500 |
US 20Y Yield
Rates · Long end retraces PCE dip, pressing channel highs again
The 20-year yield sits at 5.62% at the Q4 open, edging back up after the PCE-driven dip to 5.60% yesterday. Term-premium pressure from fiscal deficits and elevated oil persists; the 10-year has retraced to ~5.30%. Below 5.70% the immediate targets are 5.60% and 5.53%; payrolls Friday are the main risk — a strong jobs print would push yields above 5.74% and signal the selloff is extending.
| Resistance | Support |
|---|---|
| R15.70% | S15.60% |
| R25.74% | S25.53% |
| R35.80% | S35.45% |
Bitcoin (BTC/USD)
Crypto · Consolidating at Q4 open near key $83K support
Bitcoin opens Q4 at $83,521, consolidating after tagging $85.6K intraday on Wednesday. The $82,580-$82,940 support zone has held throughout the week; holding above $83,000 keeps $86,500 and $88,000 in the frame. The 10-year yield rebound is a headwind for risk assets. A daily close under $82,500 would invalidate the bullish setup; Friday’s payrolls are the next macro trigger.
| Resistance | Support |
|---|---|
| R1$86,500 | S1$83,000 |
| R2$88,000 | S2$82,580 |
| R3$90,000 | S3$80,000 |
XRP (XRP/USD)
Crypto · Holding the $1.50 area at Q4 open; watching payrolls Friday
XRP holds near $1.495 at the Q4 open, still contesting the key $1.50 level. The RSI near 56 keeps momentum neutral. A sustained close above $1.50 brings the weekly high of $1.5557 back into play and then the $1.66 zone; a break below $1.45 would cancel the setup. Friday’s payrolls could set the near-term direction for the entire crypto complex.
| Resistance | Support |
|---|---|
| R1$1.56 | S1$1.50 |
| R2$1.66 | S2$1.4656 |
| R3$1.70 | S3$1.40 |
What to Expect from the Next Session
- Micron reaction. Micron reported earnings after Wednesday’s close and early market reaction sets the tone for the chip sector today. The Nasdaq’s 0.9% lead reflects tech optimism as Q4 starts.
- ISM Manufacturing (14:00 GMT). First top-tier US data of Q4; the market looks for a hold near expansion territory after China’s official PMI returned to 50.1 in September. A miss could ease yield pressure.
- Jobless claims and Fed speakers. Weekly unemployment claims (12:30 GMT) provide a labour-market read ahead of tomorrow’s NFP; ADP already beat at 90K Wednesday. Fed speakers continue to calibrate October hike messaging.
- Payrolls Friday (2 Oct, 12:30 GMT). Non-farm payrolls consensus is ~84-90K with unemployment at 4.1%. A strong print above 120K would revive October hike bets and pressure yields-sensitive assets; a miss below 50K could deliver a significant risk-on relief rally.
What Is Moving the Market
PCE cools the hike trade — for now
Wednesday’s core PCE came in at 3.0% y/y (0.2% m/m), missing by 0.3 point and triggering a sharp dip in yields and the dollar. However, yields are already retracing: the 10-year is back near 5.30% as markets focus on Friday’s NFP to confirm or deny the October pause thesis.
Dollar firms at Q4 open
The DXY has recovered to 101.33 after touching 101.03 post-PCE Wednesday. The yield rebound is supporting the dollar; a strong NFP Friday could extend the dollar recovery toward Q3 highs near 101.80.
Oil steady on supply risk
WTI holds near $91.43 after the EIA confirmed a modest build on Wednesday. Hormuz disruption risk lingers as Iran talks remain stalled; US officials continue to flag risks of renewed conflict, capping downside in crude.
Q4 macro backdrop
China’s PMI returned to expansion at 50.1 in September, and German CPI at 3.3% keeps European rate pressure elevated. Gold near $4,188 and silver near $60.89 remain anchored by the multi-decade yields environment entering Q4.
Economic Calendar / Events
| Time (GMT) | Country | Event | Forecast vs. Actual |
|---|---|---|---|
| Yesterday | CN | Official Manufacturing PMI (Sep) | Actual 50.1, first expansion since June — Q4 opens with China back in expansion |
| Yesterday | DE | CPI flash (Sep) | Actual 3.3% y/y vs 2.9% in Aug — keeps ECB hawks active |
| Yesterday | US | ADP Employment (Sep) | Actual 90K vs fcst 73K (prev 36K revised) — beat keeps October hike debate alive |
| Yesterday | US | Core PCE (Aug), PCE, personal spending | Core 3.0% y/y vs 3.3% exp; core 0.2% m/m vs 0.3%; PCE 3.4% vs 3.7% — cooler than expected |
| Yesterday | US | Final Q2 GDP | Released alongside PCE; confirmed Q2 GDP |
| Yesterday | US | Chicago PMI (Sep) | Fcst 51.2 — Q3 factory activity reading digested |
| Yesterday | US | EIA Crude Oil Inventories (wk) | Confirmed modest crude build — bearish read absorbed; WTI holds above $91 |
| Today | US | ISM Manufacturing (14:00 GMT) | Fcst slight expansion — key first Q4 manufacturing read for the US |
| Today | US | Weekly Jobless Claims (12:30 GMT) | Labour market check ahead of NFP Friday; ADP beat at 90K yesterday |
| Friday 2 Oct | US | Non-Farm Payrolls (Sep), 12:30 GMT | Fcst ~84-90K, unemployment 4.1%; the week’s defining event for rates and FX |
Summary
Q4 opened with Wall Street edging higher on the back of Wednesday’s cooler PCE (3.0% core), though Treasury yields are already retracing: the 10-year is back near 5.30% and the 20-year near 5.62%. USD/CAD trades near 1.4175, USD/CHF near 0.8337, silver near $60.89, WTI near $91.43, the Dow near 51,371, the S&P 500 near 7,709, Bitcoin near $83,521 and XRP near $1.495. Friday’s non-farm payrolls (consensus ~84-90K, unemployment 4.1%) is the week’s decisive event for the rates, dollar and risk-asset outlook.
FAQ
Q:Why are US stocks higher at the Q4 open?
A:Yesterday’s cooler core PCE (3.0% vs 3.3% expected) provided relief from multi-decade yield highs, carrying momentum into Thursday. The Nasdaq is leading with ~0.9% gains, partly driven by Micron’s earnings reaction.
Q:What does the PCE mean for the Fed?
A:Wednesday’s cooler core PCE (3.0%) reduced October hike probability, but ADP’s 90K beat and Friday’s payrolls will be decisive. A strong NFP above ~120K would revive hiking bets sharply.
Q:What is moving oil?
A:Ongoing Middle East supply risk and stalled US-Iran talks; EIA confirmed a modest build on Wednesday. WTI holds near $91.43 with Hormuz disruption risk providing a floor.
Q:What could move silver, the Dow and crypto next?
A:Friday’s payrolls are the key catalyst; a hot number above 120K would revive October hike bets and pressure yields-sensitive assets including silver, crypto and dividend stocks. ISM Manufacturing today is the first test.