Week Ahead Asia, 21–25 September: Xi’s Washington Summit, Yen Intervention Watch Through Japan’s Silver Week and a Live RBA Hike Countdown Steer a Holiday-Thinned Asian Session | 19 September 2026
Week Ahead, 21–25 September: Xi’s Washington Summit, Yen Intervention Watch Through Japan’s Silver Week and a Live RBA Hike Countdown Steer a Holiday-Thinned Asian Session
China LPR Mon 21 Sep · Japan Markets Closed Mon–Wed · Aussie Jobs & Japan Flash PMI Thu 24 Sep · Xi–Trump Summit Thu 24 Sep · China Mid-Autumn Holiday Fri 25 Sep · Full Asian session news for the week of 21–25 September 2026
1. USD/JPY — can the yen hold its ground through Silver Week with the BOJ checking rates? USD/JPY starts the week near 156.80 after the Bank of Japan lifted its policy rate to 1.25% on Friday. The 7–2 vote, with Toichiro Asada and Ayano Sato dissenting, together with Governor Ueda’s data-dependent tone and refusal to set a timetable, disappointed traders hoping for a faster tightening path; the yen slid 1.3% at one point, sending the pair to 158.06. A Nikkei report that the BOJ made a rate check with market participants late Friday pulled it back to the upper 156s. Japan’s national CPI on Friday was soft, with core inflation at 1.7%, the eighth straight month below the 2% target, which explains the dissents. With Tokyo closed Monday through Wednesday, the Federal Reserve’s hawkish 25-basis-point hike to 3.75–4.00% and a median dot pointing to another 2026 increase keep the dollar side supported, while officials who already ran a joint US–Japan intervention earlier this summer have shown discomfort with moves toward 158.
2. AUD/USD — no RBA meeting, but the countdown to 29 September drives the Aussie. AUD/USD trades near 0.7120 after dipping to 0.7087 on Thursday in the wake of the Fed. The RBA’s next decision is 28–29 September, so there is no policy meeting this week, yet markets price a quarter-point hike to 4.60% at somewhere between roughly 80% and 96% depending on the gauge, after Governor Michele Bullock told a parliamentary committee on Friday that upside risks to inflation appear to be materialising. Wednesday’s flash PMIs and Thursday’s August labour force report — employment is expected to rise about 20,000 after July’s 15,800 drop, with unemployment steady at 4.5% — are the main scheduled inputs, alongside Chinese demand signals from Monday’s LPR and Thursday’s summit.
3. Copper and the Hang Seng — China demand and a leaders’ summit. Copper at $6.63/lb has gained four sessions in a row, helped by China’s Yangshan premium climbing to $121 a ton, its highest since November 2022, and by a delay to the Trump administration’s decision on refined copper tariffs; it remains under the August record near $6.83. The Hang Seng closed Friday at 24,750 after a 0.6% gain led by technology, with mainland stocks logging their best day in a month, as investors bet that Thursday’s meeting between Xi and Trump will ease trade tensions. Beijing’s fiscal-support signals and a Hong Kong Monetary Authority base-rate rise to 4.25% after the Fed frame the domestic backdrop, and August activity data — factory output +5.2% but retail sales just +0.4% and fixed-asset investment down 7.2% year to date — kept the growth debate alive.
4. XRP and Litecoin — life after the CLARITY Act’s failed vote. XRP at $1.33 and Litecoin at $55.00 trade the aftermath of the Senate’s 49–50 cloture defeat of the Digital Asset Market Clarity Act on Tuesday. Senator Thom Tillis’s motion to reconsider leaves a procedural door open, but Senator Cynthia Lummis has said the bill will not return soon and colleagues point to the lame-duck session at best. That shifts attention to the SEC’s “Regulation Crypto Assets” proposal, open for comment until 20 October, and to ongoing CFTC work. With spot crypto ETFs on track for a second straight week of outflows above $420 million and Bitcoin capped below its 50-week average near $78,760, both tokens enter a week of thin Asian holiday liquidity with Litecoin bouncing off the $50 zone and XRP holding the low $1.30s.
Four Forces That Will Drive the Asian Session — 21 to 25 September 2026
The scheduled Asian-session catalysts that will set the direction across FX, commodities, equities, and digital assets for the week of 21–25 September 2026
Asian Session Weekly Levels & Bias
Six instrument-specific reference levels for the week of 21–25 September 2026. All levels for reference and informational purposes only; not financial advice. Visit capitalstreetfx.com for live signals and other markets.
What to Watch — Can the Yen Hold Its Ground Through Silver Week With a BOJ Rate Check in the Background?
USD/JPY starts the week near 156.80 after touching 158.06 on Friday, when the Bank of Japan raised its policy rate to 1.25% but two members dissented and Governor Ueda gave no timetable for further increases. A Nikkei report that the BOJ conducted a rate check with market participants late Friday cut the pair’s gains and signals officials remain uncomfortable near 158, particularly after this summer’s joint US–Japan intervention that pulled the pair from around 164 to the mid-155s.
With Tokyo closed from Monday to Wednesday, thin liquidity raises the odds of sharp headline-driven moves. The 158 area is the level to watch on the topside; the 154.80 zone is the first support if the yen rallies on intervention or a dovish dollar turn. The Thursday reopening brings the Japan flash PMI and the new rate taking effect, while Friday’s Tokyo CPI is the last domestic input of the week.

What to Watch — No RBA Meeting, but Jobs Data and a Priced-In Hike Do the Heavy Lifting
AUD/USD trades near 0.7120 after slipping 0.6% to 0.7087 on Thursday following the Fed’s hike and rebounding on hawkish RBA commentary. The RBA’s next meeting is 28–29 September, with a quarter-point hike to 4.60% priced at roughly 80% to 96% depending on the measure; UBS sees two more hikes taking the cash rate to 4.85%. With that priced, the data has more room to disappoint than to surprise.
Wednesday’s Australian flash PMIs and Thursday’s August labour force report (employment seen around +20,000 after July’s −15,800, unemployment at 4.5%) are the key scheduled events, while Xi–Trump headlines matter for China-sensitive Aussie flows. UOB has flagged risk toward 0.7050 while the pair stays below 0.7140; a move through 0.7210 would put the early-September highs back in view.

What to Watch — China’s Demand Signals and the Xi–Trump Meeting Test the Rally
Copper at $6.63/lb has gained four sessions in a row, supported by strong Chinese physical demand: the Yangshan premium reached $121 a ton on Thursday, its highest since November 2022, while data-centre and renewable demand and mine supply disruptions provide a longer-term backdrop. Earlier in the week prices dipped after reports that the Trump administration delayed a decision on tariffs on refined copper.
This week’s tests are Monday’s China loan prime rate, Thursday’s Xi–Trump summit — where any tariff truce extension, critical minerals or export-control news feeds directly into industrial-metals sentiment — and whether Chinese restocking persists ahead of Golden Week from 1 October. Fresh LME inflows have pushed London copper into contango, a reminder near-term supply is ample. The August record near $6.83 is the topside marker, with the $6.43 area the first level to defend.

What to Watch — Summit Optimism Meets Higher Rates and a Holiday-Thinned Friday
The Hang Seng closed Friday at 24,750, up 0.6%, with the Hang Seng Tech Index up 2.2% as chip and AI names rallied and mainland stocks logged their best day in a month. The index was little changed on the week, after the Fed’s hike, Treasury yields above 5% and a Hong Kong Monetary Authority base-rate rise to 4.25% pressured property and financial shares. Investors are betting that Thursday’s Xi–Trump meeting delivers steps such as a tariff truce extension or a mutual tariff cut on about $30 billion of goods.
Watch Monday’s loan prime rate, expected unchanged at 3.00% and 3.50% for a 16th month, and any Beijing stimulus headlines after August data showed factory output up 5.2% but retail sales just 0.4% and fixed-asset investment down 7.2%. On Friday, Shanghai and Shenzhen are shut for Mid-Autumn while the Hong Kong holiday falls on Saturday, so HKEX trades with Stock Connect closed and thinner liquidity. Renewed AI-chip export-control headlines from Washington are a risk to the tech rally.

What to Watch — A Beta Play on Crypto Sentiment After the CLARITY Act Stumbles
Litecoin at $55.00 has recovered for a third straight session from the $50 support zone, but it lacks a token-specific catalyst and trades largely as a beta play on broader crypto sentiment. Bitcoin, above $78,000, is capped by its 50-week average near $78,760, and spot crypto ETFs are on course for a second week of outflows exceeding $420 million.
The $50 area is the level to defend for the recovery to stay intact, while a push toward $63.70 would need improved risk appetite after the failed CLARITY Act vote and a hawkish Fed. Asian holiday closures thin liquidity late in the week, which can exaggerate moves in smaller-cap tokens.

What to Watch — Regulators, Not Congress, Now Set the Near-Term Regulatory Path
XRP at $1.33 ended the week roughly flat despite the Senate’s 49–50 cloture defeat of the CLARITY Act, which was widely priced by prediction markets. Tillis’s motion to reconsider keeps a procedural option, but Senator Lummis has said the bill is unlikely to return, and colleagues point to the lame-duck session at best.
Attention shifts to the SEC’s Regulation Crypto Assets proposal, open for comment until 20 October, and to CFTC spot-market work. A hold above $1.234 keeps the recent structure intact, while a break lower would leave the token vulnerable to a retest of the low-$1.20s. The $1.55 level, near the August rally high, is the topside reference. Thin holiday liquidity and ETF outflows are near-term headwinds.

What Could Move Asian Markets Sharply This Week
The scheduled and unscheduled events that CSFX is watching most closely for the Asian session, 21–25 September 2026
Asian Session — Economic Calendar, 21–25 September 2026
All times approximate, Hong Kong Time (HKT, UTC+8) unless noted; confirm exact release times before trading. Key releases and events for USD/JPY, AUD/USD, Copper, Hang Seng, Litecoin, and XRP.
| Day | Time (HKT) | Release / Event | Impact | Relevance | CSFX View |
|---|---|---|---|---|---|
| Monday, 21 September | |||||
| Mon | All day | Japan Market Holiday — Respect for the Aged Day (Tokyo closed) | Medium | USD/JPY | Yen trades in thinner liquidity after Friday’s BOJ rate check; watch for MoF or Treasury headlines. |
| Mon | ~09:15 HKT | China Loan Prime Rate (1Y 3.00%, 5Y 3.50% expected) | Medium | Hang Seng, Copper, AUD/USD | Seen unchanged for a 16th month; a surprise cut would signal greater concern about growth. |
| Tuesday, 22 September | |||||
| Tue | All day | Japan Market Holiday — Citizens’ Holiday (Tokyo closed) | Medium | USD/JPY | Second closed day; intervention risk continues. |
| Tue | ~01:00 HKT (Wed) | US 2-Year Treasury Note Auction ($78 bn) | Low | USD/JPY, AUD/USD | Demand read on front-end yields after the Fed hike and 10-year yield’s spike above 5%. |
| Wednesday, 23 September | |||||
| Wed | All day | Japan Market Holiday — Autumnal Equinox Day (Tokyo closed) | Medium | USD/JPY | Tokyo reopens Thursday; the BOJ’s new 1.25% rate takes effect 24 September. |
| Wed | ~07:00 HKT (TBC) | Australia Flash PMIs (Sep) | Medium | AUD/USD | A demand and price-pressure read days before the RBA’s 28–29 September meeting. |
| Wed | ~21:45 HKT (TBC) | US Flash PMIs (Sep) | Medium | USD/JPY, AUD/USD, Hang Seng | Tests the US growth story after the Fed hike; a firm print supports the dollar into Thursday’s Asian open. |
| Thursday, 24 September | |||||
| Thu | ~08:30 HKT | Japan Flash PMI (Sep) — first Tokyo session after the break | Medium | USD/JPY | Manufacturing seen near 54.8, services near 52.6; price components also in focus. |
| Thu | ~09:30 HKT | Australia Labour Force Survey (Aug) | High | AUD/USD | Employment seen around +20,000 after −15,800 in July, unemployment steady at 4.5%; the RBA is seen as hiking regardless. |
| Thu | Thu night–Fri early HKT (TBC) | Xi–Trump State Visit and White House Talks / State Dinner | High | Hang Seng, Copper, AUD/USD | Tariff truce extension, ag/Boeing purchases, rare earths and chip curbs are in focus. |
| Thu | All day | South Korea Market Holiday — Chuseok (Thu–Fri) | Low | Regional risk | Adds to thin Asian liquidity late in the week. |
| Friday, 25 September | |||||
| Fri | ~07:30 HKT (TBC) | Tokyo CPI (Sep) | Medium | USD/JPY | Leading read on inflation after national core CPI stayed below 2% at 1.7% in August. |
| Fri | All day | China Mid-Autumn Festival — Shanghai/Shenzhen and Stock Connect closed; Taiwan closed; HKEX open | Medium | Hang Seng, Copper | Hong Kong’s holiday falls on Saturday; expect thin liquidity and headline-driven moves post-summit. |
| Fri | ~20:30 HKT | US Durable Goods Orders (Aug) | Low | USD/JPY, AUD/USD | A capex read to close the week for the dollar. |
| Weekend | Sat–Sun | Crypto trades 24/7; RBA meeting begins Monday 28 September | Medium | XRP, Litecoin, AUD/USD | Weekend liquidity can be thin; positioning for the RBA and the SEC comment period continues. |
Asian Session — Trader Questions Answered
Key questions from CSFX clients ahead of Xi’s Washington visit, the yen intervention watch, the RBA run-up and the post-CLARITY crypto backdrop
CSFX View: A Xi–Trump Summit, an Intervention-Primed Yen and an RBA Countdown Define a Holiday-Thinned Week
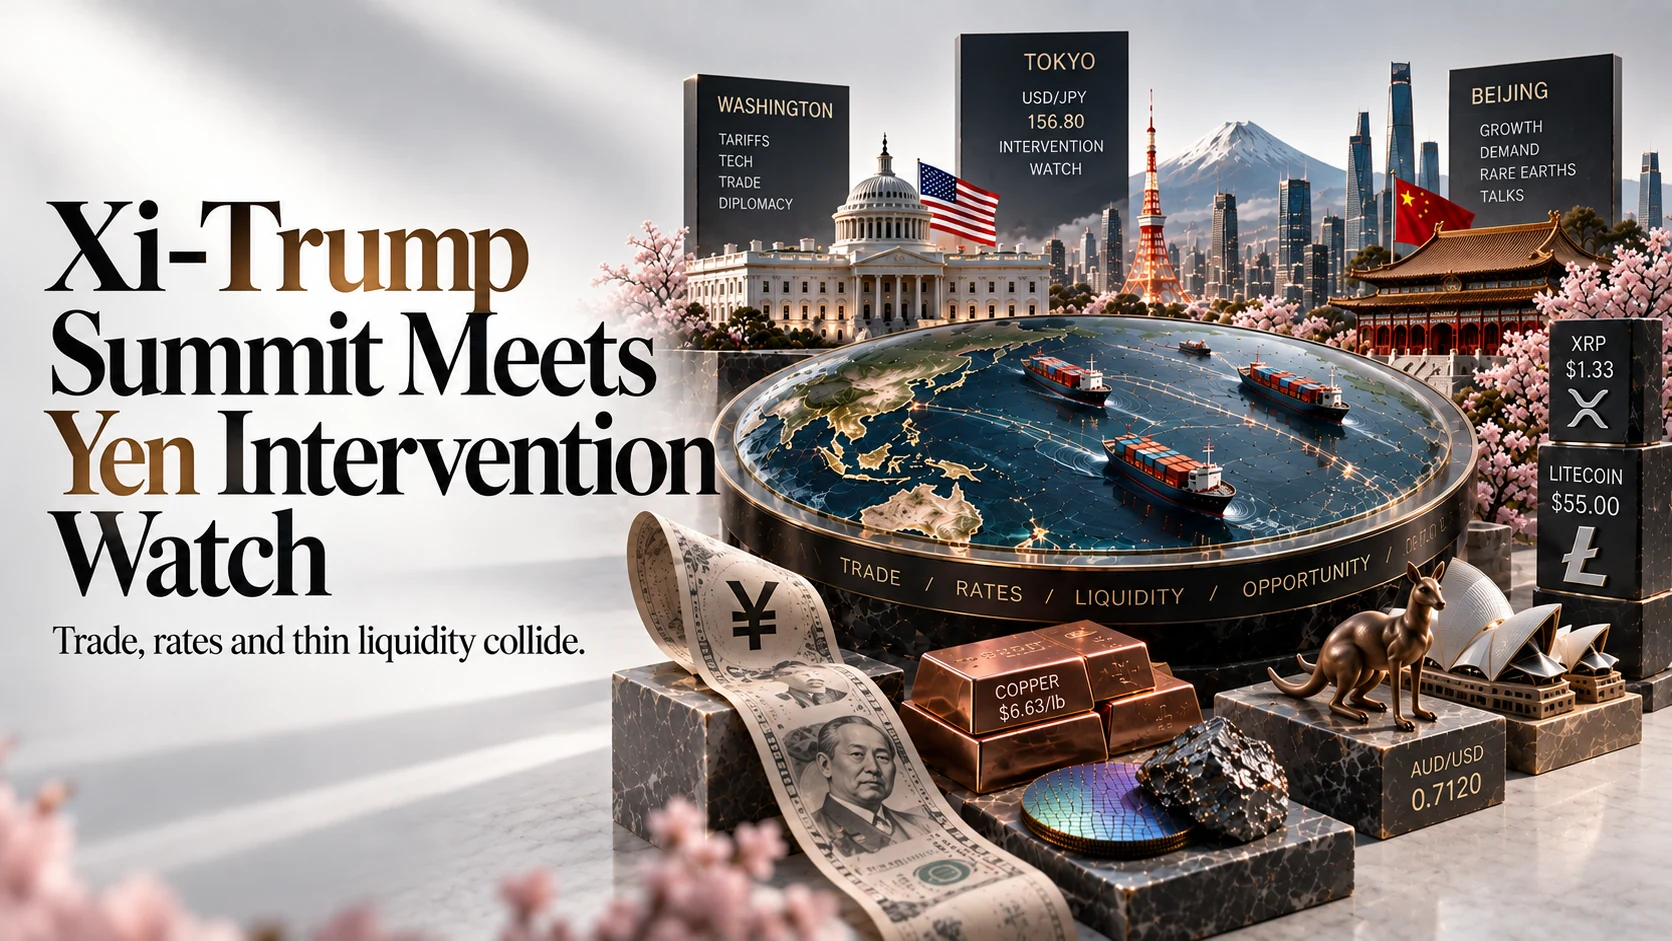
The week of 21–25 September 2026 opens the Asian session with USD/JPY at 156.80 after a split BOJ hike and a reported rate check, AUD/USD at 0.7120 counting down to the RBA’s 29 September decision, copper at $6.63/lb riding Chinese demand, and the Hang Seng at 24,750 leaning on hopes for Thursday’s summit in Washington. In crypto, XRP at $1.33 and Litecoin at $55.00 trade the aftermath of the failed CLARITY Act vote with regulators now setting the pace.
Thursday is the pivot day: Xi meets Trump in Washington, Tokyo reopens with a flash PMI, and Australia releases its August labour force data. Before it, thin holiday liquidity leaves the yen exposed to intervention headlines; after it, Friday’s Mid-Autumn closure of mainland exchanges and the RBA’s meeting on Monday and Tuesday keep positioning cautious. Outcomes on tariffs, rare earths and chip curbs will drive the Hang Seng, copper and AUD/USD, while a firm dollar and elevated yields remain the backdrop for every instrument.
CSFX will continue publishing intra-week updates as the Xi–Trump meeting, any yen intervention, Australia’s jobs data and China’s stimulus signals unfold. Follow all updates at capitalstreetfx.com.
New clients can also take advantage of a limited-time deposit bonus when they open an account this week, on top of the usual account benefits — tight spreads, high leverage, and access to 2000+ instruments across FX, commodities, indices, and crypto. Full terms and other promotions are available on the CSFX website.
Trade Asian Markets at CSFX →