Capital Street FX

european markets crossroads

Week Ahead – Europe, 31 August– 4 September: Eurozone Flash Inflation Is the Last Word Before the ECB’s 10 September Decision

August 29, 2026
CSFXadmin
Week Ahead, 31 August–4 September: Eurozone Flash Inflation Is the Last Word Before the ECB’s 10 September Decision | CSFX European Session Weekly
European Market Weekly Preview
Saturday 29 August 2026 · Week of 31 August – 4 September 2026 · UK Bank Holiday Monday · Four-Day London Week

Week Ahead, 31 August–4 September: Eurozone Flash Inflation Is the Last Word Before the ECB’s 10 September Decision

EUR/USD 1.1585 · GBP/USD 1.3590 · DAX 26,569.99 · FTSE 100 10,824.27 · STOXX 600 655.16 · Brent Crude $88.28
German Flash HICP Mon 31 Aug · Eurozone Flash HICP Tue 1 Sep · BoE Treasury Committee Hearings Thu 3 Sep · US Payrolls Fri 4 Sep · London closed Monday for the Summer Bank Holiday
EUR/USD· GBP/USD· DAX 40· FTSE 100· STOXX 600· Brent Crude
📋 Upcoming Week at a Glance · 31 August – 4 September 2026
Germany Monday, the Euro Area Tuesday: Two Inflation Prints Decide What the ECB Says on 10 September
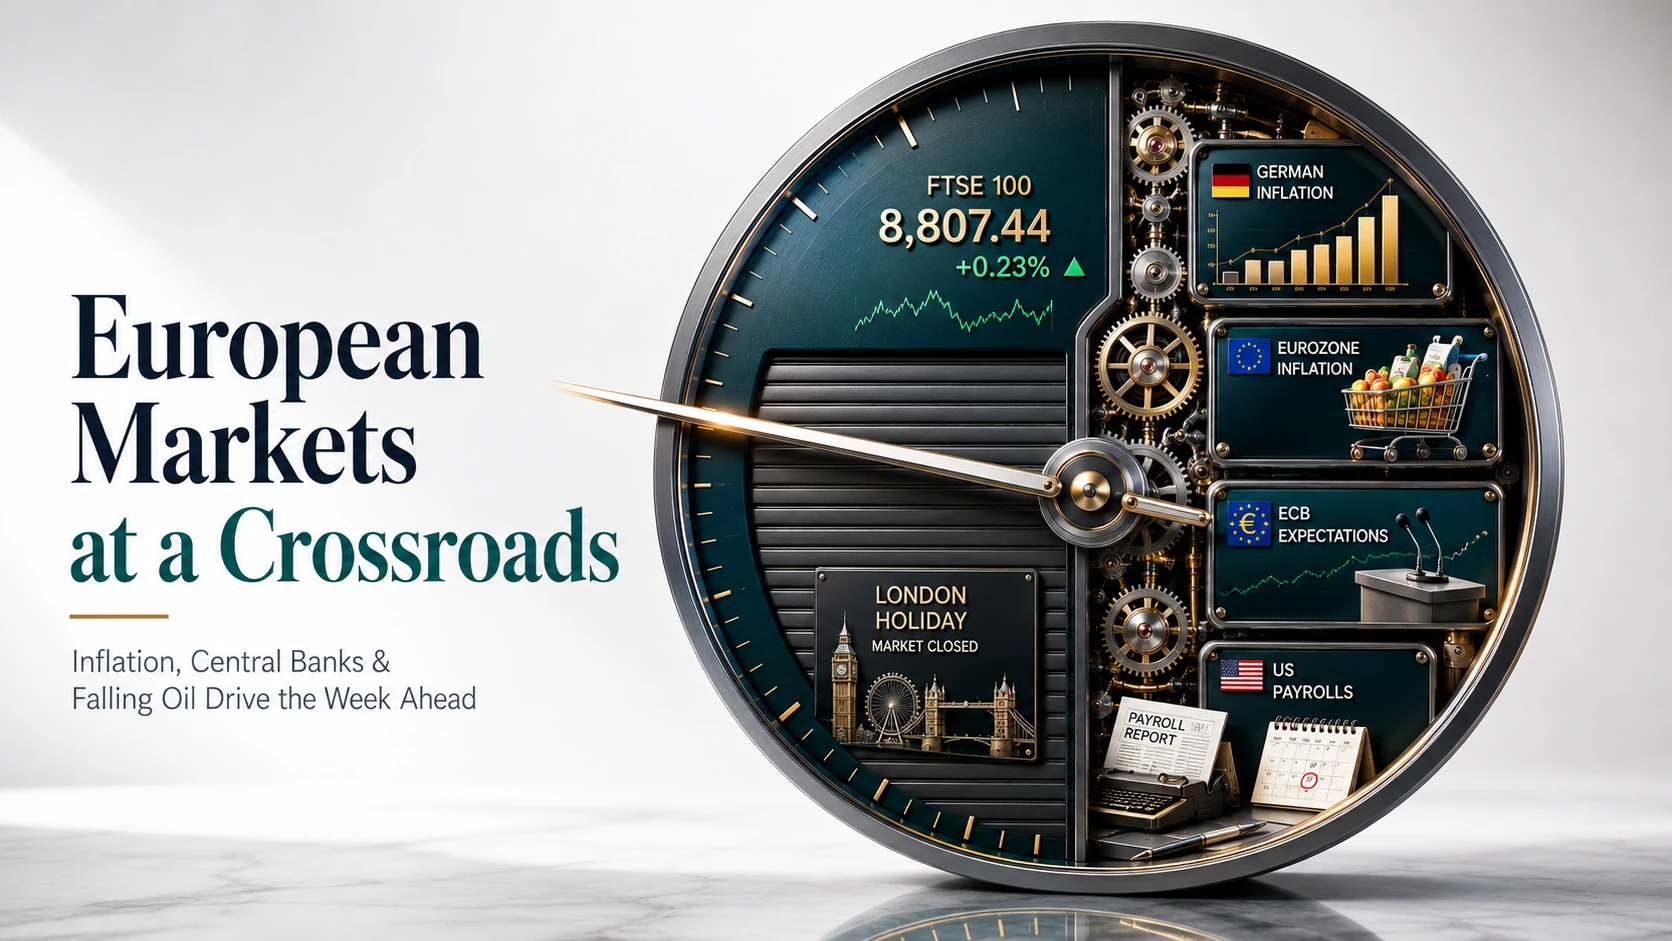
The week of 31 August – 4 September 2026 is short in London and heavy in Frankfurt. The London Stock Exchange is closed on Monday for the Summer Bank Holiday, so the FTSE 100 opens the week only on Tuesday, while the euro area runs straight into the two data points that will settle the tone of the ECB’s 10 September decision. Germany publishes its flash harmonised inflation estimate on Monday afternoon, with consensus looking for a rise to roughly 3.0% year-on-year from 2.8% in July, and the euro-area flash HICP follows on Tuesday morning, where the market is positioned for around 3.1% headline and 2.6% core. Friday’s national prints already tilted the risk: French EU-harmonised inflation climbed to 2.7% and Spain’s to 4.5%, the highest since 2023, though core rates eased in both countries — evidence that six months on from the start of the Iran war the energy shock has not yet produced broad second-round effects. A 25 basis point ECB hike to 2.50% is effectively fully priced, and Reuters reported this week that Governing Council members are ready to move in September but have little appetite to pre-commit to anything beyond it. That makes Tuesday less a referendum on September than on what comes after. Cutting the other way, Brent Crude has fallen 5.7% over the past week to $88.28 as Gulf export flows recover and Iran and Oman agree a revenue-sharing framework for the Strait of Hormuz — the single biggest downward force on the euro area’s energy-driven inflation impulse. In the UK, Bank Rate stays at 3.75% with the next MPC decision on 17 September, and Thursday’s Treasury Committee hearings with Governor Bailey and MPC members are the week’s only genuine domestic catalyst for sterling.
🇩🇪 German Flash HICP Mon 31 Aug 🇪🇺 Eurozone Flash HICP Tue 1 Sep 🏦 ECB Quiet Period Begins Thu 3 Sep 🇬🇧 BoE Treasury Hearings Thu 3 Sep 🇺🇸 US Payrolls Fri 4 Sep
Section 1 · About the European Market This Week
Four threads carry into the European session this week, each tied to its own instrument: a two-sided inflation trade for EUR/USD at 1.1585 after Warsh’s hawkish Jackson Hole turn; a four-day London week for GBP/USD (1.3590) and the FTSE 100 (10,824.27) around Thursday’s Treasury Committee hearings; record-territory equity risk for the DAX (26,569.99) and STOXX 600 (655.16) if Tuesday’s core print runs hot; and a fading Hormuz risk premium for Brent Crude ($88.28).

1. EUR/USD — the euro’s inflation support meets a newly hawkish Fed. EUR/USD at 1.1585 gave back 0.58% on Friday, ending the week 0.8% lower and well off the 1.1712 high it set on 21 August, after Fed Chair Kevin Warsh told the Jackson Hole symposium that the summer’s PCE and CPI readings did not convince him underlying trends had meaningfully improved. That pushed the risk of a September Fed hike higher and lifted the dollar. The offset is domestic: Monday’s German flash HICP and Tuesday’s euro-area flash HICP are the last major inflation inputs before the ECB’s 10 September meeting, and both are expected to accelerate. CSFX sees the pair as a genuinely two-sided trade this week rather than a directional one — the euro’s rate support is real, but so is the dollar’s.

2. GBP/USD — a four-day week with one real domestic catalyst. GBP/USD at 1.3590 edged 0.06% lower on Friday and finished the week down about 0.3%, holding up better than the euro as the retreat in Brent eased UK inflation concerns and pushed market expectations for the next Bank of England hike further out. Bank Rate stays at 3.75% and the MPC does not meet again until 17 September, where roughly three-quarters of the market currently expects no change. Thursday’s Treasury Committee hearings, with Governor Bailey and MPC members appearing before Parliament two weeks ahead of that decision, are the week’s only first-tier UK event.

3. DAX and STOXX 600 — record highs into the euro area’s hottest inflation print of the year. DAX 40 closed Friday at a record 26,569.99, up 1.66% on the week, led by autos as BMW gained more than 4% and Volkswagen and Mercedes-Benz each added over 2%. The broader STOXX 600 at 655.16 rebounded 0.51% on Friday for a 0.15% weekly gain, but remains below its 7 August record close of 660.25. Lower oil and continued tech optimism have done the heavy lifting; CSFX sees Tuesday’s core HICP as the main risk to that, since a firm core reading would strengthen the case for the ECB to signal further tightening beyond September.

4. FTSE 100 and Brent Crude — a shorter week and a shrinking risk premium. FTSE 100 at 10,824.27 added just 0.07% over the week and sits close to record territory, but London is closed on Monday for the Summer Bank Holiday, compressing the index’s week into four sessions. Brent Crude at $88.28 has fallen 5.7% over the past week as traders reframed the Iran standoff as a sanctions and economics confrontation rather than an imminent supply threat, with Goldman Sachs estimating Persian Gulf exports have recovered to around 15–16 million barrels per day against a March trough of 5–6 million. CSFX sees oil’s direction as the swing factor cutting across every other instrument on this list.

EUR/USD
1.1585
▼ Down 0.58% Friday, 0.8% on the week
Eurozone flash HICP Tuesday the key catalyst
GBP/USD
1.3590
▼ Down 0.06% Friday, ~0.3% on the week
BoE Treasury Committee hearings Thursday
DAX 40
26,569.99
▲ Record close, up 1.66% on the week
Autos led; German flash HICP Monday
STOXX 600
655.16
▲ Up 0.51% Friday, below 7 Aug record
Core HICP Tuesday the main risk
FTSE 100
10,824.27
▲ Up 0.07% on the week, near records
London closed Monday; four-session week
Brent Crude
$88.28
▼ Down 5.67% on the week
Hormuz flows recovering; risk premium fading
Section 2 · What Moves Markets This Week

Three Forces That Will Drive the European Session — 31 August to 4 September 2026

The scheduled European-session catalysts that will set the direction across FX, equities, and commodities for the week of 31 August – 4 September 2026

🇩🇪🇪🇺
Force 1 · Back-to-Back Inflation Prints Are the Last Data Before the ECB Decides
Germany publishes its flash harmonised estimate on Monday afternoon, with consensus around 3.0% year-on-year against 2.8% in July, and the euro-area flash HICP lands Tuesday at roughly 11:00 CET, expected near 3.1% headline and 2.6% core. July’s euro-area reading of 2.9% was the fifth straight month above the ECB’s 2% target, with energy up 10% year-on-year and services inflation at 3.3%. Because the individual member states report before the aggregate, CSFX expects EUR/USD and Bund yields to react to Monday’s German number rather than waiting for Tuesday.
🏦
Force 2 · A September ECB Hike Is Priced — the Argument Has Moved to What Follows
Markets have fully priced a 25 basis point increase in the deposit rate to 2.50% on 10 September, and Reuters reported this week that Governing Council members are ready to move but see no need to hint at further tightening afterwards. Swap pricing implies close to one additional hike beyond September. The ECB’s pre-meeting quiet period begins around Thursday, so Monday to Wednesday is the final window for policymaker commentary; CSFX sees Tuesday’s core reading, not the headline, as the number that decides whether markets add to or trim that post-September pricing.
🛢️
Force 3 · Oil’s Retreat Is Quietly Undermining the Case for More Tightening
Brent has fallen 5.67% over the past week to $88.28 as traders came to view the Iran standoff as a sanctions and economic confrontation rather than an imminent threat to physical supply. Iran and Oman agreed a revenue-sharing framework for the Strait of Hormuz, though Tehran stressed this does not mean an immediate reopening, and Goldman Sachs estimates Gulf exports have recovered to roughly two-thirds of pre-conflict volumes. Since almost all of the euro area’s inflation overshoot is energy-driven, CSFX sees sustained weakness in crude as the clearest medium-term argument against the market’s post-September hike pricing.

Section 3 · Key Levels to Watch

European Session Weekly Levels & Bias

Six instrument-specific reference levels for the week of 31 August – 4 September 2026. All levels for reference and informational purposes only; not financial advice. Visit capitalstreetfx.com for live signals and other markets.

EUR/USD
1.1585
▼ Down 0.58% Friday as Warsh lifted the dollar
■ NEUTRAL / WATCH 1.1712 RESISTANCE, 1.1525 SUPPORT
Support
1.1525
Pivot
1.1585
Resistance
1.1712

What to Watch — Tuesday’s Core HICP Against a Newly Hawkish Fed

EUR/USD peaked at 1.1712 on 21 August before Friday’s reversal dragged it through the 1.1600 handle to close at 1.1585, its lowest daily close since 18 August. The pair now has genuine support on both sides: a fully priced ECB hike underpins the euro, while Warsh’s insistence that the Fed’s 2% target is firm and fixed underpins the dollar. CSFX sees an upside surprise in Tuesday’s core reading as the cleanest route back toward 1.1700, while an in-line print that fails to add to post-September hike pricing opens the 1.1525 shelf from early August into Friday’s US payrolls.

EUR/USD weekly chart
Chart by TradingView
GBP/USD
1.3590
▼ Down 0.06% Friday and about 0.3% on the week
■ NEUTRAL / WATCH 1.3677 RESISTANCE, 1.3450 SUPPORT
Support
1.3450
Pivot
1.3590
Resistance
1.3677

What to Watch — Thursday’s Parliamentary Hearings Are the Only Domestic Event

Sterling has drifted back from its 21 August high of 1.3677 to 1.3590, but held far better than the euro through Friday’s dollar rally, closing all but unchanged. Cheaper crude has eased the UK inflation outlook and pushed expectations for the next Bank of England hike out toward 2027. With Bank Rate on hold at 3.75% and the MPC not meeting until 17 September, Thursday’s Treasury Committee hearings with Governor Bailey and MPC members are the week’s only real domestic catalyst. CSFX sees hawkish testimony that reintroduces a 2026 hike into pricing as the trigger for a move back toward 1.3677, with Friday’s US payrolls the more likely source of a break below 1.3450.

GBP/USD weekly chart
Chart by TradingView
DAX 40
26,569.99
▲ Record close, up 1.66% on the week
▲ CONSTRUCTIVE / WATCH 27,000 RESISTANCE, 26,100 SUPPORT
Support
26,100
Pivot
26,569.99
Resistance
27,000

What to Watch — A Record Close Into Germany’s Own Inflation Print

The DAX finished Friday at a fresh record close of 26,569.99, just under its 26,573.50 all-time high, as BMW rose over 4% on a more positive Citigroup view and Volkswagen and Mercedes-Benz Group each added more than 2%. Utilities, chemicals, banks and insurers also advanced, with Infineon among the few decliners. Lower oil and resilient tech sentiment have driven the run. CSFX sees Monday’s German flash HICP as the first test: a print at or above the 3.0% consensus would firm up expectations of ECB tightening beyond September and put the recent rate-sensitive leadership — particularly autos and utilities — under pressure at these levels.

DAX 40 weekly chart
Chart by TradingView
STOXX 600
655.16
▲ Up 0.51% Friday, still shy of the 7 August record
■ NEUTRAL / WATCH 663.41 RESISTANCE, 645.00 SUPPORT
Support
645.00
Pivot
655.16
Resistance
663.41

What to Watch — French Banks, Fiscal Nerves, and the Pan-European Read on Tuesday

The pan-European benchmark rose 0.51% on Friday to 655.16, recovering Thursday’s 0.69% drop to end the week 0.15% higher, helped by French lenders — Societe Generale, BNP Paribas and Credit Agricole all rebounded from Thursday’s selloff, which was driven by concerns over France’s political and fiscal outlook ahead of the 2027 presidential election. The index sits below its 7 August record close of 660.25 and its 52-week high of 663.41. CSFX sees Tuesday’s euro-area core HICP as the clearest directional catalyst, with renewed French fiscal headlines the most likely source of an unscheduled move given how heavily banks are weighted in the index.

STOXX 600 weekly chart
Chart by TradingView
FTSE 100
10,824.27
▲ Up 0.07% on the week, close to record highs
■ NEUTRAL / WATCH 11,000 RESISTANCE, 10,700 SUPPORT
Support
10,700
Pivot
10,824.27
Resistance
11,000

What to Watch — A Four-Session Week With Two Opposing Forces

The London Stock Exchange is closed on Monday for the Summer Bank Holiday, so the FTSE 100 misses the German inflation print entirely and reopens on Tuesday to price two days of news at once. Two forces pull in opposite directions from here: the index’s heavy energy weighting is a drag while Brent retreats toward $88, but cheaper crude also eases the UK inflation outlook and supports domestically exposed names. CSFX sees Thursday’s Treasury Committee hearings and Friday’s US payrolls as the two sessions most likely to produce a decisive move, with 11,000 the level to clear on any upside break.

FTSE 100 weekly chart
Chart by TradingView
Brent Crude
$88.28
▼ Down 5.67% over the past week
▼ CAUTIOUS / WATCH $92.50 RESISTANCE, $85.00 SUPPORT
Support
$85.00
Pivot
$88.28
Resistance
$92.50

What to Watch — Hormuz Progress Against a Hard Ceiling on Diplomacy

Brent has snapped a two-week winning streak, falling $5.31 or 5.67% over the week to $88.28 as improving flows through Hormuz and the proposed Iran–Oman corridor reduced the perceived supply risk. Goldman Sachs estimates Persian Gulf exports have climbed to roughly 15–16 million barrels per day, still well below pre-conflict volumes of 22–24 million but far above March’s trough of 5–6 million. The counterweight is diplomatic: Washington has reportedly told mediators it does not intend to revive the terms of the collapsed June agreement with Iran. CSFX sees confirmation of an actual Hormuz reopening as the clearest route to $85, with any breakdown in the Oman-brokered framework the main upside risk toward $92.50.

Brent Crude weekly chart
Chart by TradingView

Section 4 · Key Catalysts

What Could Move European Markets Sharply This Week

The scheduled and unscheduled events that CSFX is watching most closely for the European session, 31 August – 4 September 2026

MACRO
German Flash HICP (August) — Monday, 31 August
Destatis publishes Germany’s preliminary harmonised inflation estimate at roughly 14:00 CET, with consensus looking for a rise to about 3.0% year-on-year from 2.8% in July. Because Germany reports before the euro-area aggregate, this is the first hard read on whether the August energy impulse is as strong as Friday’s French and Spanish prints implied. With London closed, CSFX expects the reaction to run through EUR/USD, Bunds and the DAX rather than a broad European risk move.
MACRO
Eurozone Flash HICP & Core (August) — Tuesday, 1 September
Eurostat’s flash estimate lands at roughly 11:00 CET and is the week’s single most important scheduled release. Headline is expected near 3.1% against 2.9% in July, with core forecast around 2.6% from 2.5%. July’s report showed energy up 10% year-on-year and services inflation at 3.3%, well above target for more than three years. CSFX sees the core figure as the number that matters, since it is the cleanest test of whether the Iran war energy shock is feeding into broader prices.
CENTRAL BANK
ECB Pre-Meeting Quiet Period Begins — From Thursday, 3 September
The Governing Council’s communications blackout ahead of the 10 September decision begins toward the end of this week, making Monday through Wednesday the final window for policymaker commentary on a hike that markets have already fully priced at 25 basis points to 2.50%. Reuters reported this week that governors are ready to move in September but see no need to signal further tightening beyond it, even as swap pricing implies close to one more increase. CSFX is watching for any speaker who pushes back on that post-September pricing before the window closes.
CENTRAL BANK
BoE Treasury Committee Hearings — Thursday, 3 September
Governor Andrew Bailey and Monetary Policy Committee members appear before Parliament’s Treasury Committee to discuss the latest Monetary Policy Report, roughly two weeks ahead of the 17 September rate decision. Bank Rate has been held at 3.75% since December 2025, with the 30 July vote splitting 6–3 as Greene, Mann and Pill dissented in favour of a hike, and the Bank’s central projection has CPI peaking near 3.2% in the fourth quarter. CSFX sees this as the week’s clearest source of sterling volatility.
FX
US August Nonfarm Payrolls — Friday, 4 September
The US employment report lands at 14:30 CET, in the middle of the European afternoon, and follows a disappointing July print of 57,000 alongside downward revisions to the prior three months. It is the first major labour reading since Warsh signalled at Jackson Hole that a September Fed hike is live. CSFX sees this as the week’s largest single source of dollar volatility and therefore the main risk to both EUR/USD and GBP/USD heading into the weekend.
GEOPOLITICS
Strait of Hormuz and the Iran–Oman Framework — Throughout the Week
Iran and Oman have agreed a revenue-sharing framework for the strait, though Tehran has stressed the arrangement does not guarantee an immediate reopening, and Washington has reportedly told mediators it will not revive the terms of the collapsed June agreement. With Gulf exports recovering to roughly two-thirds of pre-conflict levels, CSFX sees headline risk around the corridor as the dominant swing factor for Brent, the FTSE 100’s energy weighting, and — through the energy component of HICP — the euro area’s inflation path itself.

Section 5 · Economic Calendar

European Session — Economic Calendar, 31 August – 4 September 2026

All times approximate, Central European Time (CET/CEST) unless noted. Key releases for EUR/USD, GBP/USD, DAX 40, STOXX 600, FTSE 100, and Brent Crude.

Day Time (CET) Release Impact Forecast CSFX View
Monday, 31 August
MonAll Day UK Summer Bank Holiday — London Stock Exchange Closed LOWN/A No FTSE 100 session and thinner sterling liquidity; euro-area and German markets trade normally.
Mon~14:00 CET Germany Flash HICP & CPI (August) HIGH~3.0% y/y The first hard read on the August energy impulse, and the opening leg of the euro area’s last inflation round before the ECB’s 10 September decision.
MonMorning CET Italy Flash CPI (August) MEDN/A A secondary input alongside Friday’s French and Spanish prints, useful mainly for refining Tuesday’s euro-area estimate.
Tuesday, 1 September
Tue~08:00 CET Germany Retail Sales (July) MEDN/A Follows a 1.1% monthly decline; a second weak print would sharpen the contrast between resilient sentiment surveys and soft household spending.
Tue~09:55–10:30 CET Final Manufacturing PMIs — Germany, Eurozone, UK (August) MEDN/A Confirmation readings on a manufacturing sector that has been the euro area’s stronger half; the price sub-indices matter more than the headline this month.
Tue~11:00 CET Eurozone Flash HICP & Core HICP (August) HIGH~3.1% / ~2.6% y/y The week’s defining release. CSFX sees the core reading as the one that decides how much tightening beyond September stays priced into the curve.
Wednesday, 2 September
WedAll Day Final Window for ECB Speakers Before the Pre-Meeting Quiet Period MEDN/A The last chance for Governing Council members to shape expectations before the blackout; any pushback on post-September hike pricing would carry outsized weight.
Thursday, 3 September
Thu~09:55–10:30 CET Final Services & Composite PMIs — Germany, Eurozone, UK (August) MEDN/A July’s composite of 51.9 marked the first expansion in four months; confirmation of that recovery supports the case for the ECB tightening without damaging growth.
Thu~10:30 CET BoE Treasury Committee Hearings — Bailey and MPC Members HIGHN/A The week’s only first-tier UK event and the clearest source of GBP/USD volatility ahead of the 17 September decision.
Friday, 4 September
Fri~11:00 CET Eurozone Retail Sales (July) MEDN/A A read on whether higher energy costs are starting to bite into household consumption across the bloc, following a 0.3% monthly fall.
Fri14:30 CET US Nonfarm Payrolls, Unemployment Rate & Average Hourly Earnings (August) HIGHN/A Lands mid-European afternoon and is the week’s largest single driver of dollar direction, with the fullest reaction likely carrying into Monday’s open.

Section 6 · FAQ

European Session — Trader Questions Answered

Key questions from CSFX clients ahead of the euro area’s final inflation round before the ECB’s 10 September decision

If a September ECB hike is already fully priced, why does Tuesday’s inflation print still matter?
Because the market has moved past September. A 25 basis point increase in the deposit rate to 2.50% is effectively locked in, so Tuesday’s data cannot really change that decision — what it can change is the pricing for everything after it. Swap markets currently imply close to one additional hike beyond September, while Reuters reported this week that Governing Council members have little appetite to signal further tightening. That gap between what markets expect and what policymakers want to promise is where the volatility sits. A hot core reading validates the market; a soft one hands the doves an argument, and CSFX expects EUR/USD and the short end of the euro curve to move accordingly.
Why does the German print on Monday matter if the euro-area figure comes out on Tuesday?
Because individual member states report before the aggregate, so the market can build a reliable estimate of Tuesday’s number before it is published. Germany is the bloc’s largest economy and its flash HICP is the most heavily weighted single input. Friday’s French and Spanish prints already pointed to renewed energy-driven pressure, with France at 2.7% and Spain at 4.5%. If Germany comes in at or above the roughly 3.0% consensus on Monday, most of the repricing will happen that afternoon, and Tuesday’s euro-area release becomes a confirmation event rather than a surprise.
Does falling oil undermine the case for the ECB to keep tightening?
Over time, yes — and that is the central tension this week. Almost all of the euro area’s inflation overshoot has been energy-driven: July’s report showed energy prices up 10% year-on-year. Brent has now fallen 5.67% in a week to $88.28 as Gulf export flows recover through the Strait of Hormuz. If that holds, the energy contribution to headline HICP mechanically fades over the coming months. The complication is timing: August’s data reflects prices that were still elevated, so this week’s prints will look hot even as the forward-looking picture softens. CSFX sees that lag as the strongest argument for the ECB hiking in September and then stopping.
How does the UK bank holiday change how the week trades?
The London Stock Exchange is closed on Monday 31 August for the Summer Bank Holiday, which has two practical effects. The FTSE 100 has only four sessions and misses the German inflation print entirely, so it reopens on Tuesday having to price two days of news at once. Sterling liquidity is also thinner on Monday, which can exaggerate moves in GBP/USD on headlines that would normally be absorbed easily. CSFX would treat any sharp Monday move in the pound with caution and look to Tuesday’s European open for a more reliable read.
What did Warsh actually say at Jackson Hole, and why does it matter for European markets?
The Fed chair told the symposium that while the summer’s PCE and CPI readings came in better than expected, they did not convince him underlying inflation trends had meaningfully improved, and that the Fed must be confident inflation is moving to its objective clearly and quickly enough. He also described financial conditions as not currently restrictive. Markets read that as raising the odds of a September Fed hike, which lifted the dollar and knocked EUR/USD and GBP/USD lower on Friday. For European traders the read-through is straightforward: because US Treasuries and European sovereign debt are tightly correlated, a hawkish Fed tightens financial conditions for European corporates too, regardless of what the ECB does.
What is CSFX watching most closely for EUR/USD this week?
Tuesday’s core HICP first, because it determines whether the market keeps pricing tightening beyond September, and Friday’s US payrolls second, because it is the largest single dollar event of the week. Between them sit Thursday’s start of the ECB quiet period and the Treasury Committee hearings in London. The pair enters the week at 1.1585 with genuine support on both sides of the trade — a fully priced ECB hike behind the euro, a newly hawkish Fed behind the dollar — which is why CSFX is treating 1.1525 and 1.1712 as the working range rather than taking a directional view.
CSFX View · Week of 31 August 2026

CSFX View: Two Inflation Prints, a Closing Policy Window, and a Falling Oil Price Set the Tone for the Week Ahead


The week of 31 August – 4 September 2026 opens the European session with EUR/USD at 1.1585, off its August highs after Fed Chair Kevin Warsh’s hawkish Jackson Hole keynote lifted the dollar, and GBP/USD at 1.3590, which held up far better through Friday’s dollar rally. The DAX closed Friday at a record 26,569.99 on the back of a 1.66% weekly gain led by autos, while the broader STOXX 600 at 655.16 recovered from a mid-week wobble driven by French fiscal concerns and remains just below its 7 August record. The FTSE 100 at 10,824.27 sits close to record territory but faces a four-session week with London closed on Monday. Brent Crude at $88.28 has fallen 5.67% as flows through the Strait of Hormuz improve and Iran and Oman agree a revenue-sharing framework for the waterway.

Monday and Tuesday carry the week: Germany’s flash HICP is expected near 3.0% and the euro-area flash estimate near 3.1% headline with 2.6% core, the final inflation readings before the ECB’s 10 September decision, after which the Governing Council’s quiet period closes the policy window from around Thursday. A 25 basis point hike to 2.50% is fully priced, so the live question is what survives beyond it — swap markets imply close to one further increase, while Reuters reported that policymakers are reluctant to promise anything more. For equities, the DAX and STOXX 600 have been carried by cheaper oil and resilient tech sentiment, and a firm core print is the clearest threat to that leadership. For sterling and the FTSE 100, Thursday’s Treasury Committee hearings and Friday’s US payrolls are the two sessions that matter.

CSFX’s key levels for the week: watch 1.1525 support and 1.1712 resistance on EUR/USD around Tuesday’s core HICP, and 1.3450 support and 1.3677 resistance on GBP/USD into Thursday’s parliamentary hearings. The DAX is constructive between 26,100 support and 27,000 resistance after Friday’s record close, with the STOXX 600 tracking between 645.00 and 663.41 on the same euro-area data. The FTSE 100’s next test is 11,000 resistance with 10,700 as key support across its shortened week, while Brent Crude trades between $85.00 support and $92.50 resistance as the Hormuz risk premium continues to unwind. CSFX will issue intra-week alerts if Monday’s German print diverges materially from the 3.0% consensus, if Tuesday’s core reading moves post-September ECB pricing, if the Treasury Committee hearings shift expectations for the 17 September BoE decision, or if the Iran–Oman framework around the Strait of Hormuz breaks down or accelerates. Follow all updates at capitalstreetfx.com.

New clients can also take advantage of a limited-time deposit bonus when they open an account this week, on top of the usual account benefits — tight spreads, high leverage, and access to 2000+ instruments across FX, commodities, indices, and crypto. Full terms and other promotions are available on the CSFX website.

Trade European Markets at CSFX →