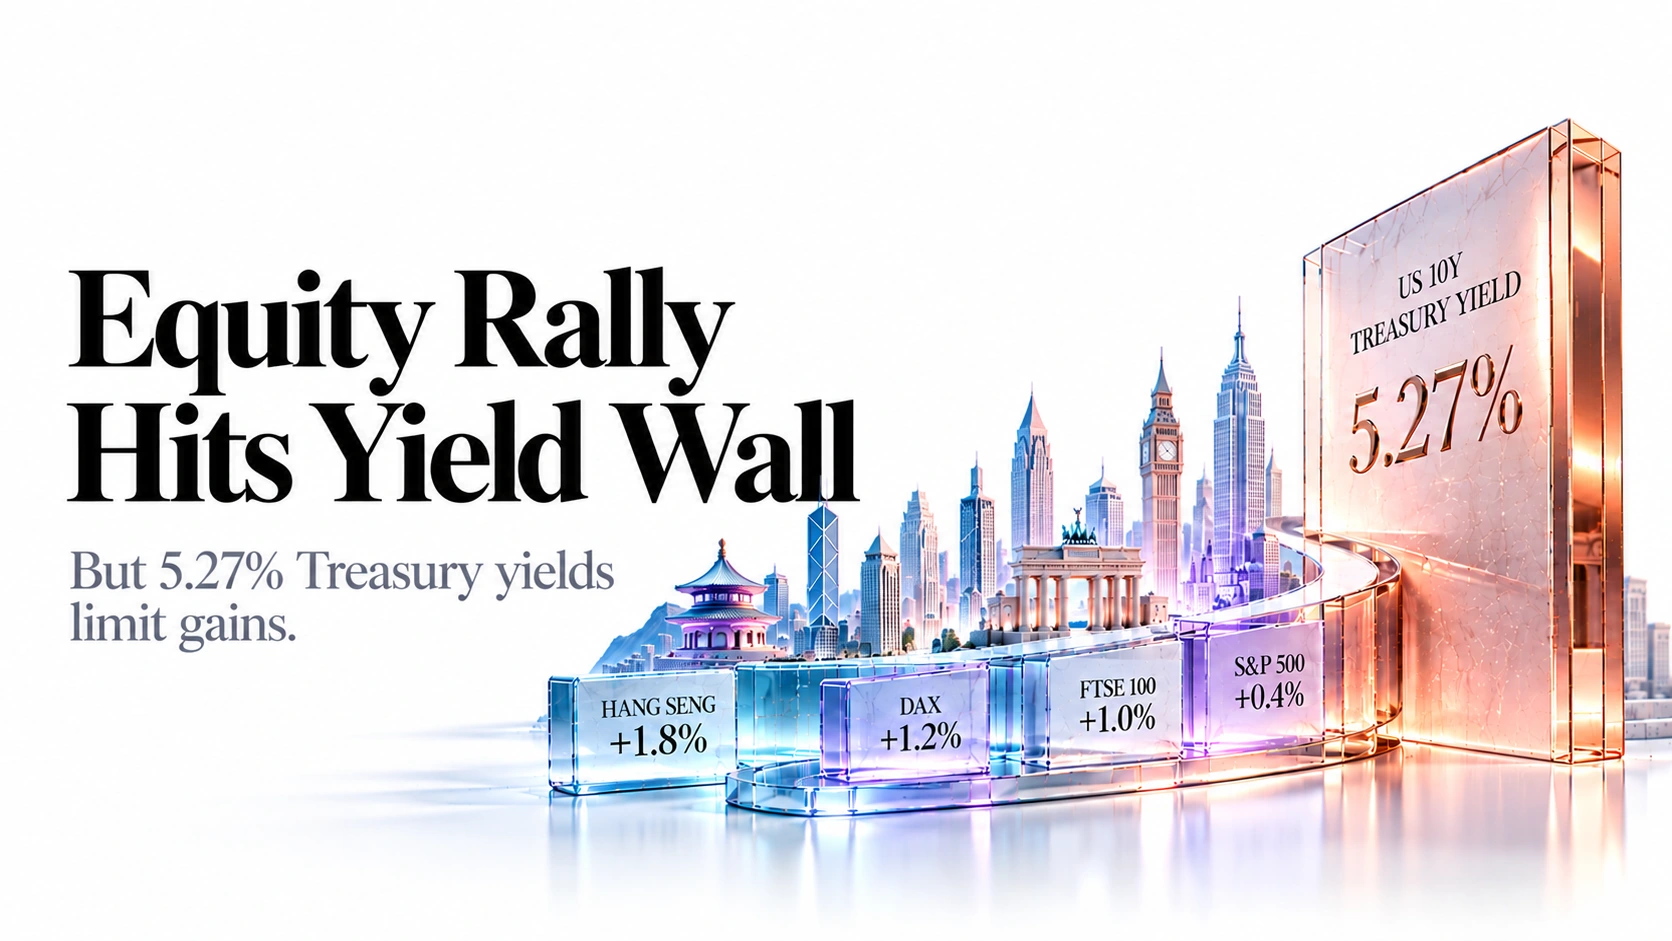
Relief Rally Rolls Around the Globe: Hang Seng Surges 1.8%, DAX and FTSE 100 Roar Back Over 1% – but Bond Yields Refuse to Back Down, US 10Y at 5.27%, EU 20Y at 3.86% | 9 October 2026
Relief Rally Rolls Around the Globe: Hang Seng Surges 1.8%, DAX and FTSE 100 Roar Back Over 1% – but Bond Yields Refuse to Back Down, US 10Y at 5.27%, EU 20Y at 3.86%
Global markets steadied on Friday after a volatile week as President Trump said the US would not strike Iran before the 3 November midterms, pulling oil back from recent highs and easing pressure on bond markets. In Asia, Tokyo's Nikkei 225 finished flat at 69,030.92 while Hong Kong's Hang Seng rallied 1.79% to 24,211.35 on a tech rebound as mainland China returned from Golden Week. Europe staged a broad recovery: the DAX rose about 1.2% to 25,099 from a two-month low and the FTSE 100 gained about 1.04% to 10,551, led by software and mining shares. On Wall Street, the S&P 500 is up about 0.35% near 7,792 and the Dow about 0.4% near 51,464 as AI stocks recovered on OpenAI revenue reports.
Rates and data: The US 10-year Treasury yield is near 5.274% (+3.9 bp) after the preliminary UoM survey showed sentiment falling to a five-month low of 46.3 but one-year inflation expectations rising to 4.7%. The EU 20-year government bond yield rose about 3.3 bp to 3.855%, even as the 10-year Bund eased slightly to about 3.48%, a sign of long-end steepening. Canada lost 68,300 jobs in September, sending the loonie to a 19-month low. Brent trades near $104 and gold near $4,183. Prices are a snapshot taken during the ongoing US session after the European close and may have moved since; verify against live quotes before trading.
Top Stories Moving the Market
1. US inflation expectations rise again
The preliminary University of Michigan survey showed consumer sentiment falling to a five-month low of 46.3 from 48.1, but one-year inflation expectations rose to 4.7% from 4.6% and long-run expectations to 3.5% from 3.4%, the second monthly increase. That is the combination the Fed fears most: weaker households alongside rising inflation expectations. With the Fed funds rate at 4.00% after September's hike and officials such as Musalem and Waller signalling further firming, the report kept hike risk alive into the 28 October FOMC.
Market impact: US 10Y up about 3.9 bp to 5.274%; caps upside for the Dow and S&P 500; supports the dollar index near 102.3.
2. AI trade revives on OpenAI revenue reports
Reports that OpenAI expects to reach or exceed $70 billion in annualised revenue by year-end eased fears that AI spending is running ahead of income, reversing Thursday's tech sell-off. Chipmakers including Broadcom, Micron, Marvell, AMD and Lam Research gained more than 2% pre-market, and reports that SoftBank is seeking about $100 billion from Gulf investors for AI ventures added support. Apple was the exception, falling about 2.5% on reported iPhone 18 Pro production cuts.
Market impact: S&P 500 back within 0.7% of its 7,845 record; SAP and Sage lead Europe; Japan's AI names (Kioxia, SoftBank) still lag, leaving the Nikkei flat.
3. Global long-end bond yields stay near multi-decade highs
Bond markets remain the main constraint on equities. The US 10-year is close to its highest since 2007, the UK 10-year gilt is near 5.45% after long-dated gilts hit multi-decade highs this week, and the 10-year Bund is about 3.48% with the EU 20-year yield up at 3.855%. Central banks are still tightening: the ECB is at 2.65% after its September increase and the BoE at 3.75% with inflation above target. Friday's modest easing in European yields gave equities room to rebound.
Market impact: Banks and rate-sensitive sectors stay volatile; higher discount rates limit index valuations; key tests are US CPI (14 Oct), ECB (29 Oct) and BoE (5 Nov).
4. China returns from Golden Week
Mainland Chinese markets reopened after the National Day holiday, restoring Southbound Stock Connect flows into Hong Kong that had been suspended while the mainland was closed. Hong Kong had suffered in early October from thin liquidity, high global yields and a bank sell-off, so returning flows and a tech rebound lifted the Hang Seng 1.79%. The Shanghai Composite was flat at 3,813.79 as investors waited for third-quarter GDP and activity data next week.
Market impact: Hang Seng reclaims 24,000; China Enterprises Index up about 1.6%; next week's GDP will decide if the rebound can extend toward 24,600-25,000.
5. Metals rally lifts miners; telecoms sell off
Sector rotation shaped Europe's rebound. Gold rose about 1.2% to near $4,183, silver about 2.7% and copper about 2%, lifting Antofagasta, Fresnillo and Rio Tinto in London. On the other side, European telecoms slumped after SpaceX's spectrum acquisition raised fears of new competition for T-Mobile US: Deutsche Telekom, which owns 54% of T-Mobile US, fell more than 6%, and Vodafone and Airtel Africa dropped more than 3%.
Market impact: Miners helped the FTSE 100 gain about 1.04%; Telekom was the biggest drag on the DAX, though the index still rose about 1.18%.
6. Earnings and macro data: Tesco, Delta, Canada jobs
Company results and data drove single-stock and FX moves. Tesco extended gains after raising its full-year outlook and increasing its buyback to £950 million, while Delta Air Lines fell about 3% after missing earnings expectations and cutting guidance, a warning on consumer and travel demand. Canada lost 68,300 jobs in September against expectations of a 7,000 gain, with unemployment at 6.5%, sending the Canadian dollar to a 19-month low.
Market impact: Supports UK defensives and staples; adds caution on US consumer and travel stocks; USD/CAD near 1.4271 and BoC hike pricing under pressure.
Technical, Fundamental & Trade Ideas
Nikkei 225
INDEX · Japan · AI/tech wobble, weak yen, BoJ pathThe Nikkei 225 closed almost flat at 69,030.92 (-0.02%) on Friday after Thursday's 1.42% slide, so the index has stabilised rather than rebounded. Price holds above the 68,500 support zone that capped Thursday's selling, and the broader trend stays positive with the benchmark up about 5.7% over the month and more than 40% year on year. Resistance comes in at 69,500 and then the round 70,000 handle; a daily close below 68,500 would open 68,000 and shift the short-term picture to corrective. Levels are conditional.
Today's driver: Tokyo traded in a holiday-thinned session with South Korea and Taiwan closed, which reduced regional liquidity and kept moves small. The Nikkei 225 finished at 69,030.92 (-0.02%), effectively flat after Thursday's 1.42% fall, while the broader TOPIX rose 0.33% to 4,104.81. That gap matters: domestic and value stocks recovered, but the AI and semiconductor heavyweights that dominate the price-weighted Nikkei stayed under pressure, with Kioxia down about 2.2% and SoftBank also lower.
Currency and rates: USD/JPY near 158.30 is a tailwind for exporters such as autos, machinery and electronics, because every yen of weakness lifts overseas earnings when translated back. The trade-off is policy risk: talk of Japanese intervention near these levels is a two-way risk for the yen, and a 10-year JGB yield around 3.0% raises the discount rate on long-duration growth stocks. Elevated US Treasury yields (10-year near 5.27%) add a second layer of valuation pressure.
Positioning: The index is still up roughly 5.7% over the past month and more than 40% year on year, so it is consolidating from a strong run rather than breaking down, and its June peak near 73,000 remains a long-term reference.
What to watch: USD/JPY versus intervention signals, the next leg of the AI trade after OpenAI revenue reports helped US tech, and US CPI on 14 October for global yields. Fundamental bias: neutral to mildly positive; a weak yen supports earnings, but tech concentration and high global yields limit upside.

Hang Seng
INDEX · Hong Kong · Tech rebound, mainland reopening, China GDP next weekThe Hang Seng jumped 1.79% to 24,211.35, recovering most of Thursday's 1.43% drop and reclaiming the psychological 24,000 level. The index is still well below its mid-September area near 24,600-24,750, which now acts as the first resistance band, after the 2 October slide to about 23,972. Holding above 24,000 keeps the rebound intact; a close back below 23,750 would revive the early-October lows. Levels are conditional.
Today's driver: The Hang Seng rose 1.79% to 24,211.35, recovering Thursday's 1.43% loss, as technology shares rebounded and the China Enterprises Index gained about 1.6%. Mainland markets reopened after the National Day Golden Week holiday, with the Shanghai Composite up 0.05% to 3,813.79, which restored Southbound Stock Connect flows that had been suspended while the mainland was closed.
Why Hong Kong had room to bounce: On 2 October the index lost 2.6% in a single session, its steepest fall in more than six months, as HSBC, AIA and Standard Chartered dropped 5-6% on concerns over possible new UK bank taxes and rising global bond yields, with thin holiday liquidity amplifying the selling. Much of that was positioning rather than a change in earnings, so the return of mainland buyers and calmer oil prices triggered short covering in financials and tech.
Macro backdrop: China's growth remains held back by weak domestic demand and soft consumer spending, and the 10-year Chinese government bond yield near 1.70% shows how loose financial conditions are compared with the US. A firmer yuan (USD/CNY near 6.69) eases capital-outflow worries, but US yields near 19-year highs still cap valuations for rate-sensitive Hong Kong property and growth stocks.
What to watch: China's third-quarter GDP, retail sales and industrial output next week, any new stimulus signals, and Southbound flow data. Fundamental bias: constructive above 24,000 on flows and cheap valuations, but a disappointing GDP print would test the rebound.

FTSE 100
INDEX · UK · Software and miners lead, gilts near multi-decade highsThe FTSE 100 rose 1.04% to about 10,551, halting a two-day decline and moving back above the 10,450 area where Thursday's selling stalled (prior close 10,441.60). The index is still about 0.6% lower on the month and roughly 4% below its July record near 10,991, so 10,600 and then 10,700 are the levels to beat. Support sits at 10,450 then 10,400. Levels are conditional.
Today's driver: The FTSE 100 gained about 1.04% to 10,551, ending a two-day decline and heading for a weekly gain of about 0.7%. Software and data names led, with Sage up about 4% and RELX about 3.2%, while miners such as Antofagasta, Fresnillo and Rio Tinto rose on firm copper, silver and gold prices. Defensive heavyweights also recovered, with AstraZeneca and GSK up about 1.5% after falling 2-3% on Thursday.
Company news: Tesco added about 2.8% as Deutsche Bank and Jefferies reacted positively to Thursday's interim results, which showed adjusted operating profit up about 6.3% to £1.78 billion, a raised full-year outlook and a larger £950 million buyback. On the downside, Vodafone (-3.8%) and Airtel Africa (-3.4%) followed a wider European telecom sell-off, and oil majors BP and Shell slipped as crude eased.
Rates and policy: The index's main fundamental headwind is the gilt market. The 10-year gilt yield is near 5.45% and long-dated yields hit multi-decade highs this week as energy costs fed inflation fears; banks fell about 2% on Thursday on higher funding costs. UK inflation was 3.1% in August with Bank Rate at 3.75%, and markets still see BoE hike risk into the 5 November meeting, with the UK Budget a further fiscal test.
Fundamental bias: neutral to positive. The FTSE's mix of miners, energy, pharma and dividend payers makes it more defensive than the DAX, but a renewed gilt sell-off would hit banks and housebuilders.

DAX 40
INDEX · Germany · Bounce from two-month low, SAP up, Telekom downThe DAX climbed about 1.18% to 25,099 after touching a two-month low on Thursday (close 24,806.97). The bounce puts price back above 25,000, but the index is still about 1% lower on the month and roughly 5.7% below its August record near 26,628. Resistance is 25,300 then 25,500; support is 24,950 then the 24,800 low. A close below 24,800 would resume the September-October downtrend. Levels are conditional.
Today's driver: The DAX rose about 1.18% to 25,099, bouncing from a two-month low set on Thursday, when it fell 1.18% to 24,807 as Volkswagen, Fresenius and Infineon dropped more than 3%. Friday's recovery was broad, with the mid-cap MDAX up about 1.7%, showing domestic stocks joined the rally rather than only the large exporters.
Stock moves: SAP and Zalando gained more than 3%, Siemens about 2.6% and Deutsche Post about 2.4%, while Heidelberg Materials rose about 2.6% after an RBC upgrade. Deutsche Telekom was the clear drag, falling more than 6%, after SpaceX's spectrum acquisition raised fears of new competition for T-Mobile US, in which Telekom owns a 54% stake. Rheinmetall was little changed and remains around 50% below year-ago levels as the defence trade has faded.
Economy: German data are mixed. Industrial output in August rose by the most in 17 months and the composite PMI was confirmed at 53.8, but exports fell for a second month and factory orders slumped on a reversal of large orders. Inflation has risen to 3.3%, unemployment is 6.4%, and the ECB has raised its policy rate to 2.65%, pushing the 10-year Bund yield to about 3.48%. Lower oil prices help Germany as a major energy importer.
Fundamental bias: neutral. Earnings in software and industrials support dips toward 25,000, but tighter ECB policy and weak exports cap the upside before the 29 October ECB meeting.

Dow Jones
INDEX · US · UnitedHealth and Amazon up, Apple dragsThe Dow Jones Industrial Average is up about 0.44% near 51,464 in the US session, adding to a positive open. The blue-chip index is roughly 1.3% lower on the month and has lagged the S&P 500, so the move is a recovery inside a range rather than a breakout. Resistance is 51,700 then 52,000; support is 51,100 then 50,800. A slip below 51,100 would put the weekly range low back in play. Levels are conditional.
Today's driver: The Dow Jones is up about 0.44% near 51,464. UnitedHealth (+3.6%), Amazon (+1.6%) and Boeing (+0.9%) led the open, while Apple (about -2.1%) weighed after reports that it told some suppliers to cut component production for the iPhone 18 Pro and Pro Max. 3M and Home Depot also lagged, and Delta Air Lines fell about 3% after missing earnings expectations and cutting its outlook, a warning sign for consumer and travel spending.
Why the Dow lags the S&P 500: The blue-chip index is down about 1.3% over the past month while the S&P 500 is up about 2.6%. The Dow is price-weighted and heavy in industrials, healthcare, financials and consumer names that are more exposed to high borrowing costs, while it has less weight in the AI megacaps that are driving the broader market.
Macro backdrop: The Fed raised rates to 4.00% in September, US CPI is running at 3.4% and the unemployment rate has edged up to 4.2%. The Atlanta Fed's GDPNow model points to about 3.6% third-quarter growth, so the economy is still expanding, but US mortgage rates are at their highest since 2023. Friday's UoM survey showed sentiment at a five-month low of 46.3 and one-year inflation expectations at 4.7%, a difficult mix for consumer stocks.
Fundamental bias: neutral. Defensive healthcare and solid growth support the index, but rates near 19-year highs and a softening consumer cap rallies ahead of US CPI on 14 October.

S&P 500
INDEX · US · Tech rebound, OpenAI revenue reports, record high near 7,845The S&P 500 is trading near 7,792, up about 0.3% after rising as much as 0.4% earlier, and sits within roughly 0.7% of its record high near 7,845 set earlier in October. The index is up about 2.6% on the month and 0.6% on the week so far. A break above 7,845 would open 7,900; support is 7,750 then 7,700. Levels are conditional.
Today's driver: The S&P 500 is up about 0.35% near 7,792 after gaining as much as 0.4%, with the Nasdaq 100 up about 0.4%. Technology rebounded from Thursday's sell-off after reports that OpenAI expects to reach or exceed $70 billion in annualised revenue by year-end, easing fears that AI spending was running ahead of revenue. Broadcom, Micron, Marvell, AMD and Lam Research gained more than 2% before the open, and reports that SoftBank is seeking about $100 billion from Gulf investors for AI ventures added to the theme.
Leaders and laggards: Microsoft (+1.8%), Amazon (+2%) and Oracle (+4.4%) supported the index, Tesla rose about 3% after Elon Musk clarified who will own and operate Terafab, and consumer discretionary and real estate outperformed. Apple fell about 2.5% on reported iPhone 18 Pro production cuts, a reminder that the index is still heavily concentrated in a handful of megacaps.
Valuation and rates: The index is within about 0.7% of its record near 7,845, up about 2.6% on the month and nearly 19% year on year. The main fundamental risk is the discount rate: with the 10-year Treasury yield near 5.27%, the equity risk premium is thin and further yield gains could pressure multiples. Calm volatility (VIX near 15) shows investors are not hedging heavily.
Fundamental bias: positive while AI earnings momentum holds, but US CPI on 14 October and the 28 October FOMC are the key risks to the record-high test.

US 10Y Treasury Yield
BONDS · US · 19-year highs, Fed hike risk, inflation expectationsThe US 10-year Treasury yield is around 5.274%, up about 3.9 basis points on the day, after easing from earlier in the week when it reached about 5.33%. It remains near its highest levels since 2007, with the 5.20% area acting as support and 5.33% then 5.40% as resistance (higher yield means lower bond prices). A sustained move above 5.33% would signal a fresh leg of the sell-off. Levels are conditional.
Today's driver: The 10-year Treasury yield is near 5.274%, up about 3.9 basis points, after the preliminary University of Michigan survey showed one-year inflation expectations rising to 4.7% from 4.6% and long-run expectations to 3.5% from 3.4%. Headline sentiment fell to 46.3 from 48.1, but the bond market focused on the inflation component because it feeds directly into Fed thinking.
Recent context: Yields reached about 5.33% earlier in the week, close to the highest since 2007, before easing on Thursday after a 30-year bond auction and President Trump's comments on Iran, which pulled oil lower. Friday's move partly reverses that relief, showing that the market is still demanding a high term premium for inflation and fiscal risk.
Fed and economy: The Fed raised rates to 4.00% in September, and St. Louis Fed President Musalem and Governor Waller have both said further tightening may be needed. US CPI is 3.4%, GDPNow points to about 3.6% growth and unemployment is 4.2%, so the economy is not weak enough to force cuts. Higher yields are already feeding into mortgage rates, now at their highest since 2023, and keep the dollar index near 102.
What to watch: September CPI on 14 October, Fed speakers including Collins, and the 28 October FOMC. Fundamental bias: yields stay elevated in a 5.20%-5.33% range; a hot CPI print would risk a break higher, while softer inflation and calmer oil would favour a pullback.

EU 20Y Government Bond Yield
BONDS · Euro area · ECB hike pricing, long-end supply, French fiscal riskThe EU 20-year yield is up about 3.3 basis points at 3.855%, recovering from an intraday low of 3.809% and sitting right on its 20-day moving average near 3.853%. On the daily chart the yield has climbed inside a rising channel since early August, with channel support now near 3.80% and the 50-day average near 3.751% beneath it; the longer-term average near 3.62% confirms the uptrend. The late-September peak near 3.97% was rejected and early October saw a pullback, but buyers defended the lower channel line. RSI near 55 is neutral. Resistance is 3.90% then 3.97%; a daily close below 3.80% would break the channel and open 3.75%. Levels are conditional.
Today's driver: The EU 20-year yield rose about 3.3 basis points to 3.855% even though the 10-year Bund eased slightly to about 3.48%, so the euro curve steepened. Lower oil prices trimmed the near-term inflation premium, but investors are still demanding more compensation to hold long-dated paper, reflecting persistent inflation, heavy government issuance and uncertainty over how far the ECB will need to tighten.
ECB and inflation: The ECB raised its policy rate to 2.65% in September and markets still price further tightening, with German inflation at 3.3% and euro-area inflation near multi-year highs. The yield curve is upward sloping: shorter maturities around 3.0-3.1% sit well below the 20-year and 30-year area near 3.8-3.9%, showing investors want extra compensation for long-term inflation and fiscal risk.
Fiscal and spread risk: Germany's higher spending on defence and infrastructure is increasing long-end supply, while French fiscal concerns keep the France-Germany spread wide (French 10-year near 4.86%, Italian near 4.59%). Demand remains solid, though: Germany's first new 20-year bond sale earlier this year drew orders of more than €72 billion for €6.5 billion of paper, showing strong investor appetite at these yields.
What to watch: ECB speakers before the 29 October decision, euro-area inflation, European gas prices and any spillover from US Treasuries. Fundamental bias: yields biased higher inside the rising channel while inflation and supply pressures persist; a break below 3.80% would need softer inflation data or a dovish ECB signal.

Ongoing Session
Asian market: mixed, Hong Kong outperforms
Asian shares were mixed in holiday-thinned trade with South Korea and Taiwan closed. Tokyo's Nikkei 225 ended almost flat at 69,030.92 (-0.02%) after Thursday's 1.42% drop, as AI-related stocks stayed weak, while the TOPIX gained 0.33% to 4,104.81. Hong Kong's Hang Seng rallied 1.79% to 24,211.35 on a tech rebound, and the Shanghai Composite edged up 0.05% to 3,813.79 as mainland markets returned from the National Day holiday. Australia's ASX 200 rose about 0.6% to 8,716.60 and India's Sensex added about 1.2%. Oil fell back from recent gains after President Trump said the US would not strike Iran before the midterms.
European market: broad rebound led by Germany
European equities bounced after two days of heavy losses. The DAX rose about 1.18% to 25,099 from a two-month low, the FTSE 100 gained 1.04% to about 10,551 and the CAC 40 added about 0.8%, with the STOXX 600 up about 1%. Easing geopolitical risk pulled Brent toward $104 and helped Bund and gilt yields stabilise. Software (SAP, Sage, RELX) and miners (Antofagasta, Fresnillo) led on firm metals prices, while telecoms were the weak spot as Deutsche Telekom fell more than 6% and Vodafone more than 3%.
US session (ongoing): stocks up, yields firm
Wall Street opened higher and is holding gains: the S&P 500 is up about 0.35% near 7,792, the Nasdaq 100 about 0.4% and the Dow about 0.4% near 51,464. Tech rebounded on reports that OpenAI expects annualised revenue of $70 billion or more by year-end, and Tesla rose about 3%, while Apple fell on reported iPhone 18 Pro component cuts and Delta dropped after cutting its outlook. Preliminary UoM sentiment fell to 46.3 from 48.1 (five-month low), but one-year inflation expectations rose to 4.7%, nudging the 10-year yield up to about 5.27%.
Cross-asset: oil, gold, dollar and Canada
WTI crude is near $91 and Brent near $104, both slightly lower on the day after Iran de-escalation comments. Gold is up about 1.2% near $4,183 and silver about 2.7%. The dollar index is near 102.28 (+0.14%), with USD/JPY around 158.34. The Canadian dollar fell to a 19-month low after Canada lost 68,300 jobs in September versus expectations of a gain of around 7,000, with the jobless rate at 6.5%; USD/CAD trades near 1.4271.
Elsewhere in Global Markets
Mainland reopens flat
China returned from Golden Week with a muted session ahead of Q3 GDP data next week.
Sydney firmer
Australian shares gained with miners supported by firm copper and gold prices.
Paris lags Frankfurt
French stocks rose but trailed the DAX as fiscal risk keeps a premium on French assets.
Chipmakers recover
AI infrastructure names rebounded from Thursday's sell-off after OpenAI revenue reports.
Oil eases on Iran comments
Trump said no strike on Iran before the midterms, describing talks as productive.
Gold climbs with silver
Precious metals firmed alongside copper, supporting mining stocks in London.
Dollar treads water
The DXY holds just above 102 near its 18-month high as Treasury yields stay elevated.
Loonie at 19-month low
Canada shed 68.3K jobs in September versus a forecast gain, hitting the Canadian dollar.
Summary
Friday was a relief session for global equities. Asia was mixed, with the Nikkei 225 flat at 69,030.92 as AI names lagged and the Hang Seng up 1.79% at 24,211.35 on a tech rebound and the return of mainland traders. Europe bounced firmly from the week's lows, with the DAX up about 1.2% to 25,099 and the FTSE 100 up about 1.04% to 10,551 as softer oil and steadier yields helped software and mining shares. In the ongoing US session the S&P 500 (about 7,792) is pressing back toward its 7,845 record and the Dow (about 51,464) is modestly higher. The caution is in rates: the US 10-year yield is still near 5.27%, close to 19-year highs, as consumer inflation expectations climbed again, and the EU 20-year yield climbed to 3.855%. With Iran headlines, US CPI on 14 October and central bank meetings later in the month, rallies remain vulnerable to any renewed rise in yields or oil.
Frequently Asked Questions
Q:Why is the stock market up today?
A:Global stocks rose on Friday 9 October 2026 after President Trump said the US would not strike Iran before the 3 November midterms, which pulled oil lower and eased pressure on bond markets. AI stocks also rebounded on reports that OpenAI expects $70 billion or more in annualised revenue by year-end. The S&P 500 was up about 0.35%, the Dow about 0.44%, the DAX 1.18% and the Hang Seng 1.79%.
Q:Is the S&P 500 at a record high?
A:Not yet. The S&P 500 is near 7,792, about 0.7% below its record high near 7,845 set earlier in October. It is up about 2.6% on the month and nearly 19% year on year. A break above 7,845 would open the way to 7,900, while 7,750 is the first support. US CPI on 14 October and the Fed decision on 28 October are the main risks to a new record.
Q:Why is the Dow lagging the S&P 500?
A:The Dow is price-weighted and heavy in industrials, healthcare, financials and consumer stocks that are more exposed to high borrowing costs, and it holds less of the AI megacaps that are driving the market. Over the past month the Dow is down about 1.3% while the S&P 500 is up about 2.6%. Today Apple fell about 2% on reported iPhone 18 Pro production cuts, holding the Dow to a gain of about 0.44%.
Q:Why is the Hang Seng up today?
A:The Hang Seng jumped 1.79% to 24,211.35 as tech shares rebounded and mainland China returned from the Golden Week holiday, restoring Southbound Stock Connect flows. The index had fallen 2.6% on 2 October on worries over possible UK bank taxes, high global yields and thin holiday trading, which left room for a bounce. China's third-quarter GDP data next week is the next test.
Q:Why is the Nikkei flat today?
A:The Nikkei 225 closed at 69,030.92 (-0.02%) because AI and chip heavyweights such as Kioxia (-2.2%) and SoftBank fell, and they carry a large weight in the price-weighted index. Most Japanese stocks still rose: the broader TOPIX gained 0.33%. Trading was thin with South Korea and Taiwan closed, and the yen near 158.30 per dollar continues to support exporters.
Q:Why is the FTSE 100 up today?
A:The FTSE 100 rose about 1.04% to 10,551, ending a two-day losing run. Software stocks Sage (+4%) and RELX (+3.2%) led, miners Antofagasta and Fresnillo gained more than 3% on firm metals prices, and Tesco added about 2.8% after raising its outlook and lifting its buyback to £950 million. Vodafone (-3.8%) lagged, and gilt yields near multi-decade highs remain the main risk.
Q:Why is the DAX up today, and why did Deutsche Telekom fall?
A:The DAX climbed about 1.18% to 25,099, bouncing from Thursday's two-month low, with SAP and Zalando up more than 3% and Siemens about 2.6%. Deutsche Telekom fell more than 6% after SpaceX's spectrum acquisition raised fears of new competition for T-Mobile US, in which Telekom owns a 54% stake. The DAX is still about 5.7% below its August record near 26,628.
Q:Why is the 10-year Treasury yield so high?
A:The US 10-year yield is near 5.27%, close to its highest level since 2007, because inflation expectations keep climbing. The University of Michigan survey showed one-year expectations rising to 4.7% and long-run expectations to 3.5%. US CPI is running at 3.4%, the Fed raised rates to 4.00% in September and officials have signalled more tightening, so bond investors are demanding higher yields.
Q:Will the Fed raise interest rates in October?
A:A hike is a live risk but not certain. The Fed raised rates to 4.00% in September, and St. Louis Fed President Musalem and Governor Waller have said further tightening may be needed. Rising inflation expectations kept hike risk alive into the 28 October FOMC meeting. September CPI on 14 October is the key data point: a hot print would raise the odds, softer inflation would lower them.
Q:Why are European bond yields rising?
A:The EU 20-year government bond yield rose about 3.3 basis points to 3.855% because inflation is sticky (German CPI 3.3%), the ECB has raised rates to 2.65% and markets price more tightening. Higher German defence and infrastructure spending is adding long-dated bond supply, and French fiscal worries keep spreads wide. A close above 3.90% would signal renewed pressure on European stocks.
Q:Why are oil prices falling today?
A:Brent eased to about $104 and WTI to about $91 after President Trump said the US would not strike Iran before the 3 November midterms and described talks as productive. The pledge only runs to the midterms, so oil remains the biggest swing factor for inflation expectations, bond yields and stock indices, especially for energy importers such as Japan and Germany.
Q:When is the next US CPI report and Fed meeting?
A:US September CPI is due on Wednesday 14 October, and the next Fed (FOMC) decision is on 28 October. Other key dates are China's third-quarter GDP next week, the ECB decision on 29 October, the US midterm elections on 3 November and the Bank of England decision on 5 November.
Q:What are the support and resistance levels for major indices today?
A:Support / resistance: S&P 500 7,750 / 7,845; Dow Jones 51,100 / 51,700; Nikkei 225 68,500 / 69,500; Hang Seng 24,000 / 24,600; FTSE 100 10,450 / 10,600; DAX 40 24,950 / 25,300; US 10Y 5.24% / 5.33%; EU 20Y 3.80% / 3.90%. These are conditional technical references, not forecasts.