Week Ahead, 14–18 September: Bank of England Decision and UK Inflation Frame the European Session as Brent Above $100 Keeps the Pressure On | European Session – Technical Analysis | 12-09-2026
Week Ahead, 14–18 September: Bank of England Decision and UK Inflation Frame the European Session as Brent Above $100 Keeps the Pressure On
UK Labour Market Tue 15 Sep · UK CPI Wed 16 Sep · Fed Decision Wed 16 Sep · BoE Rate Decision Thu 17 Sep · Euro-Area Final HICP Thu 17 Sep · UK Retail Sales Fri 18 Sep
For ongoing European Market Insights and Market Analysis, visit the CSFX Research Desk. This week’s European market outlook breaks down into four key threads:
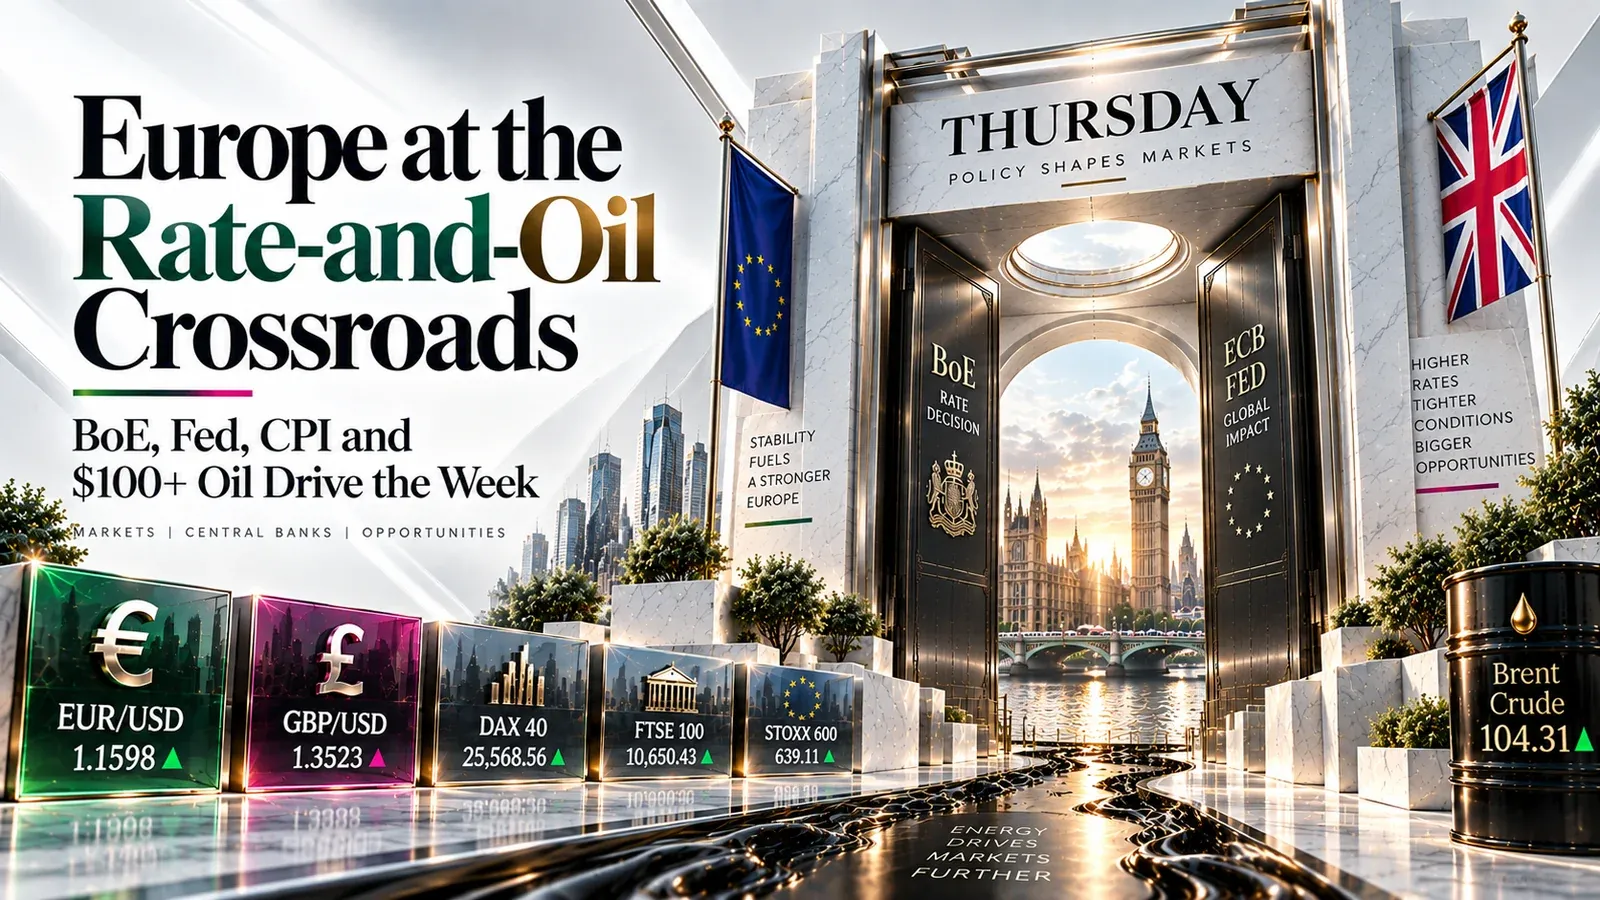
1. EUR/USD — a hawkish ECB meets an equally hawkish Fed, leaving the pair boxed in. EUR/USD at 1.1598 ends the week down 0.13%, holding just above the 1.1563 Fibonacci level, despite the European Central Bank raising its deposit rate to 2.50% on Thursday and warning that inflation will stay well above the 2% target for an extended period. Money markets have responded by pricing three more ECB hikes by March and a fourth by June, with an October move live. The offsetting force is the dollar: after a hot US producer price print, markets head into the week pricing roughly a 70% chance the Federal Reserve raises rates on Wednesday. CSFX sees the pair’s direction hinging on which central bank out-hawks the other rather than on euro-area data alone. For more EUR/USD technical analysis and daily Forex analysis, visit the CSFX research desk.
2. GBP/USD — the week’s busiest domestic calendar culminates in Thursday’s Bank of England decision. GBP/USD at 1.3523 was the only instrument in this report to finish the week higher, up a marginal 0.09%, after July GDP grew 0.4% month-on-month ahead of forecasts with services leading. Tuesday’s labour market report and Wednesday’s August CPI both land before the Monetary Policy Committee announces on Thursday. Governor Bailey has pushed back on the assumption that a hike is only a matter of time, and the rates market prices just a 25% chance of a move this week, with a full 25 basis points not priced until November. CSFX sees the vote split and any change to the inflation language as the more likely market movers than the rate decision itself. See our latest GBP/USD analysis and broader UK market analysis for updates through the week.
3. DAX and STOXX 600 — a bond-yield shock leaves European equities on the back foot. DAX 40 at 25,568.56 fell 1.83% on the week and the broader STOXX 600 at 639.11 lost 1.66%, both retreating sharply from record territory as the pan-European benchmark posted its worst week since April. The German 10-year yield sits near multi-decade highs and the US 10-year has pushed toward 5%. CSFX sees Thursday’s final euro-area and German inflation readings, plus the Fed and BoE decisions, as the tests of whether the rates repricing has run its course or has further to go.
4. FTSE 100 and Brent Crude — oil above $100 reshapes the whole European risk picture. FTSE 100 at 10,650.43 fell 1.67% on the week, essentially in line with its continental peers despite its energy and mining weighting, while Brent Crude at $104.31 gained 8.84% and printed a weekly high of $109.97 as the Strait of Hormuz crisis intensified. CSFX sees the oil price as the single most important variable for the week — it feeds directly into UK and euro-area inflation prints, central bank rhetoric, and the FTSE’s sector mix all at once.
Three Forces That Will Drive the European Session — 14 to 18 September 2026
The scheduled European-session catalysts that will set the direction across FX, equities, and commodities for the week of 14–18 September 2026
European Session Weekly Levels & Bias
Six instrument-specific reference levels for the week of 14–18 September 2026. All levels for reference and informational purposes only; not financial advice. Visit capitalstreetfx.com for live signals and other markets.
What to Watch — Two Hawkish Central Banks Cancelling Each Other Out
The euro failed to hold gains after the ECB’s hike to a 2.50% deposit rate, closing the week down 0.13% after rejecting from a high of 1.1654. Price now sits directly on the 1.1563 Fibonacci retracement, with the weekly moving average at 1.1555 forming the first line of defence below. Behind that is a dollar supported by a hot US PPI print and roughly a 70% market-implied probability of a Fed hike on Wednesday. CSFX sees the pair holding its range unless one side surprises: a Fed hold would open the path back toward 1.1654, while a Fed move with hawkish guidance risks a break below 1.1555 toward 1.1341.

What to Watch — The Week’s Heaviest Domestic Calendar, Ending With the BoE
Sterling was the only instrument in this report to close the week higher, edging up 0.09% and holding just below the 1.3570 Fibonacci level that has repeatedly capped the upside, with support at the 1.3436 moving-average cluster. July GDP growth of 0.4% month-on-month beat forecasts with services leading the expansion. Three domestic events now stack up in sequence: Tuesday’s labour market report, Wednesday’s August CPI, and Thursday’s Bank of England decision. With only a 25% chance of a hike priced, CSFX sees an unexpectedly hawkish vote split or a hot CPI print as the most plausible triggers for a break above 1.3570, while a dovish hold alongside a Fed hike would pressure the 1.3436 floor.

What to Watch — German Inflation Confirmation and the Direction of Bund Yields
The DAX posted the steepest weekly loss of the six instruments covered here, down 1.83% to 25,568.56 after failing at 26,070 and printing a low of 25,361. Price now sits just above the 25,506 Fibonacci retracement drawn from the 26,644 swing high, with the weekly moving average at 25,256 below that. Thursday’s final German HICP reading for August should confirm the 2.9% preliminary print, driven by energy inflation of 10.5% and heating oil up 49.6%. CSFX sees the index as most sensitive to the rates path rather than corporate news this week: stabilising Bund yields would support a recovery toward 26,070, while further yield pressure risks a test of 25,256 and then 24,584.

What to Watch — Whether the Rates Repricing Has Run Its Course
The pan-European benchmark fell 1.66% to 639.11, its worst week since April, after rejecting from 651.24 and printing a low of 635.68. The index remains well below its 664.05 swing high, with the weekly moving average at 637.74 sitting immediately beneath current price — a level that, if lost, opens the way toward 616.75. Energy names have been the notable exception, supported by Brent above $100. CSFX sees Thursday’s euro-area final HICP confirmation and the Fed and BoE decisions as the events most likely to determine whether the index holds the 630.00 area or extends its decline.

What to Watch — The Only Major Index With Both a Rate Decision and an Oil Tailwind
Despite a heavy energy and mining weighting that benefited directly from Brent’s move above $100, London still fell 1.67% on the week — essentially in line with the STOXX 600 and only marginally better than the DAX. The index rejected from 10,868 and now sits just above the 10,550 Fibonacci retracement taken from the 10,992 swing high, with the weekly moving average at 10,576 reinforcing that zone. A dense domestic calendar follows: Wednesday’s CPI, Thursday’s Bank of England decision, and Friday’s August retail sales. CSFX sees the index caught between a supportive commodity backdrop and the risk that hotter inflation forces the BoE to sound more hawkish than the 25% hike probability currently implies.

What to Watch — The Week’s Dominant Variable for Every Other European Instrument
Brent was the standout mover of the week, gaining 8.84% to close at $104.31 after reaching $109.97 — its strongest weekly candle since the spring — as the Strait of Hormuz crisis intensified, with WTI also topping $100 and US diesel passing $6 a gallon for the first time. Price has now reclaimed the $100.62 Fibonacci level, which converts prior resistance into the first support below. The move is central to the European rates story: the ECB has tied its tightening directly to the energy shock. CSFX sees further Gulf escalation as the clearest upside risk toward the $109.00–$109.97 band and then $119.69, while a credible diplomatic breakthrough would be the most powerful bullish catalyst available for European equities and the fastest route back below $100.62.

What Could Move European Markets Sharply This Week
The scheduled and unscheduled events that CSFX is watching most closely for the European session, 14–18 September 2026
European Session — Economic Calendar, 14–18 September 2026
All times approximate, Central European Time (CET/CEST) unless noted. Key releases for EUR/USD, GBP/USD, DAX 40, STOXX 600, FTSE 100, and Brent Crude.
| Day | Time (CET) | Release | Impact | Forecast | CSFX View |
|---|---|---|---|---|---|
| Monday, 14 September | |||||
| Mon | All Day | Post-ECB Positioning · Oil and Bond Yield Headlines | LOW | N/A | A light scheduled calendar leaves the session trading on the aftermath of the ECB decision, the direction of Bund and Treasury yields, and Gulf headline flow ahead of a heavy back half of the week. |
| Tuesday, 15 September | |||||
| Tue | ~08:00 CET | UK Unemployment Rate and Wage Growth (July) | MED | N/A | The first of three UK releases feeding into Thursday’s BoE decision. CSFX watches the earnings component for evidence of second-round effects from the energy shock. |
| Tue | Early CET | China Industrial Production & Retail Sales (August) | LOW | N/A | Lands before the European open; relevant to mining and luxury names across the DAX and STOXX 600, though unlikely to override the rates narrative this week. |
| Wednesday, 16 September | |||||
| Wed | ~08:00 CET | UK Consumer Price Index (August) | HIGH | N/A | The most consequential scheduled European-session release of the week, landing the morning before the MPC announces. An upside surprise would force a rapid repricing of Thursday’s decision. |
| Wed | Evening CET | US Retail Sales (August) and Federal Reserve Rate Decision | HIGH | ~70% priced for +25bp | Lands after the European close. Roughly a 70% probability of a hike to 3.75%–4.00% is priced; the outcome sets the dollar tone for Thursday’s European session. |
| Thursday, 17 September | |||||
| Thu | ~08:00 CET | Germany Final HICP (August) | MED | 2.9% y/y | Expected to confirm the preliminary reading, with energy inflation at 10.5% and motor fuel up 27.7% year-on-year the notable components. |
| Thu | ~11:00 CET | Euro-Area Final HICP (August) | MED | 3.3% y/y | Full August data from Eurostat. CSFX watches the core and services components — 2.4% and 3.0% respectively in the flash estimate — for the counter-argument to aggressive ECB pricing. |
| Thu | ~13:00 CET | Bank of England Interest Rate Decision & MPC Vote Split | HIGH | Hold at 3.75% (~25% hike priced) | The week’s single most important event inside European trading hours. CSFX sees the vote split and the inflation language as more market-moving than the rate decision itself. |
| Friday, 18 September | |||||
| Fri | Early CET | Bank of Japan Interest Rate Decision | MED | ~90% priced for +25bp to 1.25% | Lands before the European open and completes the central bank week; relevant mainly through its effect on global bond yields and broad risk appetite. |
| Fri | ~08:00 CET | UK Retail Sales MoM (August) | MED | N/A | The week’s final UK data point, offering a read on whether higher fuel costs are starting to bite into consumer spending after Thursday’s BoE decision. |
European Session — Trader Questions Answered
Key questions from CSFX clients ahead of the Bank of England decision, UK inflation data, and euro-area inflation confirmation
CSFX View: Three Central Banks, a UK Inflation Print, and Oil Above $100 Set the Tone for the Week Ahead
The week of 14–18 September 2026 opens the European session after the region’s worst week since April. EUR/USD at 1.1598 finished 0.13% lower despite the ECB lifting its deposit rate to 2.50% on 10 September, because a hot US producer price print has markets pricing roughly a 70% chance of a Federal Reserve hike on Wednesday. GBP/USD at 1.3523 was the week’s only gainer among these six instruments, up 0.09% after July GDP grew 0.4% month-on-month ahead of forecasts. The DAX at 25,568.56 fell 1.83% and the STOXX 600 at 639.11 lost 1.66% in its worst week since April, as the German 10-year yield reached multi-decade highs. The FTSE 100 at 10,650.43 fell 1.67% despite its energy weighting, while Brent Crude at $104.31 gained 8.84% and printed a high of $109.97 as the Strait of Hormuz crisis intensified.
Thursday is the pivot point for the European session: the Bank of England announces at roughly 13:00 CET, with the rates market pricing only a 25% chance of a hike after Governor Bailey publicly pushed back on the assumption that tightening is inevitable. The build-up matters as much as the decision — Tuesday’s labour market report and Wednesday’s August CPI both land first, and an upside inflation surprise would force a rapid repricing. Wednesday evening brings the Fed, Friday morning the Bank of Japan, and Thursday also carries final euro-area and German HICP readings for August, expected to confirm 3.3% and 2.9% respectively. In equities, the DAX and STOXX 600 look to the direction of Bund yields more than to corporate news, while the FTSE 100 and Brent Crude remain the instruments most exposed to any shift in the Gulf.
CSFX’s key levels for the week: watch 1.1555 support and 1.1654 resistance on EUR/USD around Wednesday’s Fed decision, and 1.3436 support and 1.3570 resistance on GBP/USD into Thursday’s Bank of England announcement. The DAX is a watch between 25,256 support and 26,070 resistance as the rates repricing plays out, with the STOXX 600 tracking between 630.00 and 651.24 on the same driver. The FTSE 100’s next test is 10,868 resistance with 10,550 as key support, while Brent Crude trades between $100.62 support and $109.97 resistance as Gulf headline risk stays elevated. CSFX will issue intra-week alerts if UK CPI diverges materially from expectations, if the MPC vote split surprises in either direction, if the Fed’s guidance shifts the dollar sharply, or if the Strait of Hormuz situation escalates further. Follow all updates at capitalstreetfx.com.
For further reading, browse CSFX’s Weekly European market outlook archive, including previous European reports covering the run-up to this week’s central bank decisions.
New clients can also take advantage of a limited-time deposit bonus when they open an account this week, on top of the usual account benefits — tight spreads, high leverage, and access to 2000+ instruments across FX, commodities, indices, and crypto. Full terms and other promotions are available on the CSFX website.
Trade European Markets at CSFX →